Life Insurance For High Net Worth

Okay, let’s talk about life insurance. But not the kind you buy at the grocery store checkout with your gum. I’m talking about life insurance for high net worth—it’s like the...
Okay, let’s talk about life insurance. But not the kind you buy at the grocery store checkout with your gum. I’m talking about life insurance for high net worth—it’s like the private jet of financial planning.
You see, most of us buy a term life policy hoping it’ll cover the mortgage and maybe junior’s college tuition. It’s the sensible, beige sedan of protection. For high net worth folks, that’s like bringing a water pistol to a tsunami.
Why you need more than a "basic" policy
If your assets are closer to Scrooge McDuck’s vault than a piggy bank, your life insurance needs are a whole different animal. You’re not just replacing income; you’re protecting an empire.
Must Read
Think of it this way: you’ve spent decades building a beautiful Lego castle. A basic policy is a tiny umbrella. A high net worth policy? That’s a climate-controlled, earthquake-proof bunker for your bricks.
We’re talking about strategies so complex they’d make a hedge fund manager blush. It’s not “how much do I pay?” It’s “how do I pay zero taxes while my wealth grows tax-free?”
The "I already have millions, why bother?" moment
I once overheard a guy at a country club say, “Why do I need life insurance? My widow will inherit the beach house and the vineyard.” Cute, right? But then I pointed out the estate tax bill that comes with that inheritance. His face went from smug to "I just stepped on a sea urchin."
See, the government loves a big estate. They want a slice. High net worth insurance is the secret sauce that pays that tax bill so your heirs don’t have to sell the vineyard to cover Uncle Sam’s tab.
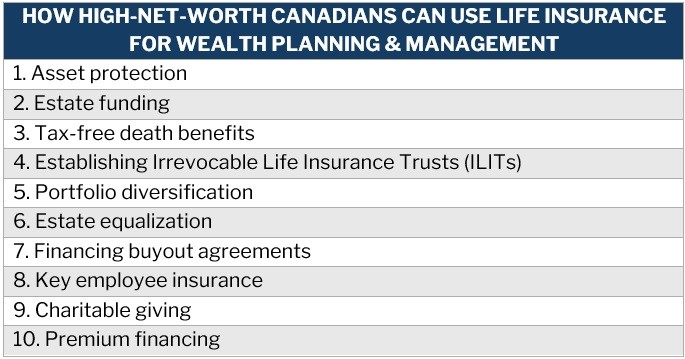
 10 High Net Worth Life Insurance Strategies Updated For 2026
It’s like having a designated driver for your legacy. You get to party with your wealth, and someone else (the insurance company) handles the messy cleanup.
Picking the right flavor: Whole Life, Universal Life, or Indexed?
Choosing between them is like choosing between a Porsche, a Ferrari, and a custom-built spaceship. They all get you there, but the vroom is different.
Whole Life is the classic. It’s the reliable, slightly boring gold watch you get at retirement. It builds cash value slowly, but it’s guaranteed. Think of it as your financial slow cooker—low and steady.
Universal Life is the flexible friend. You can tweak your premiums and death benefit like adjusting the seat in a luxury sedan. It’s great if you’re a “maybe I’ll buy another yacht next year” kind of person.
Then there’s Indexed Universal Life. This is the wild card. It’s tied to the stock market, but with a floor (you can’t lose money) and a cap (you can’t get too greedy). It’s like having a slot machine that never shows the lemon.
 Business And Wealth Archives | SmartWealth Financial Incorporated
The "cash value" secret
Here’s where it gets juicy. High net worth life insurance isn’t just a death benefit. It’s a living, breathing asset. You can borrow against the cash value tax-free to buy a vacation home or start a business.
Imagine your insurance policy silently accumulating cash like a magical couch that coughs up quarters. You don’t touch it for years, then—bam—it funds your kid’s startup while the market is tanking.
One CEO I know used his policy’s cash value to buy a failing competitor for pennies on the dollar. The bank laughed at his loan request. His own insurance policy didn’t. It’s the ultimate “bank of Me.”
The application process: Prepare for a slow dance
Don’t expect a quick online form. For high net worth, it’s a full-on medical and financial audit. They’ll ask about your hobbies (skydiving?), your health (cholesterol?), and your family tree (any rich uncles die suddenly?).
 Understanding Premium Finance for Life Insurance: A Powerful Strategy
It’s like the DMV, but with a lot more zeros and a much nicer waiting room. They might even ask for a cheek swab. Yes, a cheek swab to determine if you’re worth $50 million. Welcome to the club.
But the payoff? You get a policy that doubles as a tax shelter, an inheritance tool, and a rainy-day fund for the truly rich. It’s the Swiss Army knife of finance.
The bottom line (which is also a punchline)
Life insurance for high net worth isn’t about dying. It’s about living with the confidence that your wealth won’t be wasted on taxes, lawsuits, or a bad investment in a restaurant that serves only cauliflower.
So, if you’ve got a few million lying around, don’t just buy a term policy and call it a day. Go talk to a specialist. Tell them you want the “Scrooge McDuck vault” package—the one with the tax-free grow and the built-in skip-the-estate-tax button.
And if you don’t have a few million yet? Print this article, fold it into a paper airplane, and aim it at your future wealth. Because someday, you might just need that bunker for your Lego castle.
