Life Insurance For High Net Worth Individual

Let’s be honest: when you think life insurance, you probably picture a sad commercial with a family at a kitchen table, not a private jet over Monaco. For high net worth indiv...
Let’s be honest: when you think life insurance, you probably picture a sad commercial with a family at a kitchen table, not a private jet over Monaco. For high net worth individuals, the game changes entirely. This isn’t about covering a funeral or a mortgage—it’s about optimizing a legacy.
Think of it as the ultimate financial multitool. For the ultra-wealthy, a properly structured life insurance policy can do three things at once: transfer wealth tax-free, shelter assets from creditors, and even fund a family office. It’s the quiet powerhouse behind many dynasties you’ve heard of.
But here’s the fun part: it’s surprisingly personal. Did you know that Albert Einstein supposedly called compound interest the “eighth wonder of the world”? Well, high-net-worth life insurance is compound interest’s sophisticated cousin, wrapped in a cash-value jacket.
Must Read
The Policy That’s Actually A Portfolio
Forget term life—that’s for rookies. High net worth individuals lean into permanent life insurance like Whole Life or Universal Life, but with a twist. They use it as a tax-advantaged bank.
Here’s the secret: the cash value inside these policies grows tax-deferred, and you can borrow against it without triggering a taxable event. Imagine needing a quick $2 million for a vineyard in Tuscany—your policy says “oui” without the IRS knocking.
Practical tip: Work with an insurer that allows you to invest the cash value in alternative assets like real estate or private equity. Standard mutual funds are cute; timberland is powerful.
The Estate Planning Play
If you’ve ever whispered the words “estate tax” at a dinner party, you know the dread. For individuals with estates over $13.61 million (2024 federal exemption), Uncle Sam takes a hefty 40% cut on the way out.
Enter the Irrevocable Life Insurance Trust (ILIT). It’s like a financial invisibility cloak: the policy is owned by the trust, not you, so the payout bypasses your estate entirely. Your heirs get the cash, tax-free, while the taxman gets a shrug.
 Life Insurance for High Net Worth Individuals - Expert Guide
Fun fact: The Rockefeller family has used similar structures for generations. They didn’t build that wealth by paying unnecessary taxes—they built it by being annoyingly smart with life insurance.
Premium Financing: The Billionaire’s Discount
Let’s talk about the most glamorous part: premium financing. Instead of writing a massive check for a $50 million policy, you borrow the money from a bank to pay the premiums.
The bank is happy because you’re wealthy; the insurance company is happy because it gets a huge premium; you’re happy because your liquid cash stays invested in your hedge fund. It’s a financial love triangle with excellent returns.
Practical tip: This works best when the policy’s internal growth rate exceeds the loan interest rate. Currently, that spread is about 1-3%. Think of it as arbitrage on steroids, with a side of estate planning.
The Lifestyle Angle
Why does this matter to your daily life? Because freedom is the ultimate luxury. A well-designed policy means you can actually spend your money while alive, knowing your heirs are covered by a fortress of liquidity.
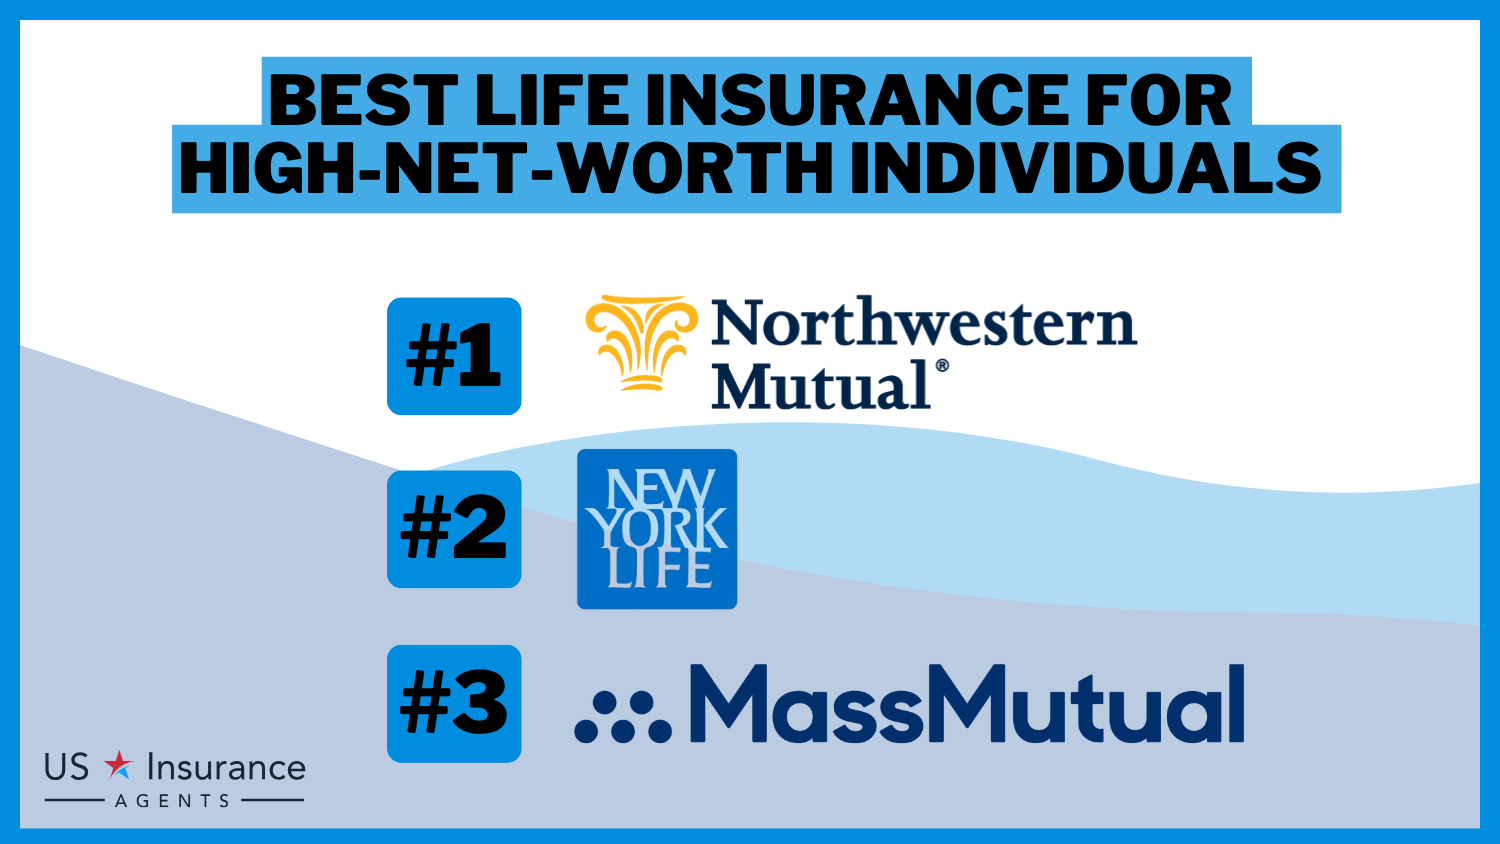 Best Life Insurance for High-Net-Worth Individuals in 2025
You can buy the sailboat. You can fund the art collection. You can take that helicopter skiing trip in British Columbia. The policy quietly works in the background, like a butler who never needs a day off.
Here’s a cultural nod: In The Great Gatsby, Jay Gatsby threw wild parties but died with no legacy. Don’t be Gatsby. Be the person who understands that protection is the foundation of indulgence.
Three Red Flags To Avoid
First, variable universal life with overly aggressive investments. It’s like betting your life insurance on a meme stock—thrilling, but likely to end in tears. Stick to policies with solid guarantees.
Second, ignoring underwriting. Even billionaires get medical exams, and conditions like high cholesterol or a jet-set lifestyle (frequent travel to risky regions) can spike your premiums. Be honest, stay healthy, and fly commercial less.
Third, overfunding the policy without a strategy. More cash value isn’t always better; it can trigger “modified endowment contract” (MEC) rules, killing your tax advantages. Yes, the tax code has a name for your mistake.
 Understanding Premium Finance for Life Insurance: A Powerful Strategy
The Fun Little Fact
Did you know that the largest individual life insurance policy ever issued was for $201 million? It was taken out on a Silicon Valley tech founder. The premium alone was reportedly $5 million per year. That’s the cost of a small island, or one very large policy that makes sure the next generation keeps their ocean view.
For mere mortals (even rich ones), a $5-10 million policy is often enough. The point isn’t the number—it’s the intention behind it.
A Short Reflection
At the end of the day, life insurance for high net worth individuals isn’t about death. It’s about life—specifically, the life you want your family to have after you’re gone.
The next time you’re sipping a $300 bottle of wine or watching the sunset from a deck in the Hamptons, remember this: building wealth is a skill; preserving it is an art. And a good life insurance policy is the frame that keeps the whole picture beautiful.
So, call your advisor. Maybe skip the wine and grab a sparkling water. Then go plan your legacy—because even the highest net worth life is worth insuring with style.
