Net Worth Definition Assets Minus Liabilities

Okay, let’s be real for a second. The term “net worth” sounds like something only people on yachts talk about, right? You might picture a calculator that only goes to 10 milli...
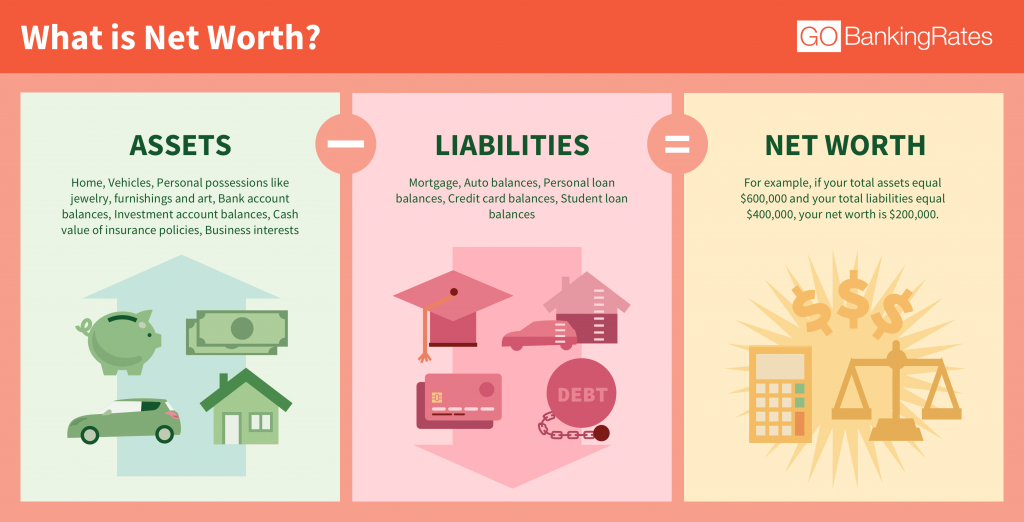
Okay, let’s be real for a second. The term “net worth” sounds like something only people on yachts talk about, right? You might picture a calculator that only goes to 10 million digits. But I promise, it’s way simpler, and honestly, a little bit fun once you get it. Think of it as the ultimate scorecard in the video game of your life—except the enemies are credit card debt and old subscriptions to magazines you never read.
So, What Exactly Is It?
Here’s the secret formula, and you don’t need a PhD in math to figure it out. Your net worth is simply everything you own minus everything you owe. That’s it. It’s the cold, hard truth of your financial universe, served up without any garnish. Think of it as a financial “selfie”—it captures exactly where you are this second, not where you wish you were.
The fancy finance people call your stuff “assets” and your bills “liabilities.” But I like to call them “the good pile” and “the annoying pile.” Your goal is to make the good pile so huge that the annoying pile is just a tiny speck in the rearview mirror.
Must Read
The Good Pile: Your Assets (The Fun Stuff)
Your assets are anything that puts money in your pocket or could be turned into cash. This includes your savings account, that rickety car you drive, and even the vintage guitar you bought at a garage sale. Even your retirement fund counts, even if it’s currently the size of a hamster’s snack stash.
Don’t forget your house if you own one, unless it’s a tent in your cousin’s backyard. And yes, that Beanie Baby collection your grandma gave you? Technically an asset, but let’s not quit your day job over it. The point is: everything you own has a value, even if that value is purely sentimental (or imaginary, in the case of my Beanie Baby, “Pinchers the Lobster”).
The Annoying Pile: Your Liabilities (The Not-So-Fun Stuff)
Liabilities are the money-monsters that try to eat your assets. This is your credit card balance, your student loans, that car loan, and any unpaid IOU you gave your roommate for pizza. Basically, if you owe someone money and they expect it back, it’s a liability. It’s the financial equivalent of a rain cloud following you around.
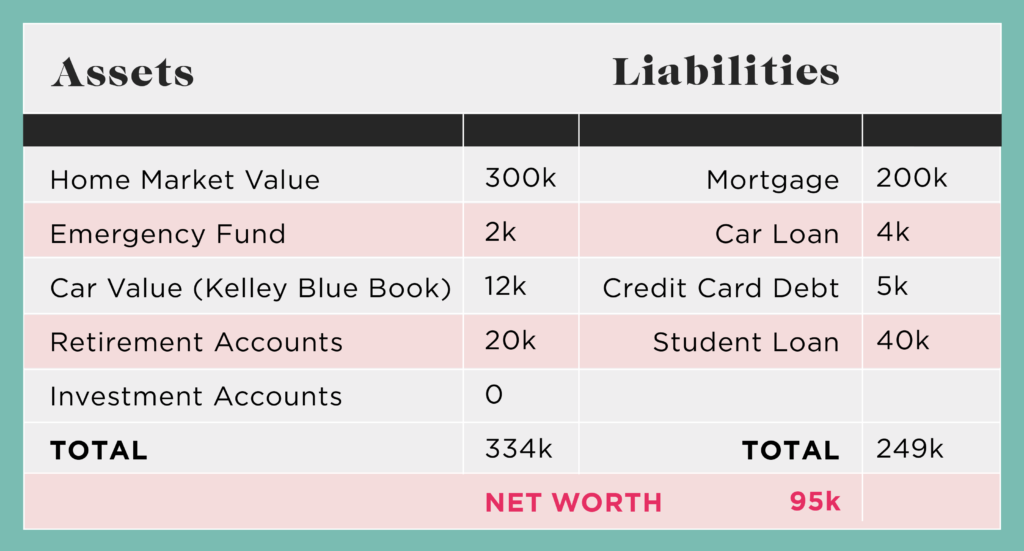 What Your "Net Worth" Is, Why You Should Always Know It, & How To
Even your mortgage is a liability, even though your house is an asset. (Yes, you can have both a good pile and an annoying pile at the same time. Life is weird like that.) The goal here is to shrink this pile until it’s smaller than a gnat’s allowance.
Putting It All Together: The Math (Don’t Panic)
Alright, let’s do the big reveal. You take the value of your good pile (say, $50,000 in savings, car, and a half-eaten bag of chips) and subtract the value of your annoying pile (say, $20,000 in credit card debt and a student loan). That equals a net worth of $30,000.
Now, what if your annoying pile is bigger than your good pile? Then your net worth is negative. You might be thinking, “Oh no, that’s terrible!” But hold on. A negative net worth is just a sign that you’re investing in your future (like student loans) or that you’re at the beginning of your journey. Even Elon Musk probably had a negative net worth when he was sleeping on a friend’s couch. So, breathe.
 What’s Your True Financial Standing: Calculating Net Worth
Why Should You Care About This Number?
Because your net worth is the most honest financial dashboard you’ll ever have. It doesn’t lie about how rich you look versus how rich you actually are. It’s like stepping on a scale that also tells you how much debt you’re hiding under your shirt. And tracking it over time is like watching a plant grow—slow, but incredibly satisfying when you see it get bigger.
You don’t need to check it every day (that’s weird). But once a month? Go for it. Watch it creep up as you pay off your car or add to your savings. It’s like leveling up in a RPG, but with less dragons and more dignity.
A Few Quick Rules for Your Financial Journey
First, assets are not fancy toys. A brand new car that loses half its value the second you drive it off the lot is a liability disguised as an asset. (It’s a financial wolf in sheep’s clothing.) Second, liabilities are not evil. Sometimes you need a loan to buy a house or start a business. Just don’t let them become your pets.
 Net Worth – Here’s Everything You Need To Know - How to Money
Finally, remember this secret: you can increase your net worth by either growing your assets or shrinking your liabilities. Or, if you’re feeling really fancy, both at the same time! It’s like getting a raise and cancelling a subscription you forgot about.
The Uplifting Conclusion (You Made It!)
Here’s the best part: your net worth is not your self-worth. Never confuse the two. Your value as a human being is infinite. Your net worth is just a number that changes every single day. It’s a tool, not a report card on your soul. Even if your net worth is currently in the negative, you have the power to make it positive—one paycheck, one paid-off bill, one smart choice at a time.
So, go grab a calculator (or just use your phone). Add up your good pile, subtract your annoying pile. Whatever number you get, smile. You now know the truth. And knowing the truth is the first step to winning the game. Plus, now you can casually say “my net worth is complex, but trending upward” at parties. You’re welcome, future millionaire. Now go be awesome.
