Net Worth Distribution In The United States

Okay, grab your coffee—or maybe a stiff drink—because we’re diving into the net worth distribution in the United States. Spoiler alert: it’s not exactly a level playing field....
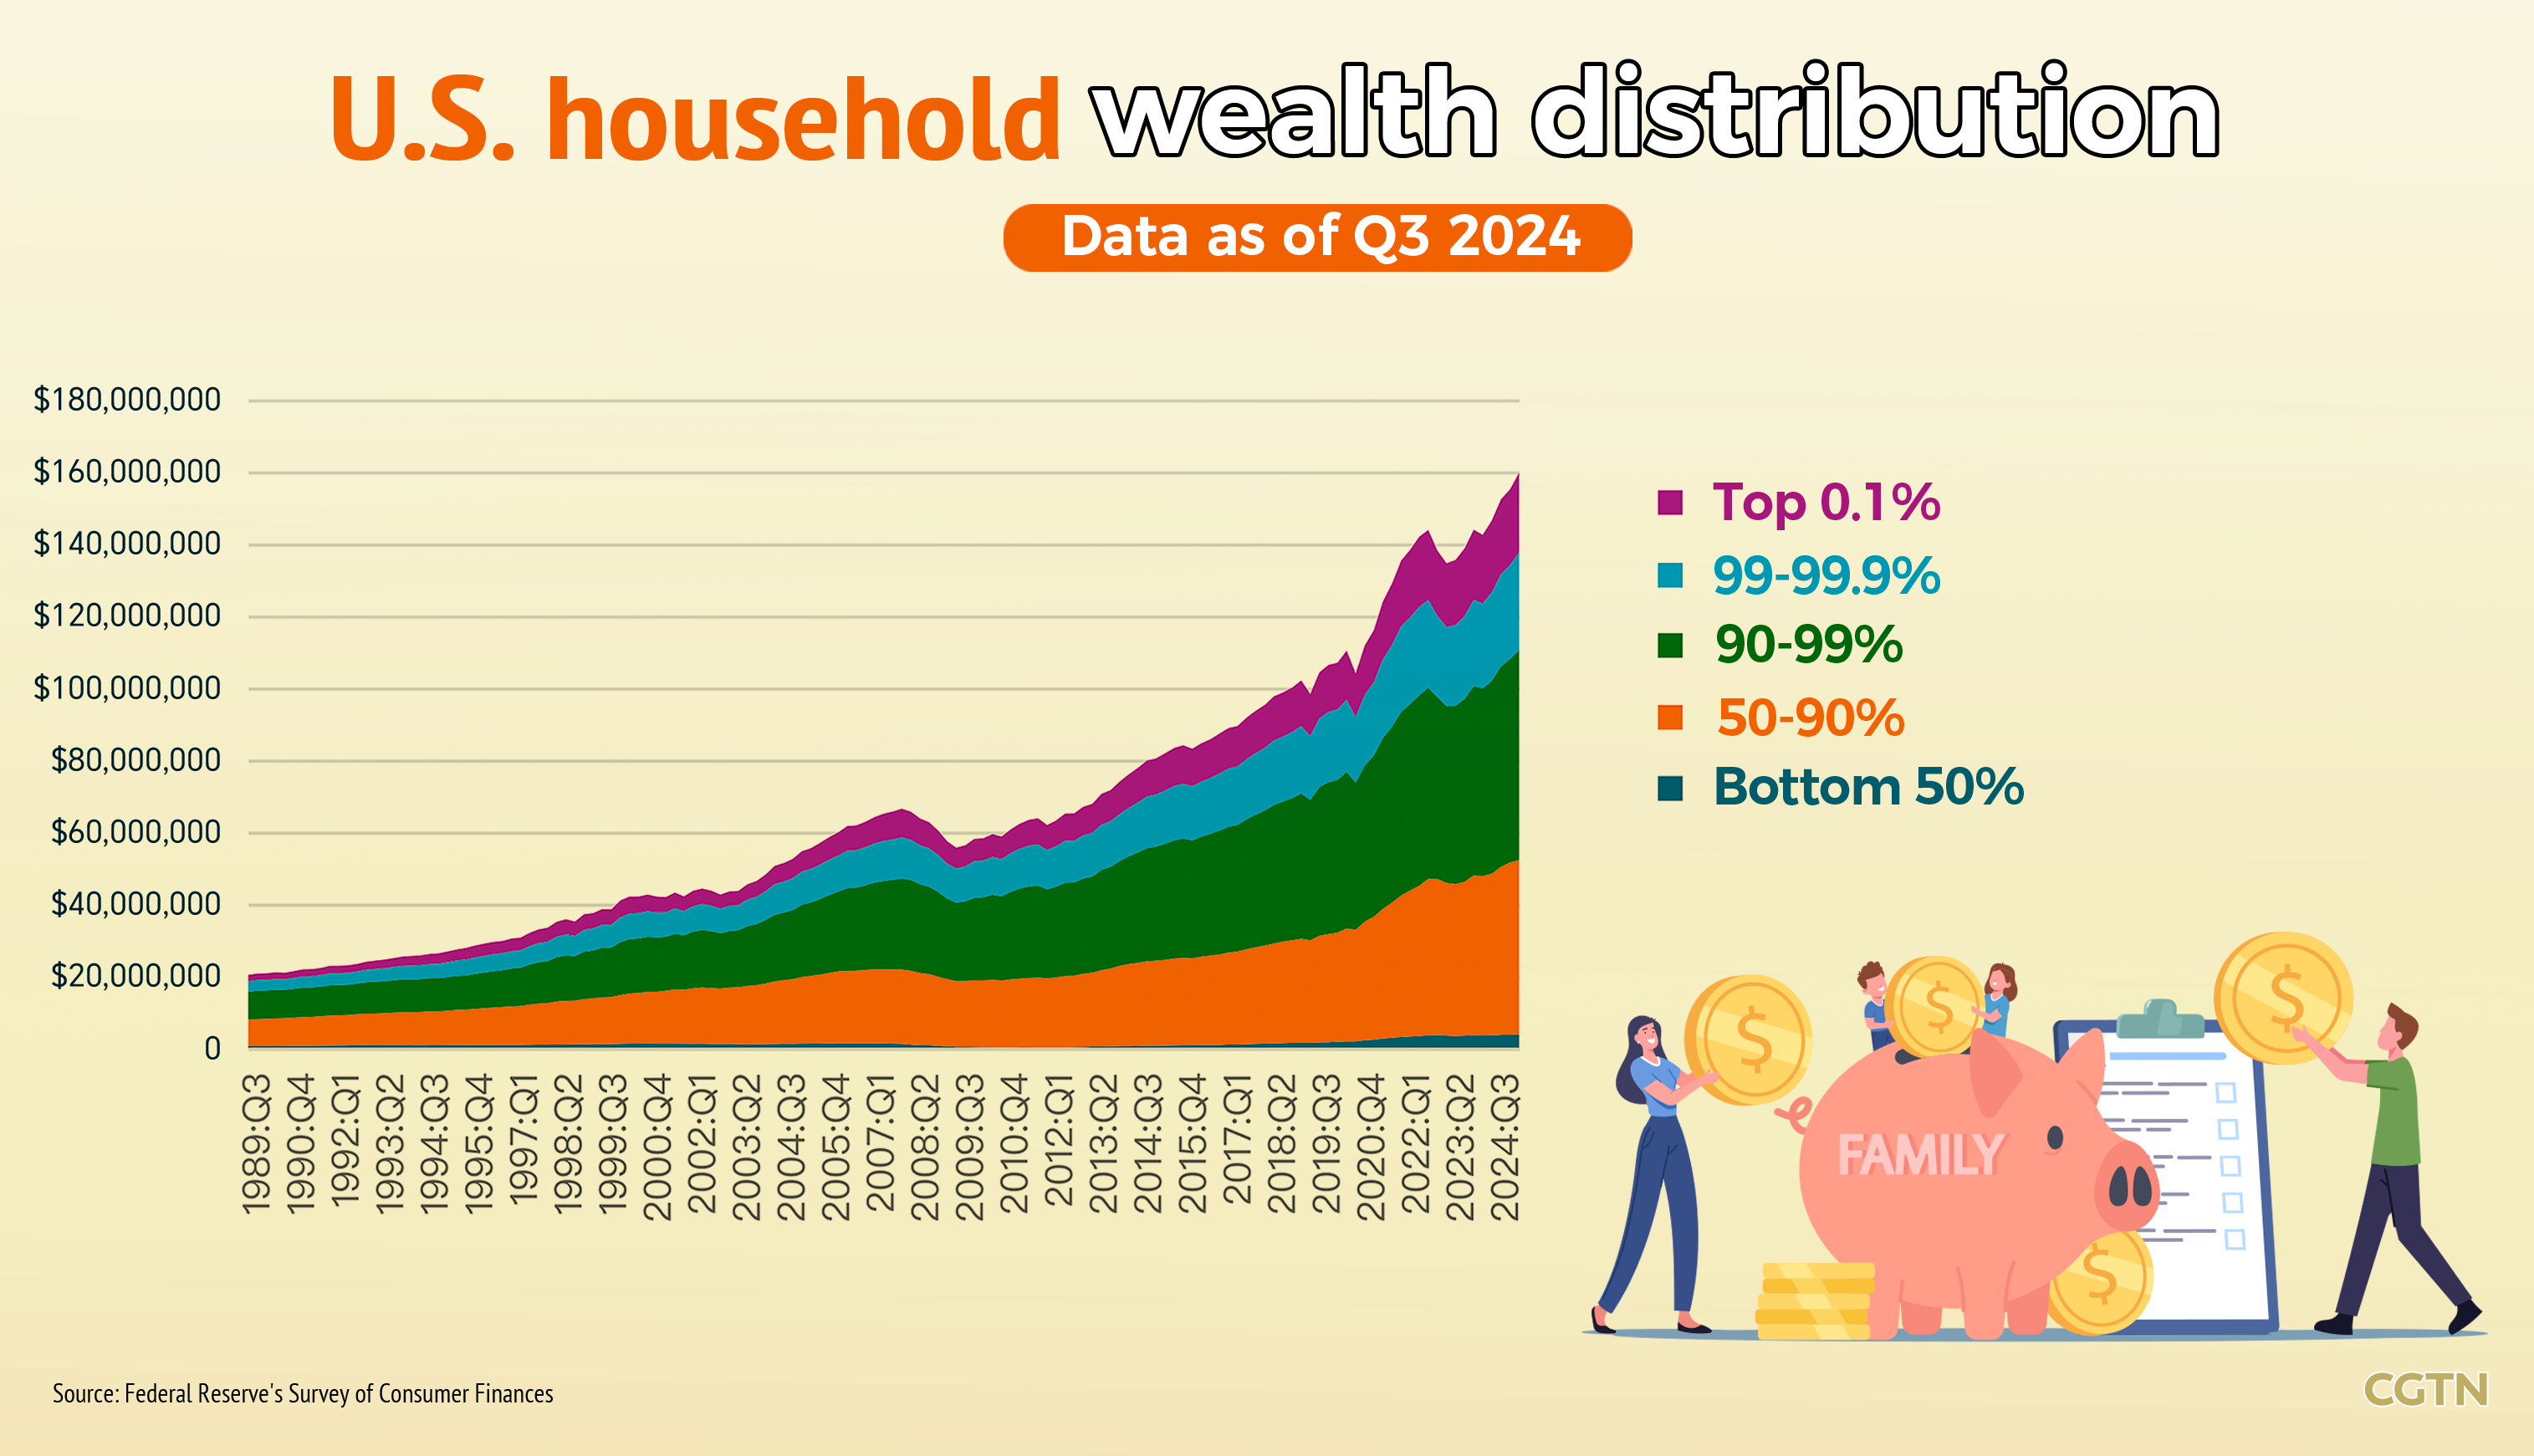
Okay, grab your coffee—or maybe a stiff drink—because we’re diving into the net worth distribution in the United States. Spoiler alert: it’s not exactly a level playing field. In fact, it’s more like a game where some folks started on third base while others are still looking for the stadium.
So, what are we even talking about?
Net worth is just your stuff minus your debt. That includes your house, savings, investments, and that vintage Beanie Baby collection you swear will pay off (it won’t). The distribution is how that wealth is sliced up among all of us—and the knife is very sharp.
Here’s the big picture: the top 10% of households hold about 70% of the country’s wealth. Meanwhile, the bottom 50%? They split a measly 2.6%. That’s not a typo. They’re fighting over crumbs while the upper crust has the whole bakery.
Must Read
The really rich vs. the rest of us
Let’s get specific. The top 1% controls nearly 32% of national wealth. For context, that’s more than the entire middle class combined. Does that make you want to laugh or cry? I’ll go with both.
Median net worth in the U.S. (the stuff in the middle) is about $193,000 as of 2023. Sounds decent, right? But then you realize that’s heavily skewed by massive wealth at the top. The average white family has a net worth of about $284,000; Black families average around $44,000. Yes, the racial wealth gap is real and it’s big.
Homeownership is the biggest driver of this. If you own a home, you’re probably sitting on a pile of equity. If you rent? You’re paying someone else’s mortgage. It’s like playing Monopoly, but one player starts with two hotels and the other has a thimble.
 Chart: 18% of American Households Hold 69% of Consumer Net Worth | Statista
How did we get here?
A few suspects: inheritance, stock market gains, and housing booms. If your parents bought a house in the 1980s for $50,000, congrats—that’s now worth $800,000. But if you’re starting out today? Good luck finding a fixer-upper for under a million.
The rich get richer isn’t just a saying—it’s math. People with stocks and businesses see their assets grow faster than wages ever do. Meanwhile, the bottom 50% rely heavily on social security and small savings accounts. Inflation eats those alive.
And let’s not forget student debt. It’s the modern-day anchor tying young people to the dock. The average graduate leaves school with over $30,000 in loans. That sets them back a decade on buying a house, starting a business, or even breathing confidently.
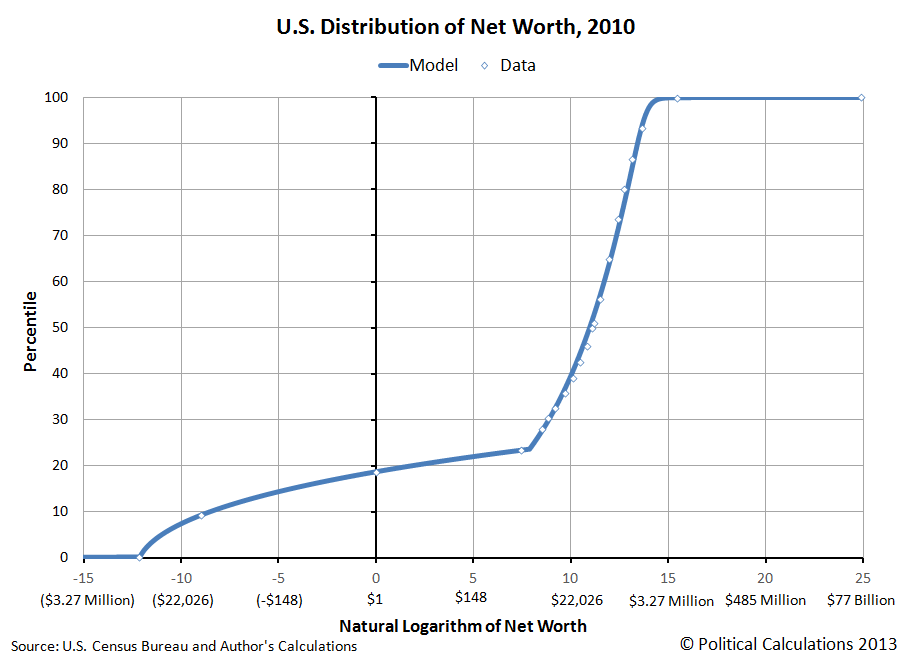 The Distribution of Net Worth in the United States - Business Insider
What does this mean for you and me?
It means luck plays a huge role. Were you born into wealth? Did you get a good education? Did a random uncle leave you a rental property? If you answered “no” to all three, you’re in the majority. And that’s okay—mostly.
But here’s the kicker: mobility is harder now. In the 1970s, you could work your way up from a diner job to a middle-class house. Today? That same diner job barely covers rent, let alone a down payment. The ladder got shorter, and the rungs are greased with avocado toast jokes.
I’m not saying this to depress you—I’m saying it because awareness is the first step. If you know the game is stacked, you can at least play smarter. Save what you can. Invest early. And for the love of all things holy, avoid credit card debt.
 13 Billionaire Maps & Facts Showing How Much Money They Have
Is there any good news?
Yeah, actually. The bottom 50% have seen modest gains in net worth over the last decade, mostly due to a rising stock market and a pandemic-era savings bump. The 2020 stimulus checks did temporarily boost savings for lower-income households. (Remember when we had money? Wild times.)
Also, generational wealth is finally getting attention. People are talking about reparations, baby bonds, and universal basic income. It’s not happening yet, but the conversation is louder than ever. Progress is slow, but it’s a start.
Finally, you can do small things. Invest in your skills. Use a high-yield savings account. Befriend an accountant. And maybe—just maybe—marry someone with a trust fund. (Kidding! Sort of.)
So what’s the takeaway? The net worth distribution in the U.S. is a tilted seesaw. A few people are on top, most of us are in the middle or bottom, and the whole thing needs a serious tune-up. But hey, at least we’re talking about it over coffee. That’s more than they did in the 1920s. Now, who wants another latte?
