Net Worth Is Assets Minus Liabilities Definition

So, picture this: my friend Sarah called me last week, practically in tears. She’d just added up her bank accounts, her 401(k), and the “value” of her vintage sneaker collecti...
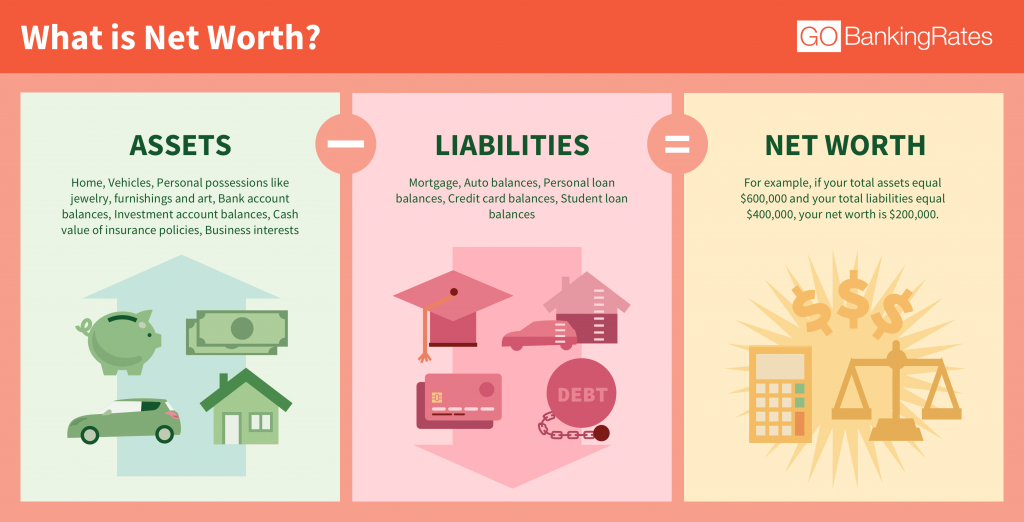
So, picture this: my friend Sarah called me last week, practically in tears. She’d just added up her bank accounts, her 401(k), and the “value” of her vintage sneaker collection—and proudly announced she was a millionaire on paper. Then she remembered her student loans, her car note, and that credit card she maxed out on a “once-in-a-lifetime” trip to Bali.
The math suddenly didn’t feel so good. Ouch. Her net worth wasn’t her assets alone; it was everything she owned minus everything she owed. That’s the brutal, beautiful truth of it.
The One-Liner That Changes Everything
Here’s the definition, plain and simple: Net worth = Assets – Liabilities. That’s it. No secret formulas, no fancy jargon, just a subtraction problem that tells you how much you’d have left if you sold everything and paid off every bill today.
Must Read
Think of it as your financial “reality check.” Your friend’s flashy car is an asset—until you remember the $30,000 loan that’s still sitting on it. Suddenly, that asset is wearing a big, ugly liability hat.
And yes, this applies to everyone, from your neighbor with the Tesla to the CEO of a Fortune 500 company. We’re all playing the same subtraction game.
Assets Aren’t Always What You Think
Let’s talk about assets for a second. Your house? Could be an asset. Your emergency fund? Definitely. But that Gucci handbag you bought “as an investment”? Spoiler alert: unless you’re flipping it for cash, it’s probably a liability disguised as a status symbol.
A true asset puts money into your pocket, not just your ego. A rental property that pays you rent every month? Heck yes. A boat that sits in the marina costing you dock fees? Pfft, that’s a money pit, my friend. (Sorry, boat lovers—I see you wincing.)
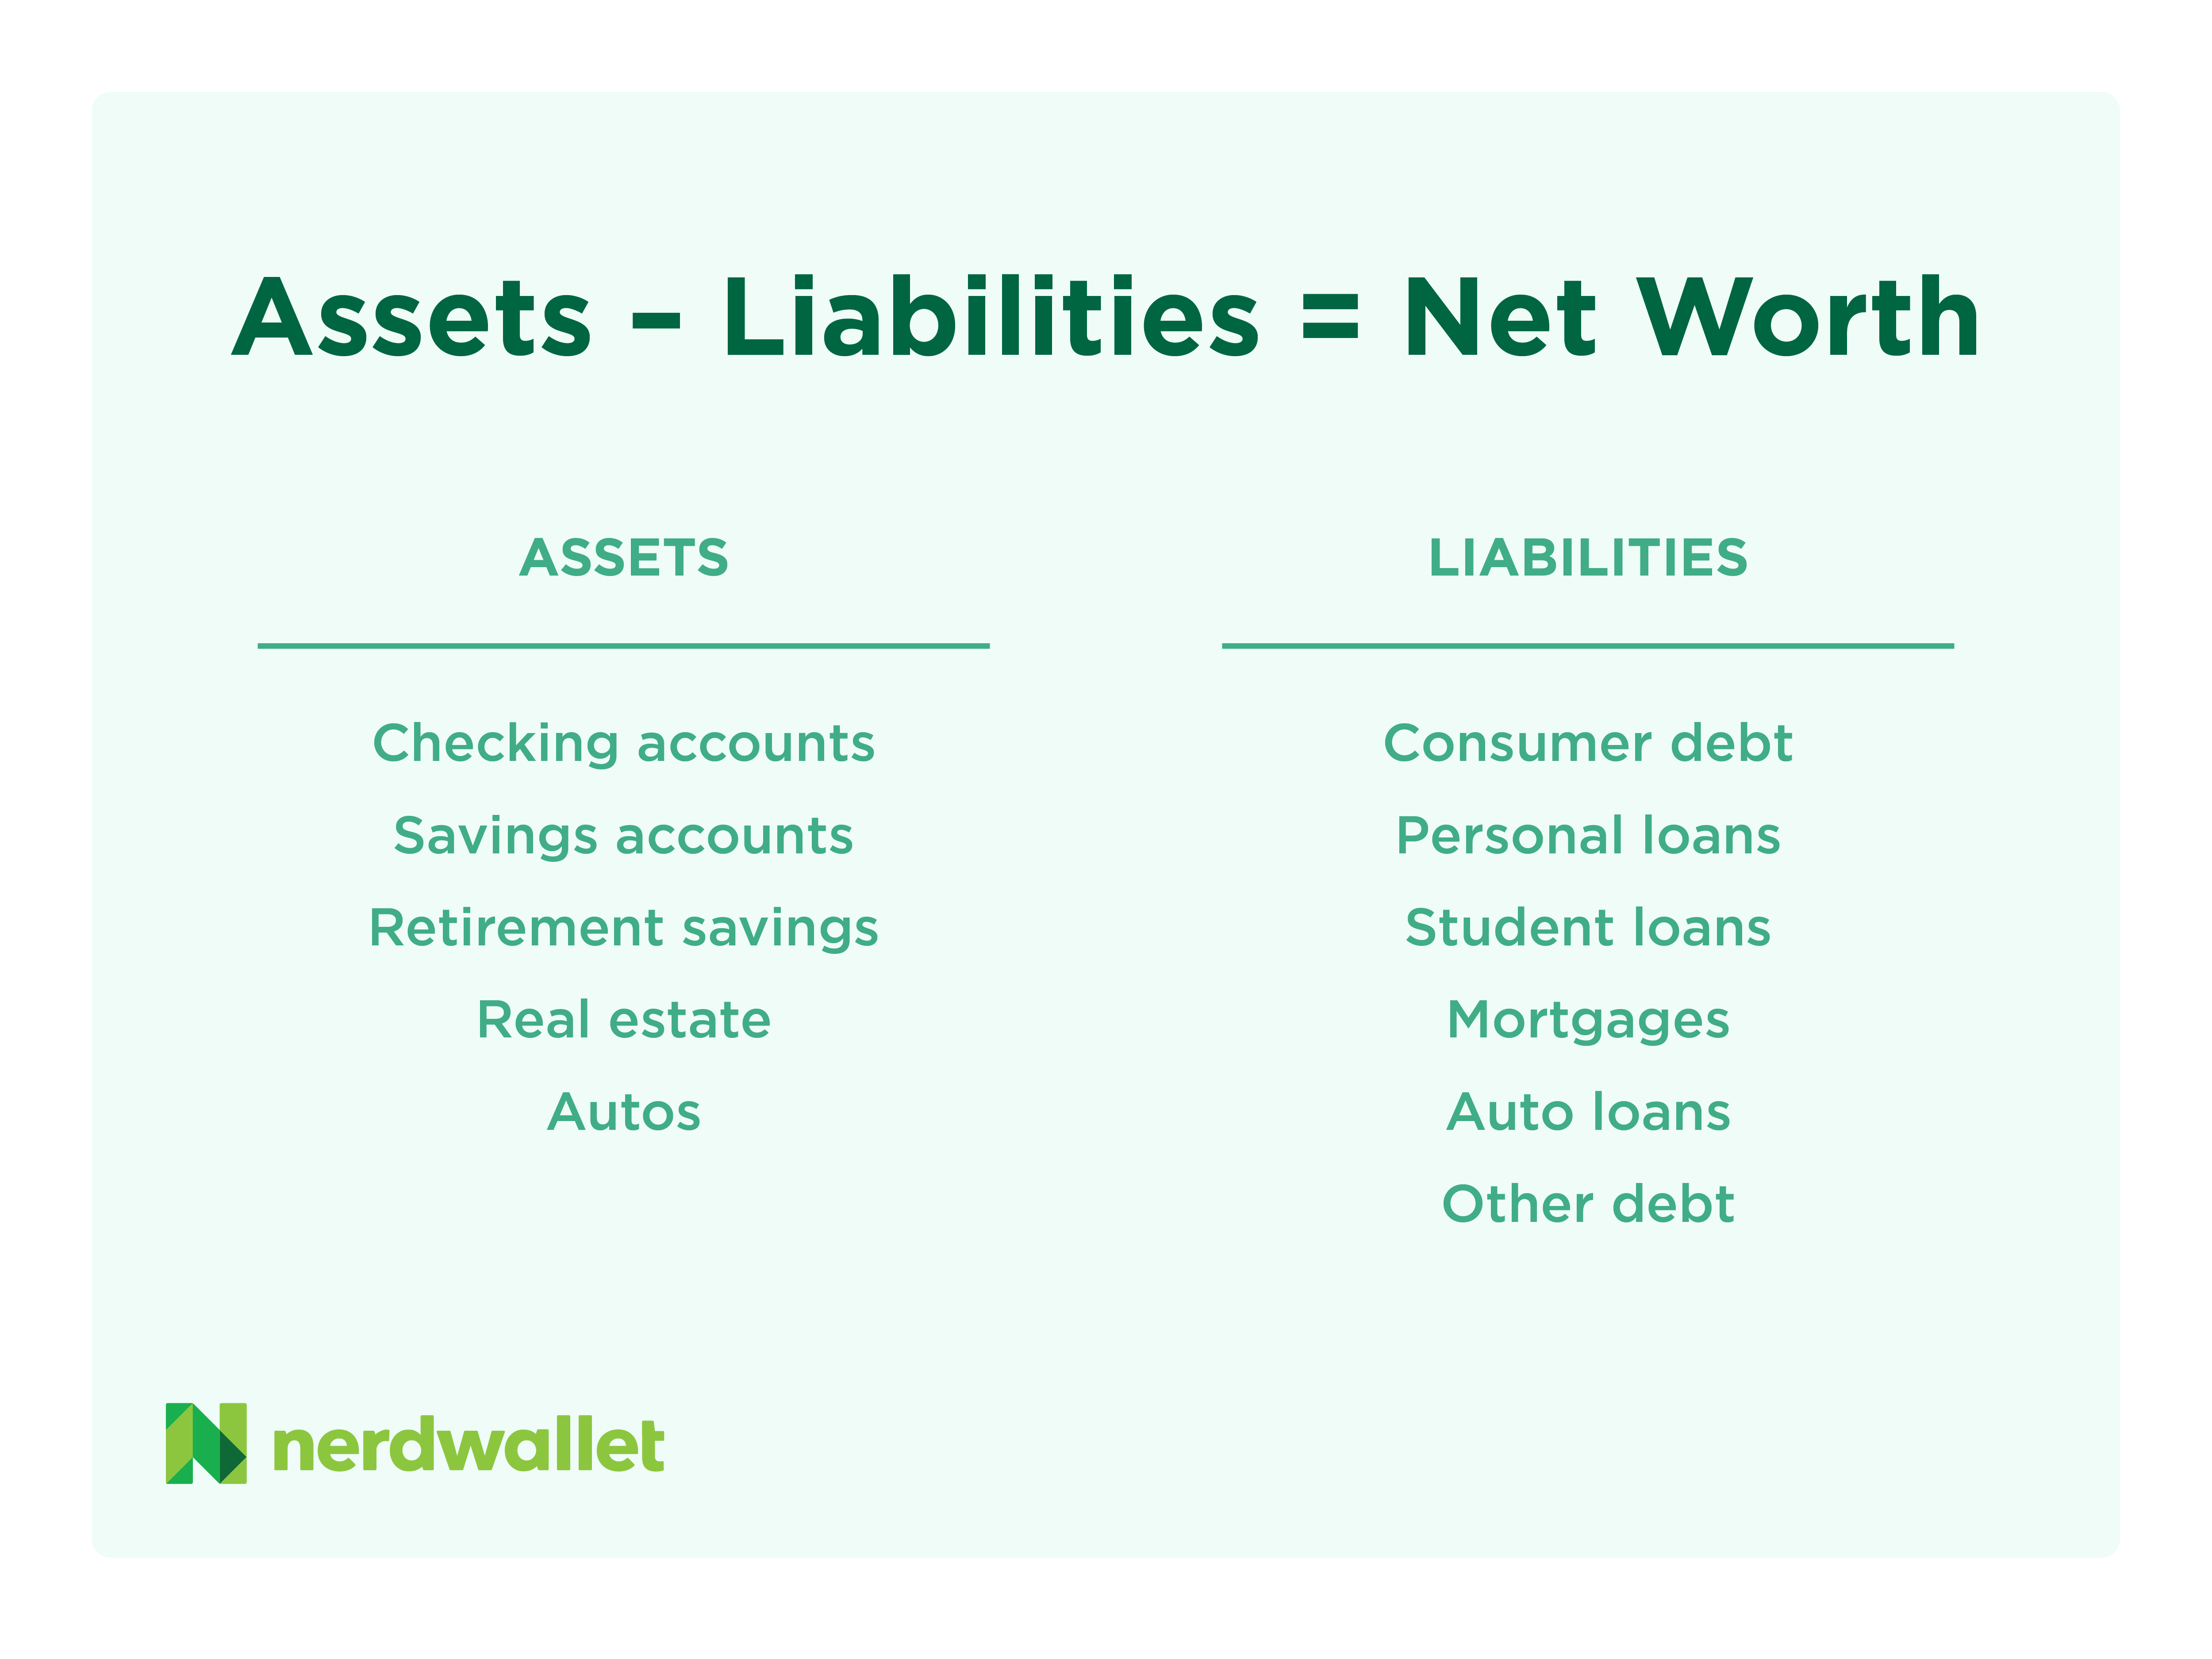 Assets And Liabilities Formula
So when you calculate your net worth, be honest. That Rolex might be worth $10,000 if you sell it, but if you’re never selling it, it’s just a pretty wrist ornament for your liabilities to laugh at.
Liabilities Are the Ninja Assassins of Wealth
Liabilities are sneakier than you think. They’re not just your mortgage or your credit card debt. They’re also that “buy now, pay later” plan on your new laptop, the personal loan from your cousin, and the back taxes you keep pretending don’t exist. They all count.
Here’s the ironic part: debt isn’t always evil. A mortgage on a house that appreciates? That’s “good” liability. But a car loan on a vehicle that loses 20% of its value the second you drive off the lot? That’s a liability doing its ninja thing—quietly draining your net worth while you enjoy the new-car smell.
And here’s my favorite: student loans for a degree you’re not using. Oooof. That’s the ninja with a sense of humor. Don’t worry, we’ve all been there.
Why You Should Care (Even If You’re Broke)
You might be thinking, “Cool story, but I’m 25 and my net worth is negative. Why should I care?” Because tracking your net worth is like checking your weight—it’s the only real way to see if you’re getting fitter or fatter financially.
 What is the business worth? - ppt download
A negative net worth (more debt than assets) is totally normal early on. You’ve got student loans, a starter car loan, maybe a credit card balance. It’s not a moral failing; it’s just data. The goal is to watch that number inch toward zero, then turn positive over time.
Ignore the people posting their “$500,000 net worth at 22” on Instagram. They’re either lying, born rich, or selling you a course. Your journey is yours.
The Fun Part: How to Improve It
Want to boost that number? Two levers: increase assets or decrease liabilities. Easy to say, hard to do. But start with the low-hanging fruit, like paying off that credit card with the 24% interest rate. Doing that is like giving yourself a 24% guaranteed return on your money. No stock market can promise that.
Next, automate a small amount into an asset—even $50 a month into an index fund. It’s boring, it’s slow, but it works. And please, for the love of spreadsheets, stop treating your car like an asset. It’s a liability unless it’s a vintage Ferrari you’re planning to sell. (Spoiler: it’s not.)
 What’s Your True Financial Standing: Calculating Net Worth
Oh, and one side comment: yes, your 401(k) counts. Even if it’s only got $500 in it. That’s $500 more than nothing. You’re doing fine.
The Final (Slightly Awkward) Math
Let’s do a quick example together, shall we? Imagine you have $20,000 in savings (asset), a car worth $15,000 (asset-ish), and a house worth $300,000 (asset). Total assets: $335,000. Now, you owe $250,000 on the mortgage (liability), $10,000 on the car loan, and $5,000 on credit cards. Total liabilities: $265,000.
Net worth: $335,000 – $265,000 = $70,000. Congratulations! You’re worth seventy grand. That’s real. That’s honest. And it’s a number you can work with.
If that number makes you cringe, good. Let it motivate you, not shame you. Net worth is just a snapshot, not your life’s final grade.
So go ahead, grab a napkin, do the math, and ignore the urge to fudge the numbers. Your future self—the one with a positive, growing net worth—will thank you. And hey, if you’re feeling brave, text Sarah and compare notes. Just don’t include the sneakers in the calculation. We both know they don’t count.
