Net Worth Of Investments On Fafsa

So, you’re staring at the FAFSA form, and you see that little box about investments. Your brain might go into a mini panic, right? You’re picturing a Wall Street broker scream...
So, you’re staring at the FAFSA form, and you see that little box about investments. Your brain might go into a mini panic, right? You’re picturing a Wall Street broker screaming at you, but really, you’re just holding a few shares of a company you think is cool. Let’s take a deep breath and untangle this together.
What Even Counts as an “Investment” on FAFSA?
Here’s the thing: the government has a very specific idea of what an investment is, and it’s weirder than you think. They’re not asking about your Pokémon card collection (sadly) or the vintage guitar you found at a garage sale. Nope. They’re looking for things like stocks, bonds, and mutual funds. If you have a brokerage account with even a tiny bit of money, that’s what they want to know about. Why? Because they assume this money is liquid—meaning you could theoretically cash it out tomorrow for tuition.
But wait—it gets a little silly. Your retirement accounts (like a 401k or a Roth IRA) are completely hidden from their prying eyes. Isn’t that wild? You could have fifty thousand bucks in a retirement fund, and FAFSA says, “Nope, didn’t see that.” It’s like wearing an invisibility cloak for your future self.
Must Read
Why Should You Care About Your Net Worth Here?
This is where the math gets interesting. FAFSA doesn’t look at the market value of your investments in a vacuum. It looks at your net worth—which is the value of those investments minus any debt you owe against them. So if you have a margin loan on your brokerage account, you get to subtract that. It’s the only time being a little in debt might actually help you on a government form.
And here’s a fun comparison: imagine your investments are like a bowl of chili at a cook-off. The government takes a big spoonful to see how much meat (money) is in there. If you’re a student with a small investment account, your “chili” is basically broth. But if you’re a parent with a hefty portfolio, that’s a three-alarm chili that could reduce your financial aid. The system is designed to assume that richer families can pay more—obvious, but also a bit of a bummer if you’re just starting to invest.
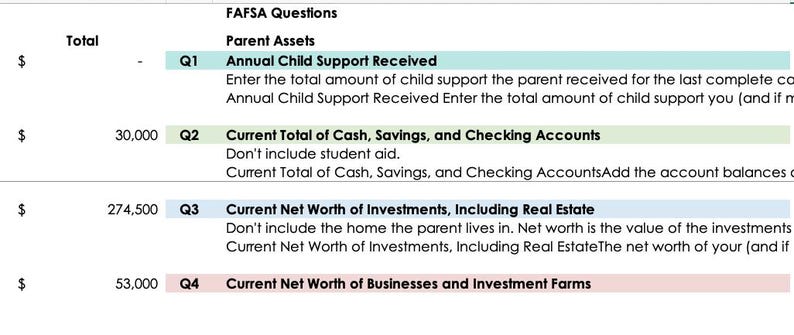
 FAFSA Basics: Parent Assets — How to Pay for College
The Cool Part: Why This Matters for Your Financial Strategy
Here’s the secret sauce: knowing how FAFSA treats investments can make you a smarter saver. Since retirement accounts are ignored, many smart families dump extra cash into a 401k or IRA to protect it. It’s like hiding a snack from your roommate—you still have it, but nobody knows. Meanwhile, that taxable brokerage account you opened to buy a few shares of Apple? FAFSA sees that. It’s like leaving your candy jar in the living room.
But don’t freak out if you have a small account. The impact on your aid is often tiny. Let’s say you’re a dependent student with $5,000 in stocks. FAFSA will assess a percentage of that as part of your assets—usually around 20% for students. That means only about $1,000 gets added to your Expected Family Contribution. That’s not going to wreck your chances. It’s like a drizzle of rain, not a hurricane.
 The Surprising FAFSA/SAI and Roth IRA Conflict that Almost Sabotaged
Rhetorical Questions to Ponder
Are you really going to sell your beloved index funds just to get an extra $200 in Pell Grants? Probably not. And honestly, should you? Investing early is like planting a tree—it takes years to grow, but by sophomore year of college, you might regret cutting it down for a quick buck. FAFSA is asking you to report your net worth, but it’s also a reminder that your future self matters too.
What if you don’t have any investments at all right now? Then you’re in the clear—you get to skip this section entirely. But maybe this is your sign to start a small, boring index fund. Even $50 a month could grow into a nice little tree while you’re studying for finals. Just don’t tell FAFSA about it if you put it in a retirement account.
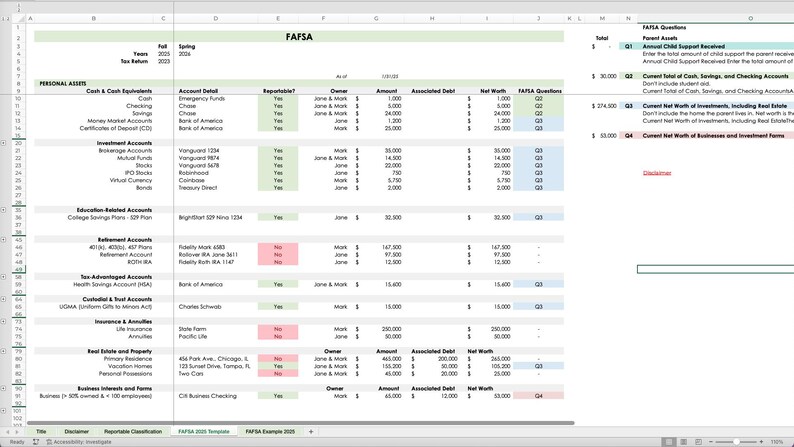 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
The Bottom Line (in a Chill Tone)
Your investment net worth on FAFSA is just a number. It’s not a judgment of your life choices or your parents’ financial acumen. It’s a tool the government uses to guess how much you can chip in for school. If your net worth is low, the system gives you a high-five. If it’s high, it asks you to contribute a little more. It’s not personal—it’s just math with a side of bureaucracy.
So next time you open your brokerage app and see that little green number, remember: you’re doing something cool. You’re building wealth. And even if FAFSA wants a peek, your future self will thank you for having the courage to invest at all. Keep your chill, fill out the form, and go treat yourself to a coffee. You’ve earned it.
