Net Worth Of Top 10 Percent Of Americans

Let’s talk about the top 10%—no, not the Oscars red carpet, but the slice of Americans who hold a staggering share of the nation’s wealth. As of 2024, you need a net worth of...

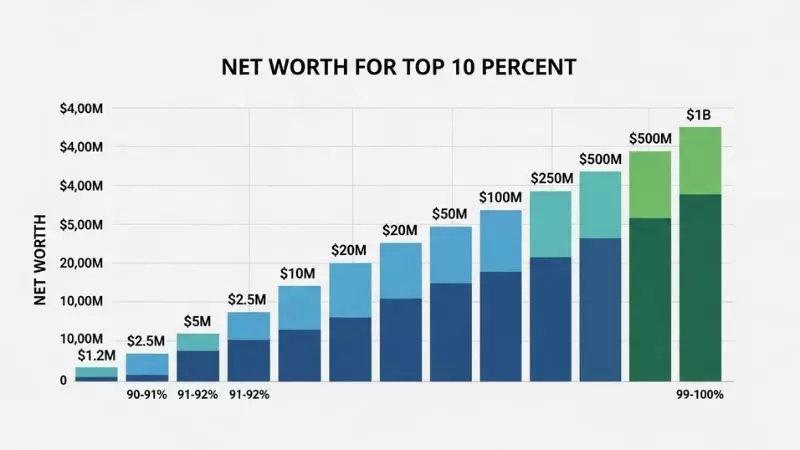
Let’s talk about the top 10%—no, not the Oscars red carpet, but the slice of Americans who hold a staggering share of the nation’s wealth. As of 2024, you need a net worth of roughly $1.9 million to crack this club. That’s up from about $1.2 million a decade ago, thanks to a frothy stock market and sky-high home values.
But here’s the kicker: net worth isn’t just about cash in the bank. It’s assets minus debts, so your 401(k), your house equity, and even that vintage guitar collection count. The top 10% owns about 67% of all household wealth in the U.S., according to Federal Reserve data. Yes, that’s a big slice of the pie—leaving the bottom 50% with a mere 2.6%.
The Line in the Sand
So, how close are you? If you’re a 55-year-old with a paid-off home and a solid retirement account, you might already be in the club without realizing it. Geography plays a huge role: $1.9 million in San Francisco feels like a starter apartment, but in rural Ohio, it’s generational wealth.
Must Read
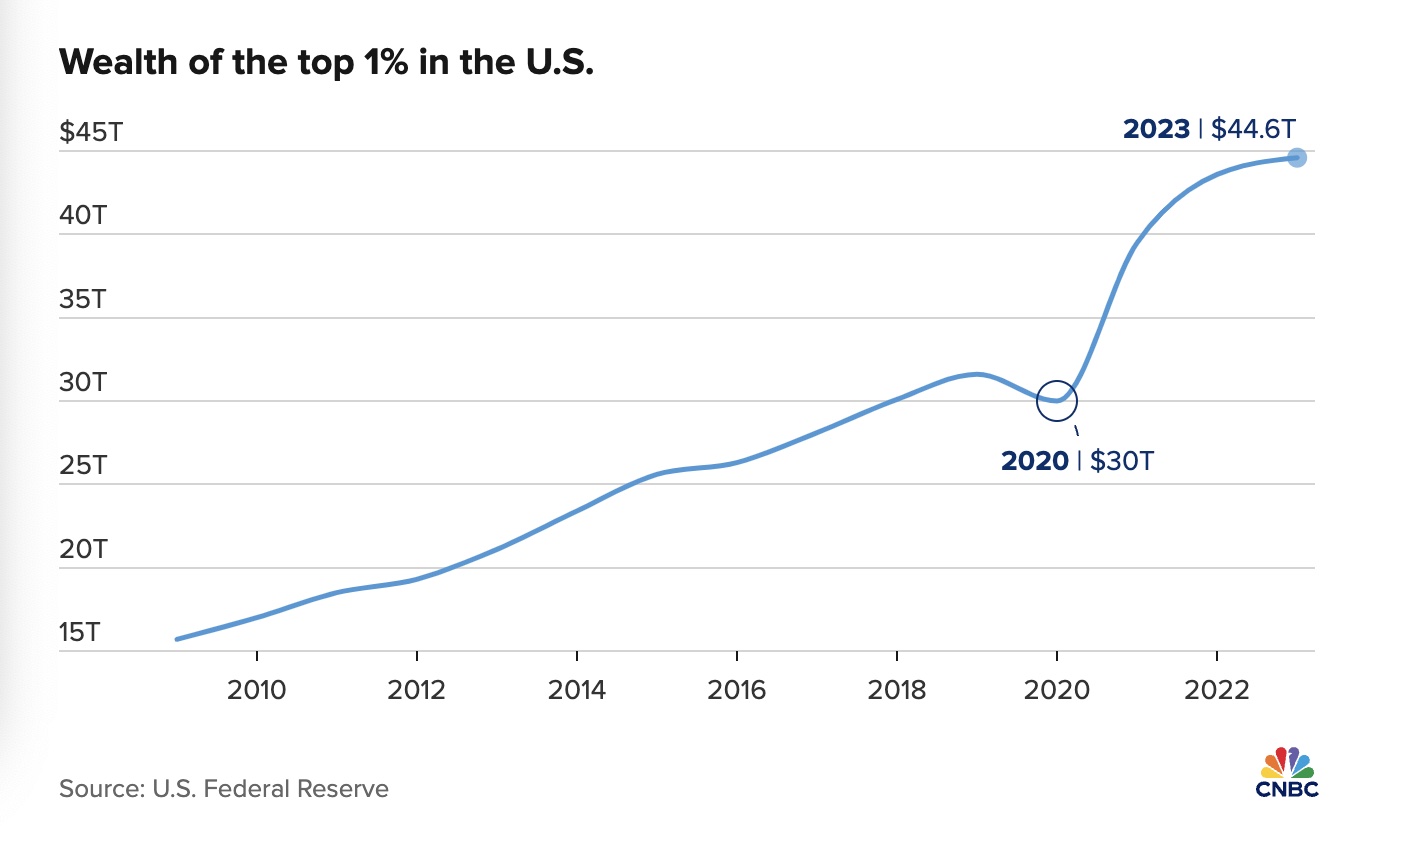
Fun fact: The threshold for the top 1% is $13.7 million—a number that makes the top 10% look almost relatable. Think of it as the difference between flying first class and owning the airline.
The Millionaire Next Door… Is a Myth?
We love the trope of the frugal millionaire who drives a 1998 Honda Civic and clips coupons. Sure, that exists, but the modern top 10% is often dual-income, tech-heavy, and leveraged. They’ve bought homes at 3% mortgages and maxed out their 401(k)s during the COVID dip.
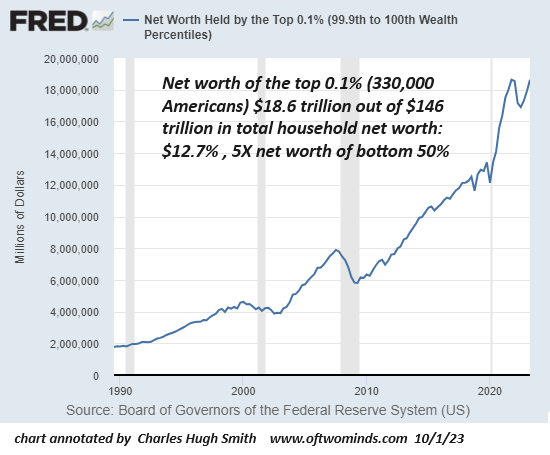
A cultural reference: Remember The Wolf of Wall Street? That’s the top 0.1%, not the top 10. Most of this group are boring—dentists, senior engineers, small business owners who reinvest profits. They’re not buying yachts; they’re paying for private school and a vacation home in the Smokies.
 Of Two Minds - Fix This or Nothing Else Matters
Practical Tip #1: Check Your "Hidden Wealth"
Net worth isn’t just your salary. Let’s play a quick game: Add up your home equity, retirement accounts, savings, and even that rare Beanie Baby collection from the ‘90s (kidding, mostly). Subtract student loans and credit card debt. You might be closer to $1 million than you think.
According to a 2023 study by Kiplinger, the median net worth for a 65-year-old in the top 10% is $3.2 million. That sounds huge, but it includes illiquid assets like real estate. The real power is cash flow from dividends, rental income, or a pension.
The Lifestyle Trade-Offs
Here’s the secret no one tells you: Being in the top 10% doesn’t mean you feel rich. You’re still stressed about property taxes, college tuition, and whether your neighbor’s new Tesla is a flex or a lease. It’s a class of people who have options—but not infinite ones.
Fun fact: The top 10% saves about 25% of their income, while the average American saves around 5%. That compounding gap is why they stay in the club. It’s less about earning more and more about keeping more.
 Net Worth for Top 10 Percent: Income, Assets & Wealth
Practical Tip #2: The "Three-Bucket" Strategy
Want to join the 10% club? Think of wealth in three buckets: Liquid (cash for emergencies), Growth (stocks, real estate), and Safe (bonds, I-bonds). The top 10% often has a 70/30 split between growth and safe assets. You don’t need to be a Wall Street whiz—just consistent.
A cultural nod: The Great Gatsby’s Tom Buchanan would be a top 0.1% guy, but the top 10% is more like Jay Gatsby before the parties—working hard, building quietly, rarely spending on status symbols. In 2024, that patience is your superpower.
The Quiet Magic of Index Funds
Surprisingly, the top 10% aren’t stock-picking geniuses. Most use low-cost index funds that track the S&P 500. Over 30 years, that approach turns $10,000 a year into over $1.5 million, assuming 7% returns. It’s boring, but it works.
Fun fact: The average net worth of a 45-year-old in the top 10% is $1.2 million—mostly in retirement accounts. That means they’re not sitting on piles of cash; they’re letting time do the heavy lifting.
 Joe Biden's America: Wealthiest 1% Set Record with $44 Trillion Total
Practical Tip #3: Own Your Home (Strategically)
Home equity is the single biggest driver of net worth for the top 10%, especially outside coastal cities. If you’re renting, consider a starter home in a growing suburb—even a fixer-upper. The mortgage interest tax deduction is a classic wealth-builder. Just don’t overbuy; a house is a home, not a casino.
Remember Friends? Monica’s rent-controlled apartment was a fantasy. In real life, owning a small condo and paying it off by 60 is a solid ticket to the 10% club.
Reflection: The Real Wealth Check
And yet, here’s the thing: Net worth is a number, not a measure of joy. The top 10% often report more stress about money, not less, because they’re managing taxes, inflation, and estate planning. Studies show that happiness peaks at an income of about $75,000 a year—after that, it flatlines.
So, while the $1.9 million threshold sounds glamorous, the real wealth is control over your time. The ability to say “no” to a bad job, to take a Tuesday afternoon hike, or to help a friend in need—that’s the dividend that matters. Whether you’re in the top 10% or saving your first $10,000, that feeling is priceless. And you can start building it today, one index fund at a time.
