Net Worth Statement Liabilities Home Mortgage Balance

Let’s be honest: a “net worth statement” sounds like something you’d only see in a boardroom full of people wearing suspenders and talking about synergies. But really, it’s ju...
Let’s be honest: a “net worth statement” sounds like something you’d only see in a boardroom full of people wearing suspenders and talking about synergies. But really, it’s just a fancy report card for your money. On one side, you have your assets—the stuff you own that could be sold for cash. On the other side, you have your liabilities—the debts you owe to other people, like that friend who spotted you for pizza in 2019.
The whole goal is to see if your assets are bigger than your liabilities. If they are, you’re winning. If they aren’t, you’re technically in the red, but hey, we’ve all been there after a holiday shopping spree. It’s like checking your bank account after a really good weekend: you know the answer might sting, but you have to look anyway.
Now, let’s talk about the biggest, scariest, and most common liability for most regular folks: the Home Mortgage Balance. That’s the remaining amount you still owe on the roof over your head. It’s the financial equivalent of that one really heavy friend who always wants to sit on your lap.
Must Read
You love your house. It’s where you hide from the world, store your snacks, and argue about the thermostat. But that mortgage balance? It’s the little gremlin that reminds you every month that you don’t actually own the front door yet—the bank just lets you borrow it.
Picture this: You buy a house for $300,000. You put down $30,000 in cash that you probably saved by eating ramen for three years. Now you have a mortgage balance of $270,000. That is a liability. It sits on the right side of your net worth statement, staring at your assets like a jealous sibling.
Here’s the funny part: Your house is also an asset on the other side of the statement. So you’re counting it twice, in a way. It’s like when you lend yourself $20 from your left pocket using your right hand. The net worth statement doesn’t care about your feelings; it just wants the math.
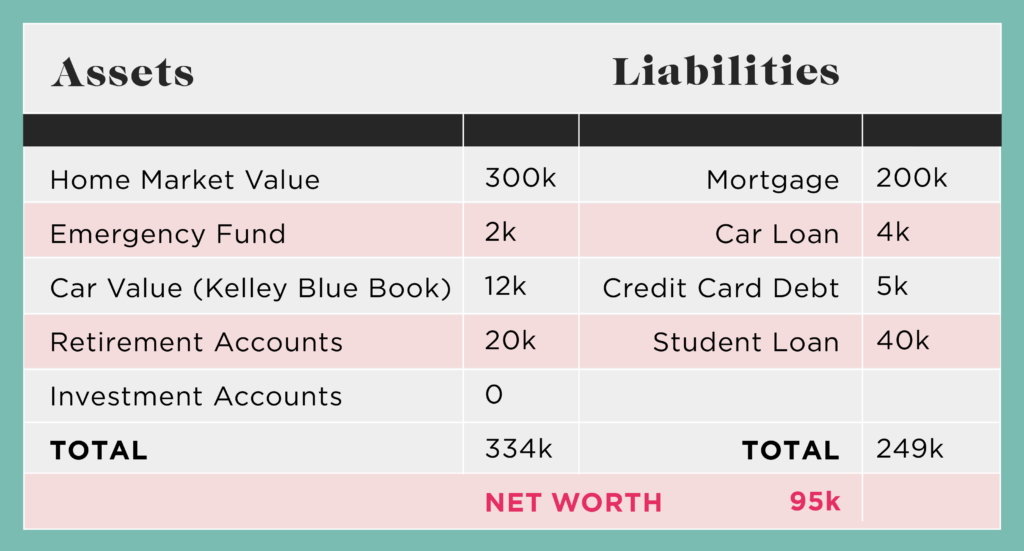 How To Calculate Net Worth
If your house is worth $320,000 today, but you still owe $270,000 on the mortgage, your net equity is only $50,000. That $50,000 is the part you actually own. The rest is just a promise you made to a bank with a very serious interest rate.
Think of your mortgage balance as a slowly deflating balloon. Every month, you make a payment, and a tiny bit of air (your debt) hisses out. But for the first several years, most of that payment goes to interest, not the balance. You’re basically paying rent to the bank for the privilege of living in your own house.
I remember looking at my first mortgage statement and feeling proud. Then I saw that out of a $1,500 payment, only $200 went to the principal. The rest went to interest, taxes, and insurance. It felt like buying a fancy coffee and realizing the cup costs more than the actual drink inside.
 Net Worth 101: What is Net Worth and How to Calculate it - Savology
So why do we do this to ourselves? Because owning a home is the closest most of us will ever get to feeling like a feudal lord. And because, eventually, that mortgage balance hits zero. That day is like graduating from college, except you actually know what you did for the last 30 years.
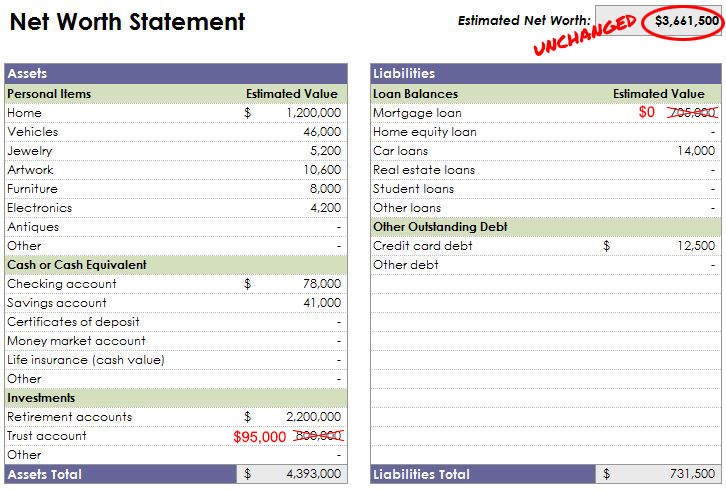
When you finally pay off the mortgage, that liability disappears from your net worth statement permanently. Poof. Gone. Your net worth suddenly jumps by $270,000 on paper, even though you didn’t find a treasure chest in your backyard. You just finished paying for the treasure chest you were already sitting on.
But be warned: the moment you pay off the mortgage, a new liability might appear. My neighbor paid off his house, and the very next week, his water heater exploded. That’s life sticking its hand in your pocket again.
 Net Worth Calculator, Balance Sheet, Assets and Liabilities Excel
So, when you look at your net worth statement, don’t panic at the big number under “Liabilities — Home Mortgage Balance.” That number is just a receipt for the biggest, most beautiful mistake you’ll ever make. It’s the price of having a place to hang your ugly holiday sweater collection.
Treat your mortgage balance like a grumpy old dog. You have to feed it every month, it’s expensive to maintain, and it takes decades to fully own. But when you finally get that mortgage-free celebration, it’s the best dang feeling in the world. Just be ready for the water heater to break.
And if your net worth is currently negative because of that mortgage? Don’t sweat it. That just means you have a lot of future equity you haven’t unlocked yet. Or, as I like to call it, you’re just pre-wealthy.
