Retirement Planning For High Net Worth Individuals

Let’s be real: retirement planning for high net worth individuals isn’t about clipping coupons or downsizing to a bungalow. It’s more like curating a bespoke lifestyle that ou...

Let’s be real: retirement planning for high net worth individuals isn’t about clipping coupons or downsizing to a bungalow. It’s more like curating a bespoke lifestyle that outlasts your career, while keeping the taxman at arm’s length. Think of it as the financial equivalent of a tailored Italian suit—sleek, expensive, and requiring a master tailor to get it right.
The New Rules of the Game
Forget the 4% rule. When your portfolio starts with a seven-figure sum, your biggest risk isn’t running out of money—it’s losing your purpose or watching inflation eat your legacy. The ultra-wealthy now plan for volatility, not just returns, because a 20% market drop hits differently when your “safety net” is a hedge fund.
Fun fact: Nearly 70% of high net worth families lose their wealth by the second generation. It’s not bad luck; it’s poor planning. So, your strategy needs to be as robust as a Swiss vault—and just as discreet.
Must Read
Asset Location Over Asset Allocation
You already know to diversify. But the real magic for the wealthy? Asset location—putting the right investments in the right tax wrappers. Put your high-growth stocks in a Roth IRA (tax-free forever) and your boring bonds in a taxable account.
Imagine you’re curating a playlist: you don’t put death metal next to lullabies. Similarly, don’t let taxes ruin your rhythm. A family office or a specialized CPA can choreograph this dance for you—because, yes, you can afford one.
The Lifestyle Empire
Retirement for the wealthy isn’t a finish line; it’s a pivot. You’re likely moving from accumulating wealth to managing a life that includes second homes, private travel, and maybe a vineyard. Your plan should budget for a Porsche 911 Turbo S and a charitable foundation—they’re both liabilities, but one gives you street cred.
 High-Net-Worth Retirement Planning: 6 Ideas to Help You Get Your
Fun little fact: The average high net worth retiree spends more on wine than on healthcare. Budget accordingly, and maybe hire a sommelier as a consultant. It’s not frivolous; it’s quality-of-life optimization.
The Invisible Tax Shield
Estate taxes are the monster under your yacht. Without a trust, the government can take up to 40% of what you leave behind. That’s like throwing a tax party and not inviting your heirs.
Enter the Grantor Retained Annuity Trust (GRAT) and the Charitable Lead Trust. These aren’t just acronyms; they’re legal loopholes that let you pass millions to your kids tax-free while funding your favorite museum. Think of it as a financial magic trick—done with a straight face and a good lawyer.
The Psychological Portfolio
Here’s the part money managers don’t teach: boredom. If you’ve spent decades building a business, retirement can feel like a slow death. The solution? Structure your days with “capital projects”—like starting a think tank, buying a winery, or mentoring startup founders.
 25 Smart Retirement Planning Questions for High-Net-Worth Individuals
One billionaire I read about bought a lighthouse. Not for the view—to have a project that required daily focus. Your retirement plan should include a “joy bucket” for hobbies that cost as much as a small country’s GDP. Skydiving school? Go for it. Just wrap it in an LLC for liability.
Health as an Asset Class
Your body is your most expensive asset. High net worth retirement means access to concierge medicine, genetic testing, and a personal chef who hates carbs. Treat your health like a luxury real estate investment: maintain it, upgrade it, and don’t let it depreciate.
Ever heard of the “Blue Zones”? The world’s longest-living people spend on relationships, not yachts. So, buy a ticket to Sardinia, but also hire a life coach to ensure you actually enjoy the trip. True wealth is time + health + meaningful work.
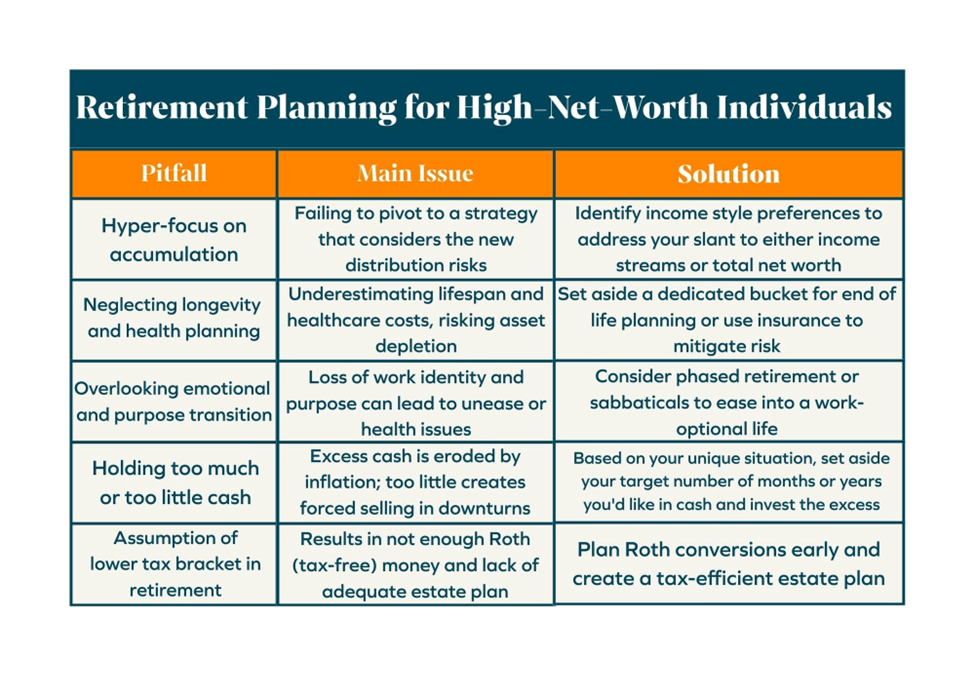 How Much Is Enough? Retirement Planning for High-Net-Worth Families
Practical Tips That Scale
- Buy a vacation home in cash. Leverage is for startups. A paid-off retreat gives you a strategic Redoubt if markets go south.
- Gift early. Use the annual gift tax exclusion ($18,000 per person in 2024) to move money to kids or grandkids. It’s like financial acupuncture—small moves now prevent big pains later.
- Think like a museum. Collect art, wine, or classic cars as a passion, but consult an art advisory to avoid fake Picassos. Storage and insurance are often tax-deductible if the collection is on display.
The Legacy of Choice
Finally, remember that control is the ultimate luxury. You can live in Monaco, sail the Galapagos, or fund a university chair. But none of it matters if you’re micromanaging your portfolio from a beach chair. Delegate to a family office, set a spending rule (like 3% of net worth), and then actually retire.
One last fun fact: Studies show that the happiest wealthy retirees give away their money while alive. They see the impact, which is more satisfying than a marble headstone. Your gift doesn’t need to be the Louvre—a scholarship in your name at your alma mater works just fine.
Reflection for the Morning Coffee
When you’re sipping your $12 pour-over from single-origin beans, ask yourself: What does $10 million a year feel like? For most, it’s not a yacht—it’s the freedom to say “no” to things that drain you. Your retirement plan is a permission slip to live intentionally.
So, trade the spreadsheet for a sunset, the board meetings for a bike ride. The numbers will work themselves out if you’ve built the right team. In the end, wealth isn’t a number—it’s the quiet confidence that your days are yours to design.
