Sec Net Worth Assets Liabilities Definition

So, picture this: my buddy Mark, a guy who can name every ‘90s hip-hop album but not a single stock ticker, texts me a photo of a crumpled receipt. It’s from a fancy sushi pla...

So, picture this: my buddy Mark, a guy who can name every ‘90s hip-hop album but not a single stock ticker, texts me a photo of a crumpled receipt. It’s from a fancy sushi place, and the total is $340. “Net worth update,” he captions it, with a skull emoji.
He’s joking, but he’s not wrong about the vibe. We all have this fuzzy notion that our financial life is a single number—a “net worth”—that’s either crushing it or begging for mercy. Net worth is just the math problem your bank account wishes it could solve in its sleep.
At its core, net worth is brutally simple: Assets minus Liabilities. If you think that sounds like a boring textbook sentence, stick with me. It’s actually the plot of your personal finance movie.
Must Read
What on Earth Are Assets?
Assets are anything you own that puts money in your pocket (or could, if you sold it). Your checking account? Asset. That vintage guitar you swore you’d learn to play? Asset. The 2013 Honda Civic that gets you to work? Yes, asset.
But here’s the trap: not all assets are equal. A wad of cash under your mattress is an asset, but it’s a lazy one—it’s losing value to inflation as you read this. A rental property that throws off cash every month is a productive asset.
I like to call the good ones “silent money-makers.” They work the night shift so you don’t have to. Your collection of Beanie Babies from 1999? That’s a “nostalgia asset,” and unless you’re selling to a very specific museum, it’s probably not funding your retirement.
Liabilities: The Party Crashers
Now, liabilities are the opposite—they’re the things you owe. They are the financial vampires that siphon cash out of your wallet every month. Student loans? Liability. Credit card balance from that sushi dinner? Liability. Your mortgage? Yes, a liability (even though it’s a “good” one).
 Assets And Liabilities Formula
I know, I know—your house is also an asset because it has value. But until you sell it, that mortgage is a monthly liability that’s very real, very hungry, and very unimpressed by your Netflix password. The bank doesn’t care about your living room decor; they just want their payment.
The sneaky part? Some liabilities pretend to be assets. A shiny new car on a 72-month loan? That’s a liability wearing a fancy hat. It loses value the second you drive it off the lot, while you’re still paying interest on it. Ouch.
The Net Worth Formula: A Brutally Honest Equation
Here’s the magic: Net Worth = Total Assets – Total Liabilities. If your assets are $50,000 (car, savings, that dusty guitar) and your liabilities are $30,000 (student loans, credit card), your net worth is $20,000. Congrats, you’re positive!
But if your student loans are $100,000 and your only asset is a used laptop? You’re looking at a negative net worth. And guess what? That’s totally normal if you’re early in your career or fresh out of school. Plenty of millionaires started with a negative net worth—it’s just a starting line, not a tombstone.
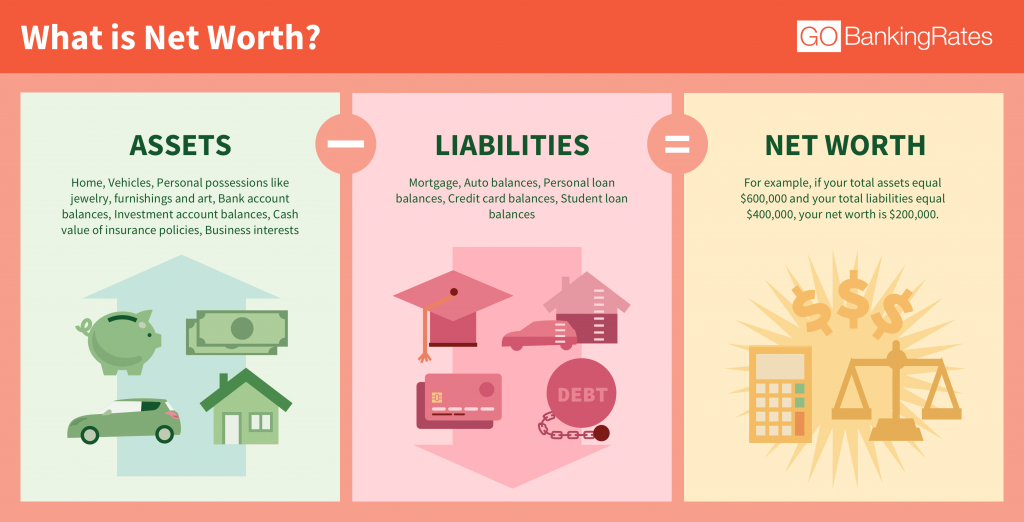 Net Worth: What Is It and How Do You Calculate It? | GOBankingRates
The real eye-opener? Most people overestimate their assets and underestimate their liabilities. We love to count the equity in our home but “forget” the loan balance. Be ruthlessly honest with yourself here. The math doesn’t care about your feelings, but it will set you free.
A Little Story to Tie It Together
Remember Mark? A year after that sushi text, he called me panicked. He was “broke” but driving a leased BMW. His assets: a wage-slave salary and a security deposit. His liabilities: the car lease, credit card debt, and a couch he bought with “buy now, pay later.” His net worth? Negative $12,000.
We sat down and played the math game. He sold the BMW (bye-bye, status symbol), paid off the credit card with the proceeds, and started driving his grandma’s old Corolla. Six months later, his net worth hit zero. Not negative. Zero. And he cried—happy tears.
That’s the power of knowing these two words. Assets are your allies. Liabilities are your leaks. And your net worth is just the report card that tells you who’s winning the tug-of-war.
 Net Worth – Here’s Everything You Need To Know - How to Money
Why You Should Track This Nerd Stuff
I’m not saying you need to obsessively update a spreadsheet every morning (though if you do, no judgment—you absolute legend). But checking your net worth once a month is like stepping on a scale for your wallet. It gives you direction.
Your goal isn’t a perfect number; it’s an upward trend. Even a $50 increase means you’re outrunning your liabilities. Compare that to the person who “feels rich” because they just got a huge credit limit increase—that’s not wealth, that’s a longer leash before the trap snaps.
So go ahead, add up your stuff, subtract what you owe, and face the number. If it’s ugly, laugh at it. If it’s pretty, know you’ve built something real. Either way, you’re not your net worth—you’re just the person who decides what to do with it.
Now go sell something you don’t use and pay off a tiny debt. Seriously. Right now. I’ll wait.
