Ultra High Net Worth Asset Allocation

You know how you plan a family dinner, making sure there’s enough pizza for everyone, a salad for the health-conscious aunt, and that one weird dessert your uncle loves? That’...
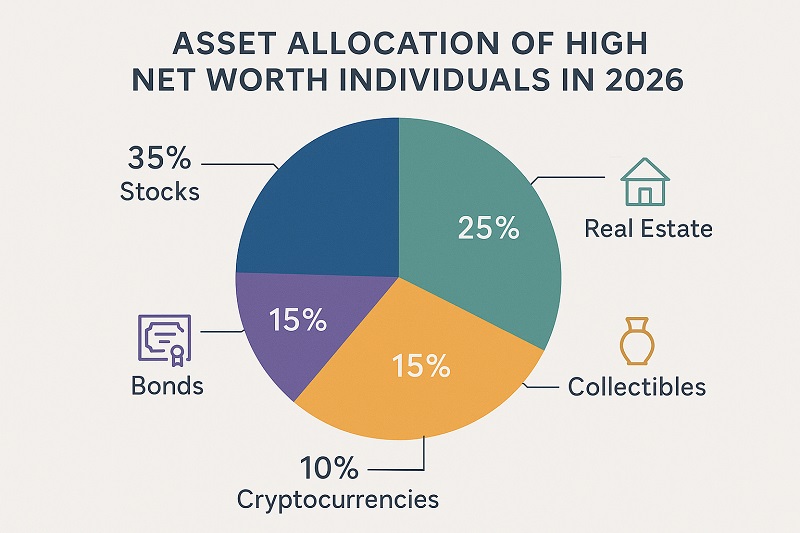
You know how you plan a family dinner, making sure there’s enough pizza for everyone, a salad for the health-conscious aunt, and that one weird dessert your uncle loves? That’s basically what Ultra High Net Worth Asset Allocation is—but for people with, say, a few million dollars in their fridge budget instead of leftover pepperoni.
You don’t need to be a billionaire to care about this. Whether you’re saving for a down payment or just hoping your retirement fund doesn’t turn into a meme coin, the same principles apply. It’s about not putting all your eggs—or your gold-plated ostrich eggs—in one basket.
What’s the Big Deal?
Imagine you’re at a buffet. You load up on mashed potatoes, but the gravy boat tips over. No biggie, right? But for ultra-wealthy folks, a single investment tipping over can mean losing a yacht or, worse, the yacht’s crew. Their allocation is like a safety net woven from cash, stocks, real estate, and even art or private jets.
Must Read
Why should you care? Because you do the same thing when you split your paycheck between rent, savings, and that emergency taco fund. Their version just has more zeros and a slightly fancier spreadsheet.
The "Pizza Party" Strategy
Let’s call this the Ultra High Net Worth Pizza. You’ve got your cheese slice (cash and bonds)—safe, boring, but reliable. Then the pepperoni (public stocks) for growth that gets spicy. Add a slice of Hawaiian (private equity) for that sweet, sweet potential—though some people hate pineapple on pizza, just like some hate private investments.
Now, the crust? That’s alternative assets: vineyards, rare watches, or a Picasso. It’s the weird corner you nibble on when you’re feeling fancy. Most of us buy a $50 bottle of wine; they buy the vineyard. But the lesson is the same: diversity makes the meal better.
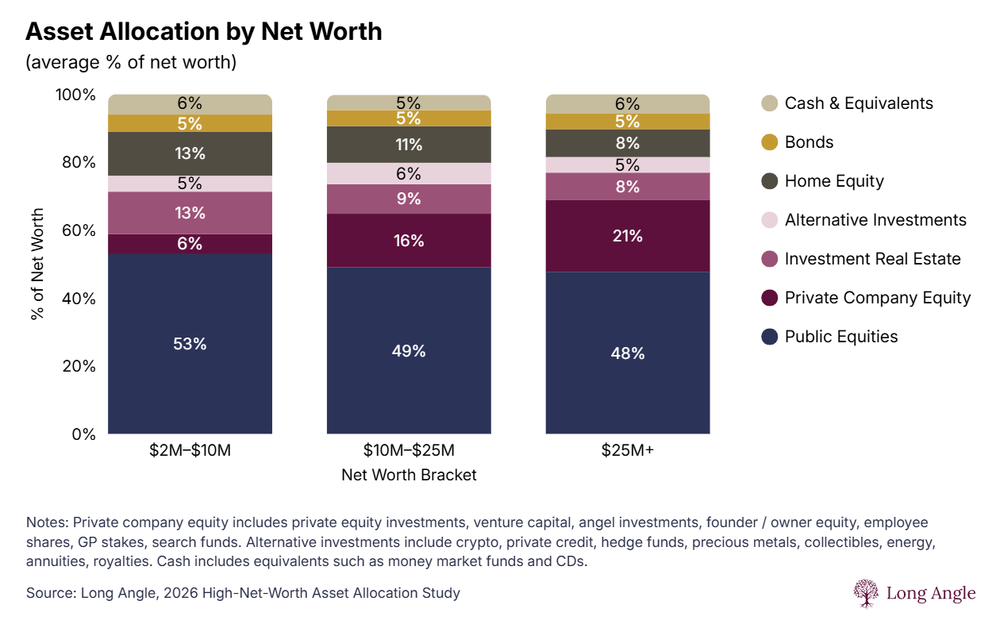 High-Net-Worth Asset Allocation Study - Long Angle
One of my neighbors, a retired teacher, once told me she owns stock in a soft-drink company, a little government bond, and a tiny rental property. She laughed and said, “It’s my billionaire-lite portfolio.” She wasn’t wrong. Her allocation mirrors what the really rich do—just without the private island.
Why Bother With Stories About the 1%?
Because the 1% aren’t just hoarding gold coins like Scrooge McDuck. They’re managing risk so their wealth lasts generations. And you, yes you, can steal their playbook. When an ultra-rich person puts 5% into art, they’re not just being artsy—they’re hedging against the stock market crashing. When you put 5% into a high-yield savings account, you’re doing the exact same thing with a smaller canvas.
Think about it: if you lose your job, your emergency fund is your “cash slice.” If the market tanks, your index funds are your “boring but safe cheese slice.” Their allocation is just your allocation on steroids, with a side of non-fungible tokens that cost more than your car.
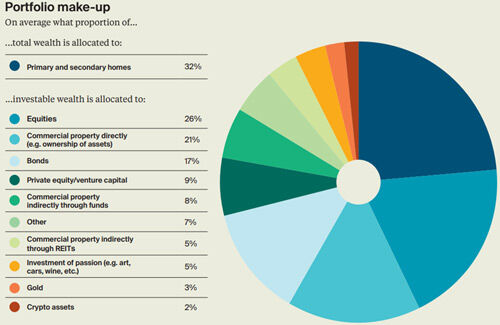 The Wealth Habits of Ultra High Net Worth Individuals Revealed
How to Sound Like a Pro at a Dinner Party
Next time someone mentions “asset allocation,” just nod and say, “Ah yes, the core-satellite approach.” It means you have a solid base—low-cost index funds—and a few cool “satellites” like a rental cabin or some crypto. The ultra-wealthy do this but their satellites are, oh, a jet fleet or a stake in a tech startup.
The real magic? Rebalancing. Every year, the rich sell a little of what’s done well (like stocks) and buy more of what’s lagging (like bonds). It’s like trimming the hedges so your garden doesn’t get lopsided. You can do this too: if your savings account is overflowing, shift some into investments. Boom, you’re rebalancing like a hedge fund manager.
I once read that a wealthy investor kept 10% in cash just so they could “buy the dip” during a panic. That’s not greed—it’s patience with a plan. The rest of us can keep a mini cash stash for sales on electronics or unexpected car repairs. Same vibe.
 High-Net-Worth Asset Allocation Study - Long Angle
A Little Laugh at the Luxury
Let’s be real: some ultra-high-net-worth allocations are hilariously extra. One billionaire had a dedicated “art fund” that included a banana duct-taped to a wall. That’s not a joke—it actually happened. But behind the absurdity, the logic is sound: that banana investment probably wasn’t correlated with the stock market, so when stocks fell, the banana (hopefully) didn’t rot.
You don’t need a banana on your wall. But you do need to ask: does your money have different jobs? Some for safety, some for growth, some for fun? If your answer is “only one job—panic,” then it’s time to spread the love.
The Takeaway That Fits Your Wallet
Ultra High Net Worth Asset Allocation sounds like a secret club for people with private islands. But it’s really just grown-up snack planning. They’re making sure they don’t trip over the gravy boat, and you can too—with a smaller boat and less gravy.
Start small. Sip coffee—yours, not theirs—and mentally split your savings into three jars: stay safe, grow a little, and treat yourself. The rest is just zeros. And honestly, your coffee is probably just as warm as theirs.
