Ultra High Net Worth Financial Advisor

Imagine you’re at a private villa in Tuscany, discussing vintage Bordeaux while someone casually mentions diversifying into a private jet fractional ownership fund. This isn’t...

Imagine you’re at a private villa in Tuscany, discussing vintage Bordeaux while someone casually mentions diversifying into a private jet fractional ownership fund. This isn’t a movie scene; it’s a Tuesday for an Ultra High Net Worth (UHNW) Financial Advisor. These are the financial whisperers for the 0.1%—people with assets north of $30 million.
We’re not talking about your friendly neighborhood stockbroker. The UHNW advisor lives in a world of bespoke family offices, generational wealth transfers, and the occasional panic over a $50 million art collection’s insurance premium. Their job isn’t just about returns; it’s about preserving a lifestyle most of us can’t even dream of.
The Art of the “No”
A great UHNW advisor spends half their time saying “no.” Clients might want to buy a vineyard in Napa on a whim or throw millions into a cousin’s “revolutionary” app. The advisor’s role is to be the calm, data-driven reality check in a world of endless yes-men.
Must Read
Think of it like the Succession scene where Kendall Roy pitches a wild idea, and the CFO just stares. The best advisors have that stare perfected. They understand that ego is the biggest risk in the portfolio.
Practical Tip #1: The Two-Week Rule for Big Money
You don’t need a private island to use this trick. When tempted by a major purchase—say, a new car or a renovation—wait two full weeks. UHNW advisors apply this to yacht purchases. Impulse buys have sunk more wealth than bad stocks ever did.
More Than Mutual Funds: The Toolbox
The UHNW toolkit is a wonderland of exotic assets. We’re talking direct private equity, timberland, litigation finance, and even shares of Broadway shows. A typical portfolio might include a stake in a Formula 1 team next to a bond ladder yielding 4%.
One fun fact: Many advisors now allocate up to 10% to “passion assets” like vintage Ferraris or rare whiskey casks. These items often appreciate faster than the S&P 500, and they look great in the garage. It’s finance as a lifestyle flex.
 Understanding the Differences: Ultra High Net Worth Advisors vs High
Cultural Reference: The Old Money vs. New Money Split
In The Great Gatsby, Gatsby throws parties to get noticed. The old money Buchanans sit quietly on their porch. UHNW advisors know this tension well. New-money clients buy the Gulfstream jet; old-money families lease it and call it a “logistics expense.” The advisor’s job is to bridge those mindsets without judgment.
They also know that privacy is the ultimate luxury. You won’t see these clients on social media bragging about their advisor. The best relationships are invisible.
The Family Office is the New Castle
Most UHNW families have a single-family office—a private company that handles everything from paying the staff’s salaries to managing charitable foundations. It’s like having a Fortune 500 CFO for your personal life. The advisor often acts as the CEO of this mini-empire.
A fascinating twist: Next-gen clients (the “kids”) are pushing for impact investing. They want their money to fight climate change and return 8%. The advisor’s skill is finding a solar energy startup that actually makes money, not just good PR.
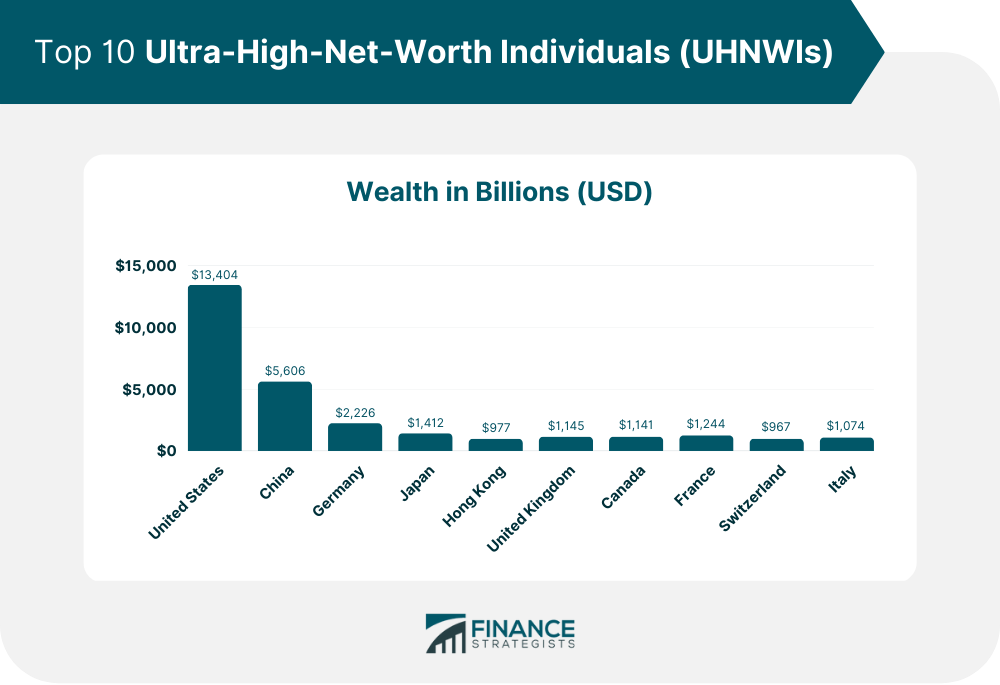 Ultra-High-Net-Worth Individual (UHNWI) | Definition & Statistics
Practical Tip #2: The “Enough” Check
UHNW advisors ask a terrifying question: “What is enough?” You can apply this today. List your top three financial goals. If you hit them, would you stop trading, stop chasing promotions? Most people never ask, and that’s why they keep working when they don’t have to. Define your finish line.
The Party Fouls of High Finance
Even the rich make rookie mistakes. The biggest? Liquidity mismanagement. A client might have $100 million in real estate but not $50,000 in cash for a tax bill. Advisors keep a “liquidity cushion” of 12–24 months of expenses, usually in boring government bonds.
Another common Gaffe: Ignoring inflation. UHNW advisors are obsessed with real returns (returns minus inflation). A 6% return feels great, but at 5% inflation, you’re actually gaining 1%. That’s why they buy infrastructure and farmland—things that tick up with the cost of bread.
Fun fact: The average UHNW client has 7 different advisors—bankers, lawyers, accountants. The “lead” advisor acts like a music conductor, making sure they don’t all play different songs.
 Top Private Wealth Management Firms USA for Ultra High Net Worth
The Human Element
Despite the exotic cars and Swiss accounts, the job is still deeply human. Advisors counsel clients through divorces, addiction battles, and the weight of inheriting a fortune at 25. They are part therapist, part actuary.
One veteran advisor told me that the hardest conversation is with the patriarch who wants to leave everything to the dog. “You have to balance the last wishes with the legal reality that a poodle can’t sign a tax return,” she laughed. That’s the job.
Practical Tip #3: The Annual “State of the Union”
Once a year, UHNW families hold a formal meeting with all stakeholders. You can do this too. Gather your partner (or yourself), review your net worth, insurance, and goals. Write it on paper. Visibility kills anxiety. The ultra-wealthy don’t check their portfolio daily; they check the plan.
What We Can Learn
The core lesson from the UHNW world isn’t about the money. It’s about intentionality. They don’t drift; they decide. They pay for advice not to get richer, but to stay where they are. For the rest of us, that translates into a simple truth: build a buffer, know your “enough,” and don’t let the noise shake your strategy.
After all, whether your portfolio is $50 million or $50,000, the sleepless nights come from the same place—fear of losing what you’ve built. A good advisor, at any level, just helps you sleep better. And that, right there, is the ultimate luxury.
