Ultra High Net Worth Investment Management

So, you’ve got a few extra million lying around. Maybe you found a rare diamond in your sock drawer, or your tech startup just got bought by a company that makes robot unicorn...
So, you’ve got a few extra million lying around. Maybe you found a rare diamond in your sock drawer, or your tech startup just got bought by a company that makes robot unicorns. Welcome to the world of Ultra High Net Worth (UHNW) investment management. It’s like regular investing, but with more zeroes, fancier wine, and a private jet to your financial advisor’s office—or, you know, a very good Zoom link.
The first thing you need to know: this isn’t your grandma’s retirement portfolio. She’s happy with a 4% return and a coupon for free oatmeal. You, my friend, are playing a different game. UHNW investing isn’t about just making money—it’s about preserving it, growing it, and sometimes using it to buy a small island nation (no judgment).
The "Family Office" (It’s Not a Daycare for Your Money)
Most UHNW families don’t just call a broker. They create a Family Office. This is a personalized team of experts—accountants, lawyers, whiz-kid analysts—who manage everything. Think of it as your own personal Avengers squad, but instead of fighting aliens, they fight taxes and inflation. Much scarier.
Must Read
A single-family office handles just one family’s wealth. A multi-family office is like a co-working space for millionaires—you share the costs but keep your secrets. Either way, they’ll obsess over your money so you can obsess over… yacht paint colors.
Asset Allocation: Not Just for Boring People
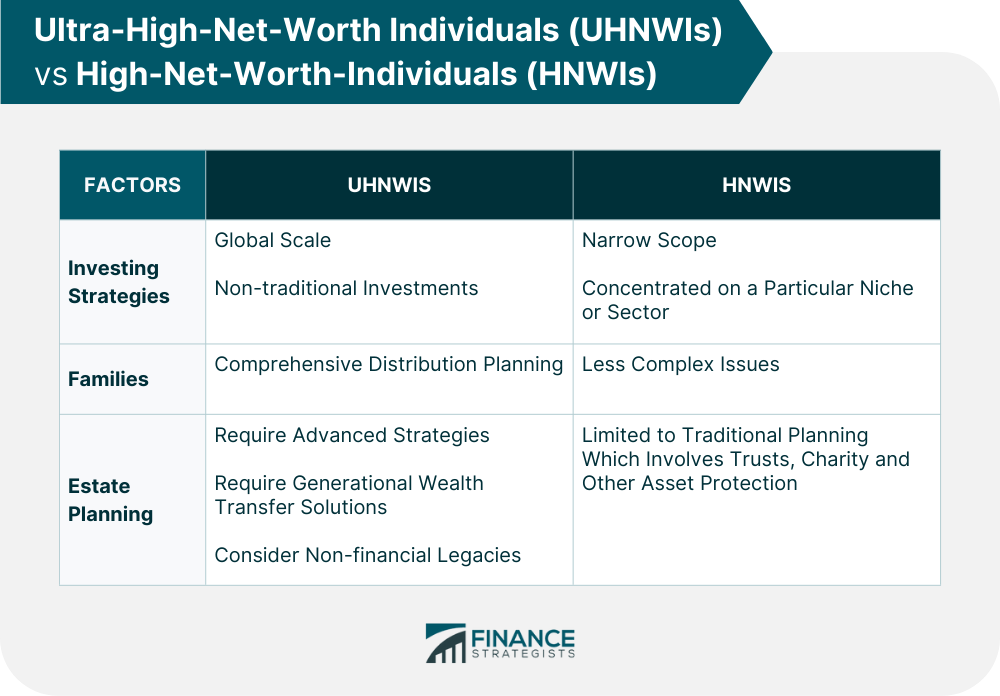
Regular folks own stocks and bonds. UHNW folks own alternative assets. We’re talking private equity, venture capital, hedge funds, real estate (the kind you can’t afford with a mortgage), and even fine art or vintage cars. Yes, that painting of a banana taped to a wall? Someone’s retirement plan.
Why? Because when you have a bazillion dollars, you don’t want your wealth tied to the stock market’s mood swings. Diversification is the name of the game. You spread your money across so many things that even if one tanking investment goes down, you barely notice—like losing a penny in your couch cushions.
Pro tip: Do not actually store cash in couch cushions. That’s for amateurs.
 Ultra High Net Worth Financial Advisors | Pillarwm
Private Equity: The VIP Club
Have you ever wanted to buy a whole company, not just a few shares? Enter private equity. UHNW investors pool money to buy companies, fix them up, and sell them for a profit. It’s like flipping houses, but the house is a national pizza chain or a robotics startup. Returns can be huge, but so is the risk—and the minimum investment (think seven figures).
Private equity is not for the faint of heart. You have to lock your money up for years. That basically means no impulse-buying a private island in the Bahamas until the fund matures. Tragic, I know.
Hedge Funds: The Wizards of Wall Street
Hedge funds are like the quirky, genius cousin of regular investing. They use complex strategies—shorting, leveraging, derivatives—to make money even when the market falls. Sounds magical, right? Sometimes it works, sometimes it’s a magic trick that goes wrong and your wallet vanishes.
Most hedge funds charge 2 and 20: 2% of your assets annually, plus 20% of any profits. That’s a lot. But if they turn your $50 million into $100 million, you probably don’t care about their fee. You’re too busy picking out a new car color—burnt orange, maybe?
 Ultra-High-Net-Worth Individual (UHNWI) | Definition & Statistics
Estate Planning: Because You Can’t Take It With You
Unless you’re planning a very fancy pyramid for yourself, you need estate planning. UHNW families use trusts, foundations, and strategic gifting to pass wealth to their kids without Uncle Sam grabbing a huge slice. Tax efficiency is the secret sauce here.
You might create a charitable foundation, donate art to a museum, or set up a trust that pays out when your family descendants achieve noble goals—like growing a perfect mustache or learning to juggle. Okay, maybe that last one isn’t standard.
The goal? Leave a legacy, not a tax bill. And maybe teach your heirs something about money—like that a gold-plated toilet is not an investment.
Philanthropy: The Fun Part
Once you’ve paid all the advisors and made your money multigenerational, you get to give it away. Many UHNW families set up foundations to fund causes they care about—clean water, education, or a giant statue of a cat. Impact investing is also big: putting money into companies that do good while still earning a return.
 Top Private Wealth Management Firms USA for Ultra High Net Worth
It feels good to give. Plus, it’s a great way to get your name on a building or a library. Just be prepared for friends to hit you up for cash. “Hey, remember that time we shared a pizza? Now I need a loan for a private school. Cool, cool.”
But Seriously, Is This Fun?
UHNW investment management can be thrilling—like playing Monopoly with real money. You get to meet brilliant people, invest in wild ideas (space tourism, anyone?), and worry about things like “Will my $20 million watch collection retain value?” The challenges are real, though. Managing huge wealth requires discipline, patience, and a good therapist to handle the guilt of having too much.
But here’s the uplifting truth: It’s not just about the money. The best UHNW investors use their resources to create freedom—for themselves, their families, and even their communities. They fund innovations, support artists, and sometimes, they just buy a coffee shop and give free lattes to everyone. You can, too.
So whether you’re a tech mogul, a lucky heir, or someone who just won the lottery (congratulations, by the way), remember: money is a tool. Invest it wisely, give generously, and never, ever forget to laugh. Because at the end of the day, your portfolio is just numbers on a screen. But the smiles you create? Those are priceless. And they don’t charge a management fee.
Now go forth, you magnificent money-magnate-in-the-making. And if you need a friend to help you spend it… I’m available. 😉
