Ultra High Net Worth Legacy Planning

So, you’ve made it. You’re an Ultra High Net Worth (UHNW) individual. Congratulations! Your biggest problem isn’t paying the bills anymore—it’s figuring out what to do with a...
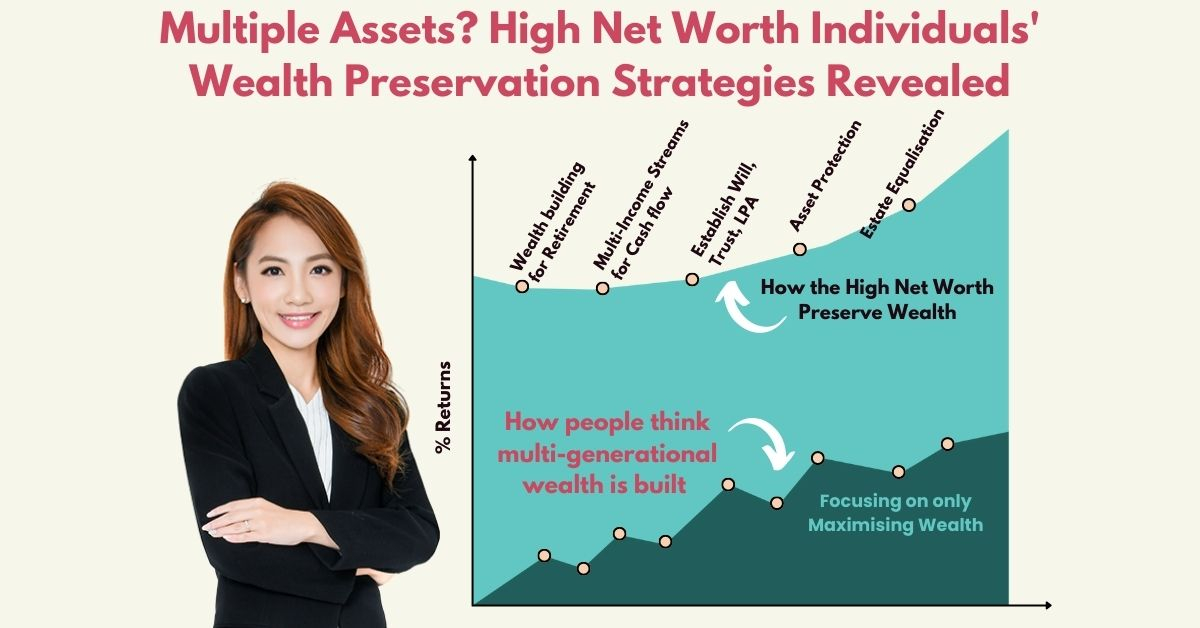
So, you’ve made it. You’re an Ultra High Net Worth (UHNW) individual. Congratulations! Your biggest problem isn’t paying the bills anymore—it’s figuring out what to do with a pile of cash so large it could probably buy a small country (or at least a very nice island with its own private jet runway). But here’s the thing: making the money is only half the fun. The real puzzle is keeping it in the family without turning your next Thanksgiving dinner into a scene from a reality TV show.
Welcome to the wild world of Legacy Planning. It sounds fancy, and it is. But at its core, it’s just a game of “Who gets what, and how do we avoid a family feud that ends with Aunt Carol hiding the good china?” Don’t worry, we’ll laugh our way through the complicated stuff.
The “Not-So-Great” Gatsby Problem
You’ve worked hard. You’ve built an empire. Maybe you started with a lemonade stand, and now you own the orchard. The last thing you want is for your heirs to treat your legacy like a cash machine for their yacht collection. This is where we talk about an Incentive Trust. It’s like a “good behavior” contract for your millions. Want the money? Great, show up to a real job for five years. No, a TikTok influencer gig doesn’t count—unless you’re selling accounting software.
Must Read
Think of it as a loving, slightly bossy letter from the grave. You’re basically saying, “I love you, but please don’t spend the family fortune on a solid gold toilet.” It works wonders, and it keeps the laughter going because, trust me, unearned money often leads to earned awkwardness.
The Art of the “No-Tax” Tax Tango
Now for the part that makes even the bravest CFOs sweat: taxes. The government loves your success almost as much as it loves taking a slice of it. But with UHNW legacy planning, we get to be sneaky—legally, of course! We use tools like GRATs (Grantor Retained Annuity Trusts) and IDGTs (Intentionally Defective Grantor Trusts). I know, the names sound like they were made up by a bored tax lawyer after three espressos. But they work.
 Wealth & Legacy Planning for HNWIs: Family Trusts Explained
Imagine you have a painting that’s worth $10 million today. You think it’ll be worth $15 million in ten years. Instead of giving it to your kid and paying a massive gift tax, you lend it to a trust. You get a tiny annuity payment back. When the painting skyrockets in value, all that growth goes to your kids tax-free. It’s like a magic trick, but instead of pulling a rabbit out of a hat, you’re pulling millions out of the IRS’s pocket. The rabbits are very jealous.
Don’t Forget the “Fun” Stuff: Charitable Remainder Trusts
You want to save the whales? Build a hospital wing? Pay for your high school’s new football stadium? Awesome. A Charitable Remainder Trust (CRT) lets you donate a huge asset, get a tax deduction now, and still get paid a nice income for the rest of your life. After you kick the bucket (or pass the checkered flag of life, as I like to call it), the charity gets the rest. It’s a win-win. You look like a saint, you save on taxes, and you get to laugh because you’re receiving checks from an asset you technically don’t own anymore. It’s deliciously clever.
 Top 10 Digital Wealth Management Platforms In 2024 – VNMNM
The Family Meeting: No Pitchforks Allowed
Here’s the secret sauce that most people forget: communication. You can have the most brilliant estate plan in the world, drafted by the fanciest lawyers in Geneva. But if your kids don’t know why you’re leaving the beach house to the younger one who actually visits you, you’re heading for a soap opera. Hold a “family summit.” Serve pizza. Be honest. Say, “Look, I love you all, but Sarah is a terrible investor, so her money is going to be managed by a bank. John likes fast cars, so his share is tied up until he turns 40. Don’t look at me like that, it’s for your own good!”
This little chat prevents the lawyers from becoming millionaires on your family’s drama. It builds true legacy—which isn’t just about money, but about trust and understanding. And if your kids still complain, just remind them that you could have left everything to a cat sanctuary. That usually shuts things up.
 Ultra-High-Net-Worth Individual (UHNWI) | Definition & Statistics
The Digital Ghost in the Machine
One more thing: your digital assets. You have crypto wallets, NFT collections of pixelated apes, and passwords to accounts filled with family photos. Don’t let those vanish into the cloud. Write down the keys—literally, on paper, in a fireproof safe. Tell your executor where the map to the treasure is. Otherwise, your grandkids will be yelling at a blockchain customer service bot for eternity. And trust me, that is a special kind of hell.
The Uplifting Punchline
Here’s the beautiful truth: legacy planning is not about dying. It’s about living on. It’s about making sure the values you held, the lessons you learned, and the resources you built don’t just vaporize into a cloud of legal fees and family squabbles. You’re not just leaving money; you’re leaving options. You’re giving your kids the freedom to fail, to try, to build their own dreams—maybe with a slightly softer safety net than you had.
So go ahead. Set up that trust. Write that letter. Buy that life insurance policy that’s so huge it needs its own zip code. But above all, laugh about it. Because at the end of the day, you can’t take it with you. And wouldn’t it be hilarious if you could? Imagine arriving in the afterlife and trying to pay St. Peter with a Platinum Amex. “Sorry, sir, we only accept good deeds here.” Plan well, love deeply, and leave a legacy that makes people smile—even when they’re reading the legal documents. You’ve earned it.
