Ultra High Net Worth Wealth Management

Let’s be honest: when you hear “Ultra High Net Worth Wealth Management,” you probably picture a guy in a thousand-dollar suit, sipping a latte on a private jet, stressing abou...
Let’s be honest: when you hear “Ultra High Net Worth Wealth Management,” you probably picture a guy in a thousand-dollar suit, sipping a latte on a private jet, stressing about whether his third yacht clashes with the sunset. But the reality is weirder, funnier, and far more relatable than you think. It’s basically the financial equivalent of having a really organized friend who reminds you to bring a snack, except the snack is a diversified portfolio of global real estate.
First, let’s define our terms. An Ultra High Net Worth (UHNW) individual is someone with at least $30 million in investable assets. That’s not “rich” in the “I can afford extra guacamole” sense. That’s “rich” in the “I could accidentally buy a small Mediterranean island and not notice until the property taxes hit” sense. Think of it as the difference between walking past a lemonade stand and buying the entire lemonade factory—and the orchard it came from.
So, what does wealth management look like for these folks? Forget the piggy bank, even a really fancy one. Their money isn’t just cash; it’s a tangled web of art collections, private equity stakes, family trusts, and an artisanal vineyard in Tuscany that produces exactly 47 bottles of wine a year. Managing it is like playing a game of chess where the pieces are worth more than your house, and the board is on fire.
Must Read
The “Family Office” Is Your Own Personal Bank
Many UHNW families create a family office—basically a mini-company dedicated to managing their money. Imagine hiring a CFO, a lawyer, a tax specialist, and a butler, all for your personal finances. It’s like having a team of personal assistants, but instead of fetching your dry cleaning, they’re negotiating the purchase of a private jet fleet.
Here’s the funny part: family offices often argue about the same stuff you do. “Should we rebalance the hedge fund allocation?” is just the billionaire version of “Should we order pizza or Chinese tonight?” The biggest crisis is often not about a stock market crash, but about whether the family’s art curator should buy a questionable NFT of a bored ape.
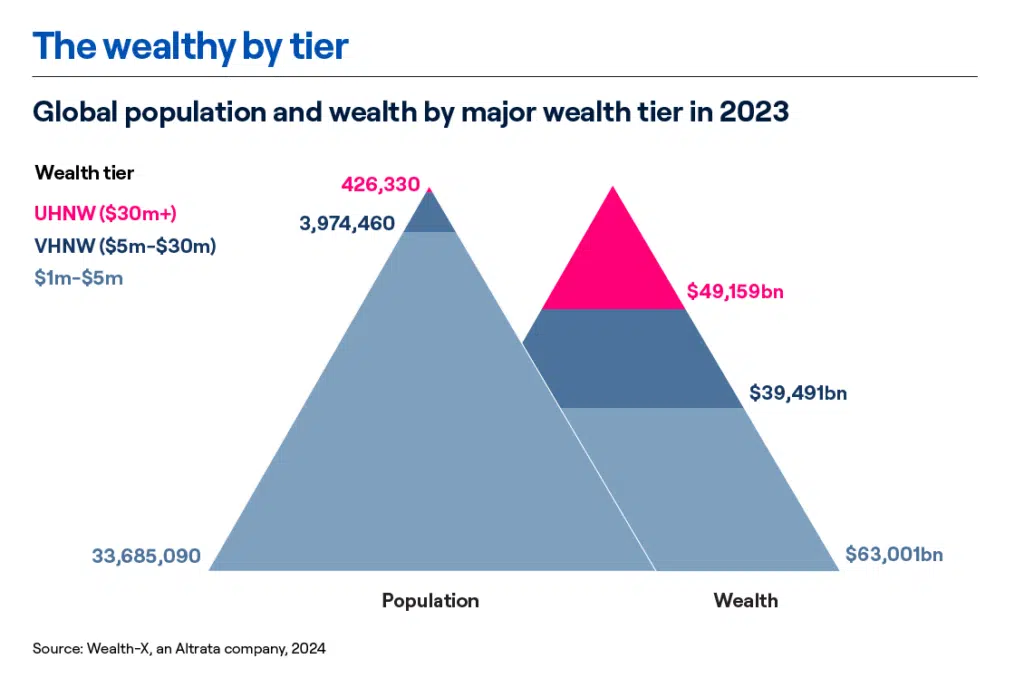 World Ultra Wealth Report 2024 - Altrata
The “Lifestyle Creep” That Ends Up on a Yacht
You know how you treat yourself to a slightly fancier coffee after a good week? UHNW individuals treat themselves to a yacht after a good quarter. But here’s the truth: a 200-foot yacht is basically a floating condo with a leaky engine and a crew of 15 who eat your food. One client I heard of bought a superyacht, then spent two years in anxiety because the Wi-Fi was spotty near the Galápagos Islands. First-world problems, meet the seventh circle of tech support hell.
Another classic situation: the “surprise inheritance.” A client’s eccentric uncle leaves them a 5% stake in a obscure mining company. Suddenly, you’re not managing stocks; you’re managing a family feud over whether to sell the stake to a rival or keep it for sentimental value. It’s like inheriting a slightly musty rug from Grandma, except the rug comes with a mine shaft and a lawsuit.
Taxes: The Universal Panic Button
Regardless of wealth, everyone hates taxes. The difference? You worry about your refund; UHNW clients worry about double taxation across three countries. Their accountants speak in a secret language: “We can do a GRAT, a CRUT, or maybe a QPRT.” Translation: “We’re going to shuffle your money through a legal labyrinth that even Theseus couldn’t navigate.” It’s like playing Monopoly but the rules change every time you land on a property, and the banker is a Swiss attorney in a turtleneck.
 Top Private Wealth Management Firms USA for Ultra High Net Worth
One client famously said, “I’d rather lose a million in a bad investment than pay a hundred thousand in unnecessary taxes.” That’s not logic; that’s emotion—the same emotion that makes you drive across town to save 10 cents on a gallon of gas, except the tank holds 200 gallons.
The “Philanthropy Paradox”
You might think rich people just hoard cash. But many UHNW families are surprisingly generous—with rules. They’ll fund a new hospital wing, but only if it’s named after their dog. They’ll donate to a museum, but insist the gallery is painted with a specific shade of beige. One family I read about set up a private foundation that funded a research project on high-altitude llama farming. Why? Because the patriarch thought llamas looked “dignified.”
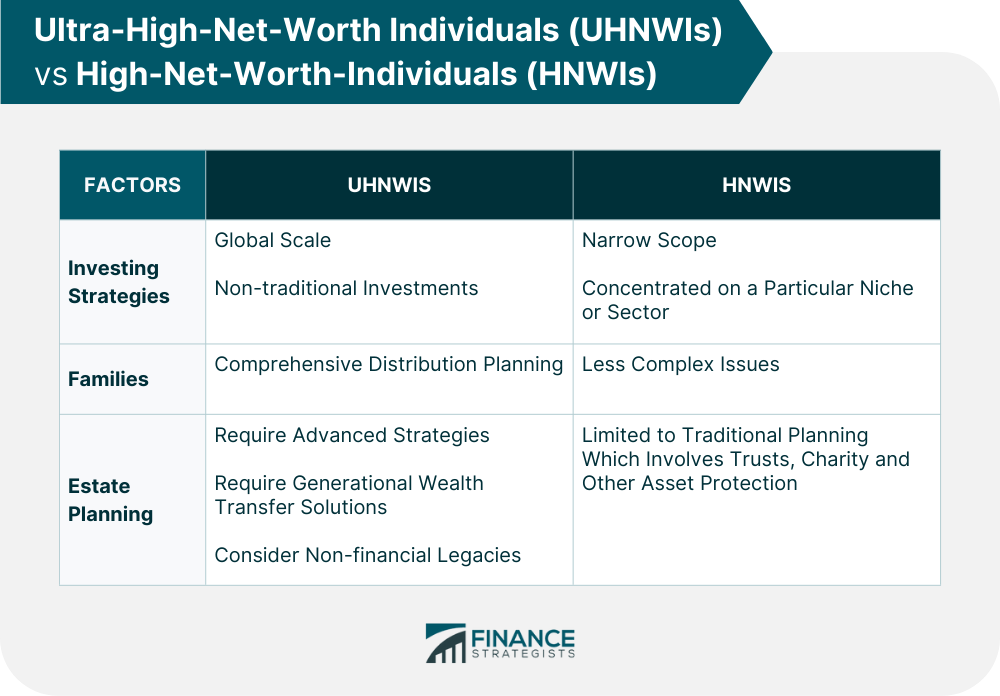 Ultra-High-Net-Worth Individual (UHNWI) | Definition & Statistics
This is where wealth management gets philosophical. It’s not just about numbers; it’s about legacy. “Do I want my name on a building, or do I want to buy a hockey team?” That’s the kind of conversation that happens over a $5,000 bottle of wine. And the answer is usually: “Yes, and a hockey team that plays in a building with your name.”
The Real Secret: It’s Still Just Money
Here’s the nod-and-smile moment. Deep down, UHNW people are just like you. They worry about inflation, but for them, it means their private jet fuel costs $10,000 more per flight. They stress about market volatility, but they stress in a panic room with a built-in espresso machine. They still have the same anxieties: “Will my kids be okay?” “Did I make the right choice?” “Why did I let my cousin invest in that wine futures scheme?”
So next time you hear “Ultra High Net Worth Wealth Management,” just picture a very organized, slightly anxious person with a gold-plated spreadsheet. They’re not superheroes. They’re just people who need help deciding whether to buy a second island or a first mountain. And honestly? That’s a problem most of us would love to have—though we’d probably just add extra guacamole and call it a win.
