Upper Middle Class Net Worth By Age

So, you want to know if you’re “doing okay” compared to the Joneses—the ones who drive a sensible German SUV and complain about their landscaper’s pricing. Let’s talk about up...
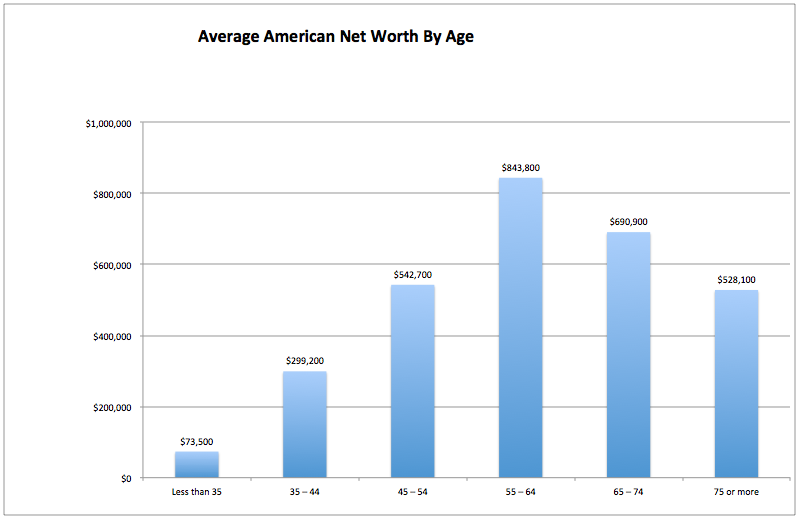
So, you want to know if you’re “doing okay” compared to the Joneses—the ones who drive a sensible German SUV and complain about their landscaper’s pricing. Let’s talk about upper middle class net worth by age. Spoiler: it involves a lot of spreadsheets, a splash of panic, and the haunting realization that your neighbor’s kid has a better 401(k) than you do.
The “Okay, But Are We Rich?” Zone
First, let’s define who we’re talking about. The upper middle class isn’t “yacht-and-private-island” rich—it’s “we can afford a vacation home that needs a new roof” rich. You probably have a graduate degree, a job that requires more meetings than actual work, and a deep emotional attachment to your espresso machine. Your net worth target is not just about cash—it’s about property, retirement accounts, and maybe a tiny crypto stash you pretend doesn’t exist.
According to the latest data from the Federal Reserve (yes, they have time for this), the sweet spot for upper middle class net worth at age 35 is around $500,000 to $1 million. That’s everything: your house, your 401(k), your Beanie Baby collection if you’re old enough. If you’re under that, don’t panic—just remember that your peers are probably eating ramen to fund their home equity.
Must Read
Your 20s: The “I’ll Sleep When I’m Rich” Phase
In your 20s, upper middle class net worth is a fantasy. You’re likely negative, thanks to student loans and a taste for craft cocktails. The goal here is not to have a net worth—it’s to start building habits. The magic number is about $100,000 by age 30, but let’s be real: most 25-year-olds would trade that for a working car and a rent-controlled apartment. Don’t stress—just avoid buying a boat. Boats are holes in the water you throw money into.
Surprising fact: the top 10% of 25-year-olds already have a net worth of $250,000. How? They either invented a fintech app or have parents who love them. For the rest of us, the real win is not having a credit score of 500.
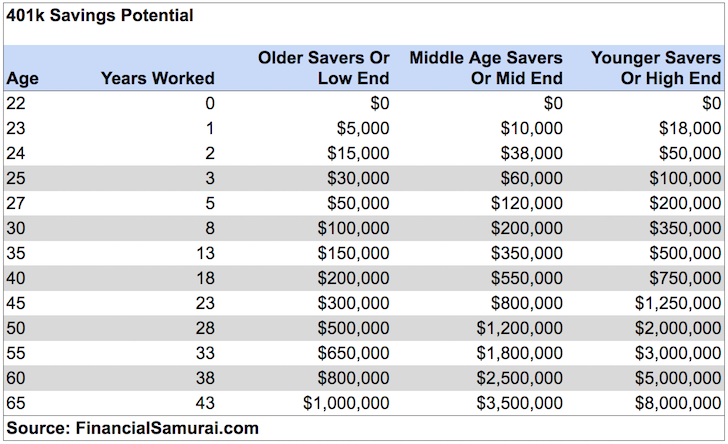 The Average Net Worth By Age For The Upper Middle Class
The 30s: Where You Realize Your Parents Were Right
By age 35, the upper middle class expects to hit $500,000. This is the decade where you buy a house, max out your 401(k), and start calling your retirement fund “Brenda.” But here’s the kicker: half of that net worth is often in home equity. So if your house is worth $700,000 and you owe $600,000, don’t pat yourself on the back too hard—you’re basically renting from the bank with extra steps. The real badge of honor is having $200,000 in liquid assets—cash, stocks, bonds—that doesn’t require a roof repair to access.
Funny story: the average 35-year-old in this bracket spends $1,200 a year on avocado toast. That’s not a joke. It’s a lifestyle investment. And if you skip the toast for a decade, you’ll have an extra $12,000. Congratulations, you can now afford a used Honda Civic. Priorities.
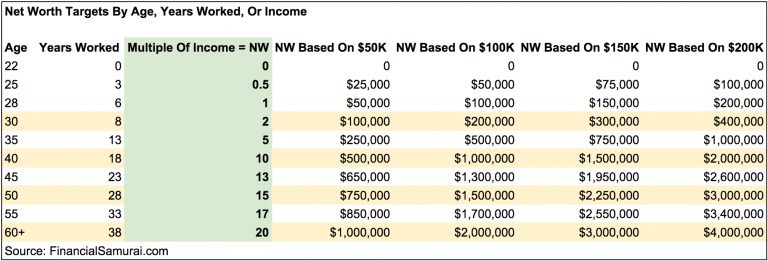 The Average Net Worth By Age For The Upper Middle Class
The 40s: The Age of “Did I Do Enough?”
At age 45, the upper middle class net worth target is $1.5 million. This is when your friends start “quiet quitting” their careers and buying sailboats. But here’s the ugly truth: the top 10% of 45-year-olds have $3.5 million. That’s 2.3 times the average. So if you’re sitting on $1 million, you’re upper middle, but you’re also the sucker who pays full price for airplane Wi-Fi. The key at this age is diversification: don’t put all your money in one thing, like a single stock or a vintage wine collection that smells like regret.
Surprising fact: 40% of upper middle class households at this age have a net worth that’s 70% tied up in their primary home. That means they’re one housing crash away from being “upper middle class in a trailer park.” Don’t be that person. Rent out the basement if you have to.
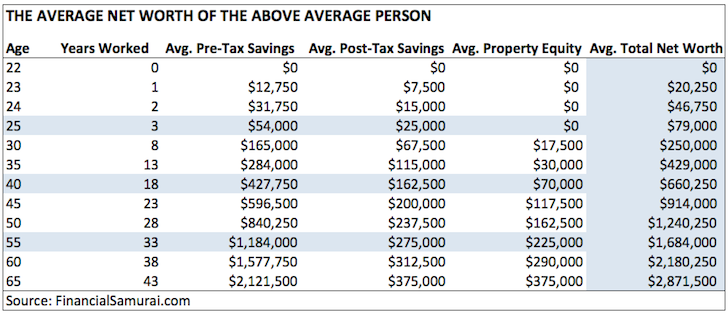 The Average Net Worth By Age For The Upper Middle Class
The 50s and 60s: The “Can I Retire Yet?” Countdown
By age 55, the goal is $2.5 million. This is the decade where you stop caring about avocado toast and start obsessing over Medicare premiums. The upper middle class here typically has $1 million in retirement accounts, a paid-off house worth $600,000, and a second property that’s a rental or a tax deduction. If you don’t have that, don’t worry—you can always plan to work until 85. Your grandkids will be thrilled.
At age 65, the magic number is $3.5 million. That’s enough to afford a nice retirement, assuming you don’t have a horse (horses are expensive) or a sudden desire to travel first class. The top 10% of 65-year-olds have over $10 million. They’re the ones who own the golf course, not just the memberships. For everyone else, the goal is to have 25 times your annual expenses saved. If you spend $80,000 a year, you’ll need $2 million. So, basically, be rich or be flexible.
The Big Takeaway (No Pressure)
Numbers are just guidelines—the real upper middle class secret is cash flow. You can have a net worth of $2 million but still feel broke if your money is locked in a house and a 401(k) you can’t touch. The funny truth is that many upper middle class folks are “house rich, cash poor.” That means they eat fancy cheese but worry about the electric bill. If you want to feel superior, just remember: the Joneses are probably paying for that SUV with a 7-year loan. You’re doing fine. Now go check your 401(k) balance and try not to laugh or cry. Or do both—it’s upper middle class appropriate.
