What Is Considered High Net Worth Individuals

So, my buddy Dave—who still clips grocery coupons and drives a 2012 Honda Civic—casually mentioned over beers that his neighbor just hit “HNWI status.” I choked on my IPA. HNW...
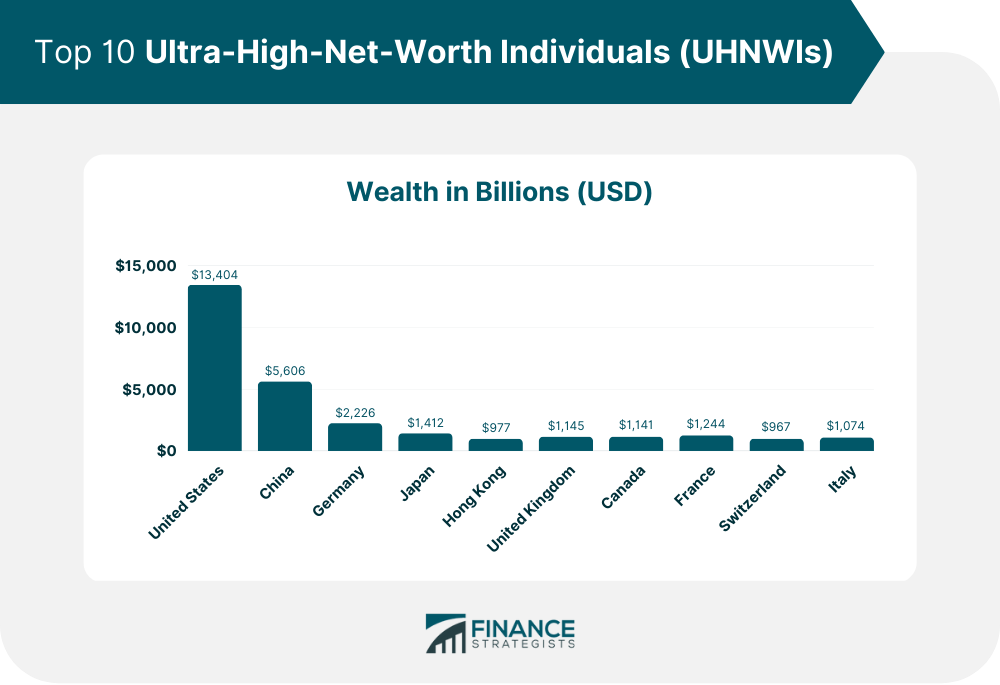
So, my buddy Dave—who still clips grocery coupons and drives a 2012 Honda Civic—casually mentioned over beers that his neighbor just hit “HNWI status.” I choked on my IPA. HNWI? It sounds like a sneeze, or maybe a new crypto exchange. But no. It stands for High Net Worth Individual. And let me tell you, that label comes with a very specific price tag.
Basically, these are folks who have a lot of liquid assets. We’re not talking about the equity in your home or your grandma’s vintage stamp collection. No, sir. We mean cash in the bank, stocks, bonds, and other stuff you could sell within 24 hours if you needed to buy a yacht on a whim. The magic number, according to most financial firms, is $1 million in investable assets, excluding your primary residence.
Now, you might be thinking, “Hey, my house is worth $800k! I’m almost there!” Whoa, slow down, big spender. That house is where you sleep. If you sell it, you’re homeless. The financial industry does not care about your cozy living room. They care about money that can move—money that buys securities, private equity, and yes, that conversation-starting art piece.
Must Read
The Tiers of Rich: More Than Meets the Eye
Just calling someone “wealthy” is too vague for this club. They have levels, like a video game for the ultra-prepared. The first step is the HNWI (High Net Worth Individual)—you know, the million-buck club. Then you get the VHNWI (Very High Net Worth Individual), which starts at around $5 million. That’s the point where you can probably afford to stop checking your bank balance every morning.
And then? The UHNWI (Ultra-High Net Worth Individual). These are the titans, the Space X investors, the people who have “family offices” that handle their laundry… and their taxes. The threshold for UHNWI is usually $30 million or more. Think of them as the final boss of capitalism. They don’t worry about inflation; they cause inflation by buying all the Aspen real estate.
 High-Net-Worth Individual (HNWI) | AwesomeFinTech Blog
What Counts (and What Doesn’t)
This is where it gets tricky, and where most of us get our feelings hurt. Your 401(k) counts. Your stock portfolio counts. That vintage Rolex from your dad? Nope. Financial firms hate illiquid assets unless they are called “alternative investments.” If you have to find a buyer and argue about authenticity, it’s not an HNWI asset. It’s just a nice wristwatch.
Also, debt is a total buzzkill here. If you own a $2 million business but owe $1.9 million to the bank, you’re not a HNWI. You’re just a very busy person with a lot of risk. The calculation is assets minus liabilities. Simple math, but with zero room for motivational accounting. Sorry, entrepreneur guy.
 Wealth Management Marketing Strategies for a Brighter 2024
Why Do We Even Care About This Label?
Here’s the ironic part: banks and wealth managers care way more than the actual rich people do. If you’re a HNWI, you get access to special things. Better interest rates? No. But you get “private banking” where they call you by your first name. You get invites to exclusive investment dinners where they serve tiny, expensive sandwiches. It’s a membership card to a club where the main activity is protecting your money from the guy who wants to sell you a timeshare.
But honestly? Most HNWIs I’ve met (and yes, I’ve served a few coffee) seem stressed. They worry about market corrections. They worry about their kids marrying the wrong person. They worry about whether their private jet is “too flashy.” Money solves a lot, but it also creates new, very specific anxieties. Like, “Is my accountant on vacation? Who’s monitoring my Swiss account?”
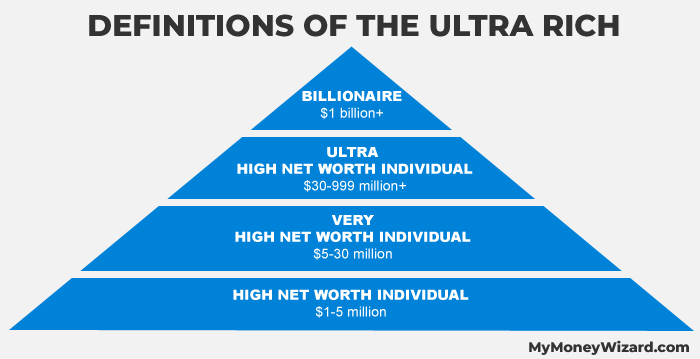 What's actually a high net worth? 11 wild statistics and 4 life lessons
The Bottom Line (a.k.a. The Reality Check)
So, are you a HNWI? If you laughed and said “not even close,” welcome to the club. Most of us are mass affluent at best—meaning we have some savings but still clip coupons like my buddy Dave. And that’s fine. Being a HNWI isn’t a moral victory; it’s just a tax bracket. Actually, it’s a wealth bracket. There’s a difference.
The real secret? Time is the only asset class you can’t trade. You can be a HNWI at 60 and have never done a cartwheel in your life. Or you can be broke at 30 and have a killer travel blog. The label just helps banks sell you index funds with fancier names. It’s a social construct with a very real number attached: $1,000,000.00. So next time someone drops “HNWI” at a party, just nod, sip your drink, and remember: they probably still have to file their own taxes. We all do.
