What Is The Average Net Worth In The United States

Let’s be real for a second. Have you ever woken up, checked your bank account, and wondered, “Am I doing okay?” You’re not alone. That little number—your net worth—is the ulti...

Let’s be real for a second. Have you ever woken up, checked your bank account, and wondered, “Am I doing okay?” You’re not alone. That little number—your net worth—is the ultimate scoreboard for your financial life.
So, what’s the magic number?
According to the latest data from the Federal Reserve, the average net worth in the United States is about $1.06 million. Yeah, you read that right—over a million bucks.
But before you panic and throw your phone across the room, hold up. That number is wildly misleading. Averages get skewed by folks like Jeff Bezos or your neighbor who invented a weird app for organizing socks.
Must Read
The real story is the median.
The median net worth in the U.S. sits at around $192,000. That’s the actual middle: half of households have more, half have less. Suddenly, that million-dollar average feels like a weird flex from the 1%, right?
Why the gap? Because a few super-rich people pull the average up like a giant financial balloon. Meanwhile, the median tells us what a “normal” family is actually working with—home equity, savings, maybe a 401(k) they’ve been feeding for years.
Here’s a fun comparison: imagine a party with ten people. One guest is Elon Musk, and everyone else is a librarian. The average net worth at that party would be billions. But the median? Probably just a few hundred thousand. You want to be the median guest, not the average one.
What makes up that $192,000?
About a third of that wealth comes from home equity. If you own a house in a decent neighborhood, congratulations—you’re probably richer than you think. That’s why renters usually have a much lower net worth.
 Average Net Worth by Age in the US: Are You on Track
Retirement accounts are the next big chunk. Your 401(k) and IRA are like slow-growing magic beans. Add in a little cash, maybe a car (though cars are terrible investments because they lose value fast), and you’ve got your number.
Oh, and student loans? They’re the opposite of net worth, dragging you down like an anchor. Debt subtracts directly from your net worth, which is why that number can be negative for many young people.
How do you stack up by age?
For people under 35, the median net worth is only about $39,000. That’s not a typo. Most Gen Zers and millennials are still building—paying off student loans, saving for a down payment, buying avocado toast (guilty).
For ages 55–64, the median shoots up to $400,000. That’s the sweet spot: decades of compound interest, a paid-off mortgage, and maybe some inheritance from your cool aunt.
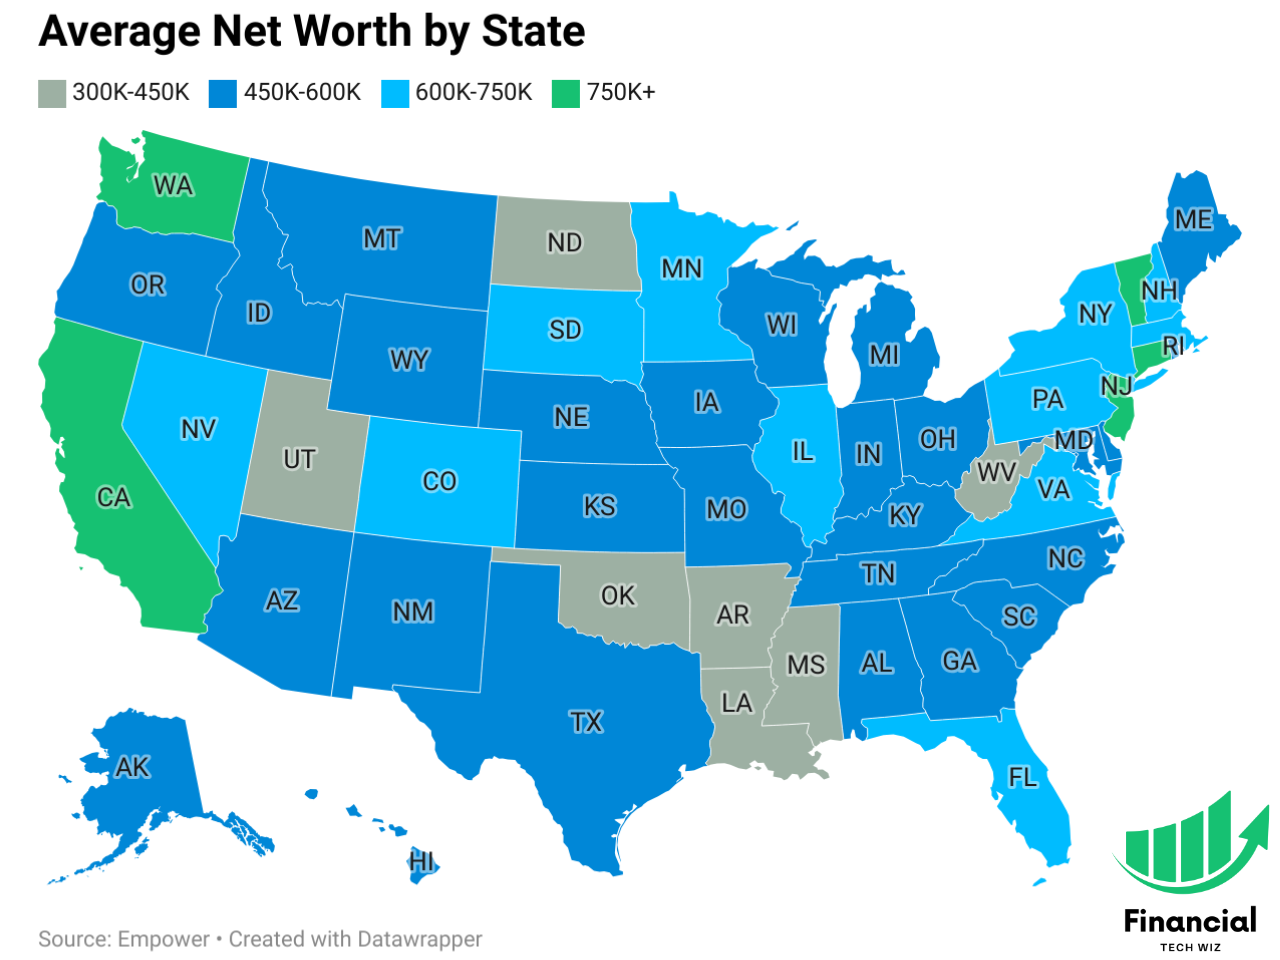 Net Worth by State (2026): Median and Average Rankings
So if you’re 25 and have $5,000 saved? You’re ahead of the curve. The race is long, and it’s mostly against yourself.
Why should you even care?
Net worth isn’t about bragging rights. It’s a tool—like a GPS for your money. Knowing where you stand helps you set realistic goals. Want to retire at 50? Buy a tiny house in the woods? Travel the world? Your net worth is your fuel gauge.
Plus, it’s kinda cool to watch grow. Think of it like a video game level: every time you pay off a credit card or get a raise, your XP bar moves up. Satisfying, right?
But here’s the secret: comparing yourself to the average is a trap. The U.S. is a massive country with wildly different costs of living. Living in San Francisco? You need a much higher net worth just to breathe. In rural Kansas? $100,000 makes you feel like royalty.
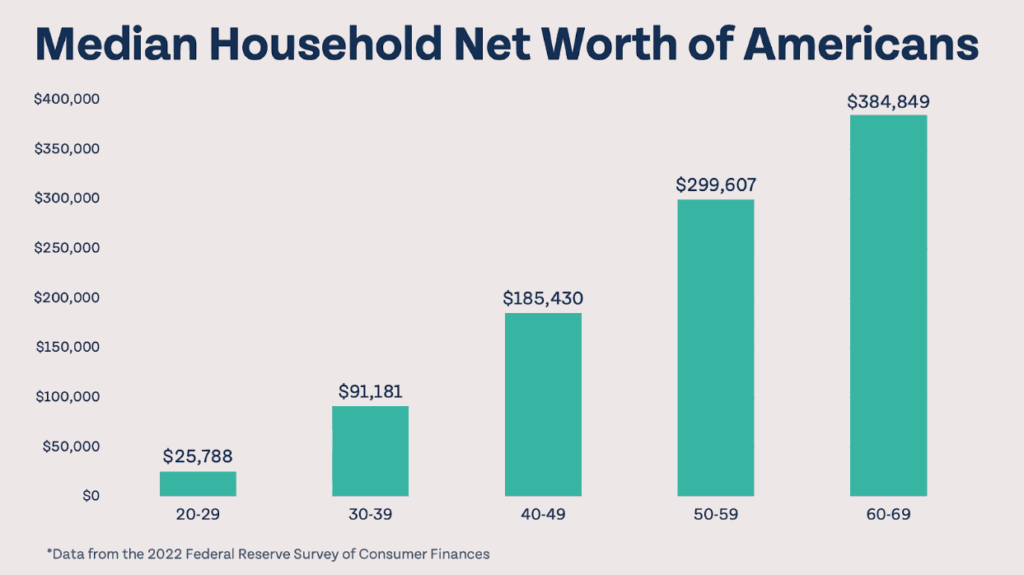 Income Levels America Chart U.S. Incomes Stabilize For First Time
Let’s get weird with comparisons.
The average net worth of a U.S. household could buy you 27,000 Big Macs. Or roughly two brand-new Ferrari Portofinos. Or maybe one tiny, sad-looking apartment in Manhattan’s SoHo neighborhood. Fun, right?
Another way to think: if you stacked $1.06 million in dollar bills, the pile would be about as tall as a 10-story building. That’s a lot of paper, but not exactly life-changing for the billionaires who own that building.
The bottom line (chill version).
For most people, net worth isn’t about being a millionaire. It’s about flexibility. It’s the freedom to say “no” to a bad job, or “yes” to a spontaneous road trip.
So check your numbers once a year. Ditch the debt slowly, save a little automatically, and ignore the hype. The average net worth is interesting, sure, but the only number that matters is yours—and how it helps you sleep at night.
Now go pay off that credit card bill. You’ve got this.
