What Net Worth Is Considered Top 1 Percent

You’re scrolling through your feed, half-watching a show, when a headline pops up: “This is the Net Worth You Need to Be in the Top 1 Percent.” Your thumb hovers. Is it a mill...
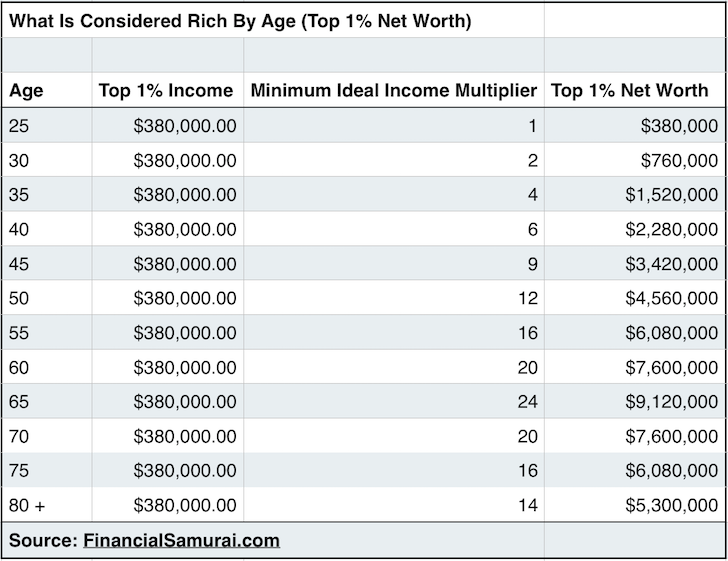
You’re scrolling through your feed, half-watching a show, when a headline pops up: “This is the Net Worth You Need to Be in the Top 1 Percent.” Your thumb hovers. Is it a million? Ten million? A hundred? The truth, it turns out, is both more specific and more surprising than you’d guess. And it’s not just about the rich—it’s about how we measure success in the modern world.
The Number That Separates the Elite
As of late 2023, the global threshold for the top 1 percent of wealth is roughly $1.1 million in net worth, according to the Knight Frank Wealth Report. But don’t pack your bags for Monaco just yet. That figure lumps everyone together, including folks in rapidly growing economies where a million bucks buys a different kind of life.
In the United States, the bar is significantly higher. You need a net worth of about $5.8 million to join the top 1 percent, according to data from the Federal Reserve and Wealth-X. That’s the number that makes your jaw drop at a dinner party—until someone mentions real estate in San Francisco.
Must Read
To put it in perspective: only 1.3 percent of U.S. households have a net worth above $5 million. So, if you’ve ever thought “everyone’s rich on Instagram,” remember that the algorithm hides the math. The top 1 percent is a very, very small club.
What Counts as Net Worth? (Spoiler: It’s Not Your Salary)
Here’s the fun part: net worth isn’t your annual paycheck. It’s assets minus liabilities. That means your house, your retirement accounts, your investments, your art collection, and even that vintage comic book stash—minus your mortgage, student loans, and credit card debt. A neurosurgeon earning $600k a year might still have a net worth of $1 million if they’re drowning in debt from a fancy home and a boat.
Conversely, a retiree in a paid-off house with $2 million in stocks is closer to the top 1 percent than you’d think. This is why net worth is a better snapshot of financial stability than income. It’s the difference between looking rich and being rich.
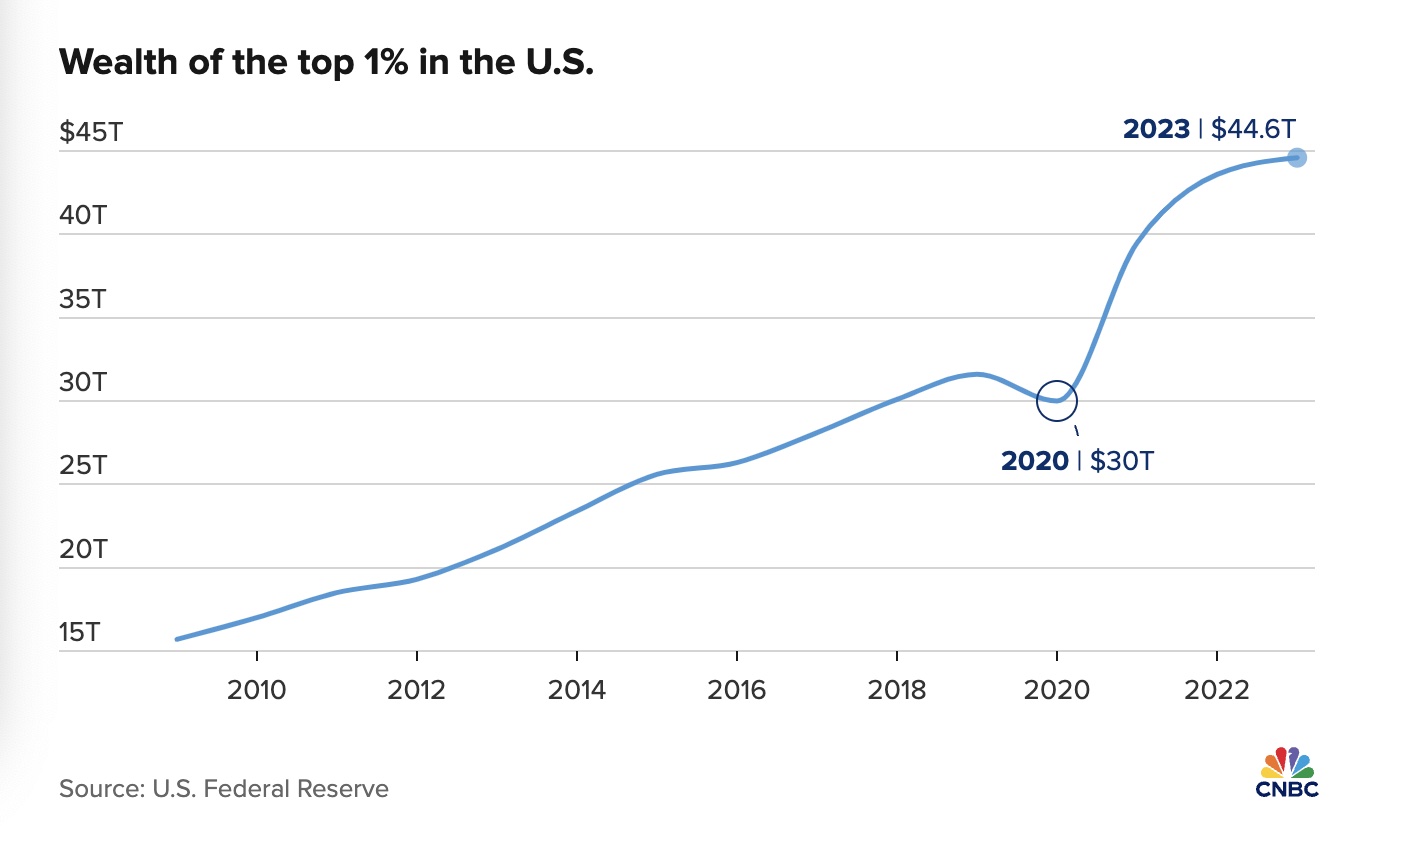 Joe Biden's America: Wealthiest 1% Set Record with $44 Trillion Total
Fun Fact: The Geography of Wealth
Where you live changes everything. To be top 1 percent in Monaco, you need over $12 million. In Switzerland, it’s around $6.6 million. But in Indonesia? The threshold drops to about $60,000. Suddenly, your neighborhood coffee shop’s owner might be a global elite—just not in your zip code.
This geographical twist is why your friend who moved to rural Vermont feels “rich” while the Manhattan banker feels “middle class.” Wealth is relative, and it’s also deeply tied to cost of living. The top 1 percent in one place is a comfortable millionaire; in another, it’s a monarch.
Cultural References: The “Old Money” vs. “New Money” Divide
Think of The Great Gatsby. Jay Gatsby had the parties, the house, and the mystery—but he never had old money’s quiet confidence. Today, the top 1 percent includes both: a tech founder with a crypto fortune and a trust-fund heir with a vineyard in Tuscany. The difference is liquidity. Old money tends to be in land, art, and bonds; new money is often in stocks, startups, and—cringe—non-fungible tokens.
Pop culture loves to poke fun at this. Remember the Succession Roy family? Their net worth was probably in the tens of billions, but they still worried about “keeping up” with the Murdochs. Even at the top, the game is competitive. The takeaway? Net worth is a number, not a personality.
 Net Worth Benchmarks To Ensure Proper Growth Over Time
Practical Tips for Your Own Wealth Journey
Stop comparing your net worth to the top 1 percent. That’s like comparing your commute to a private jet. Instead, focus on your own personal top 1 percent—the version of you that has enough savings to feel secure. Start with these steps:
1. Calculate your net worth today. List every asset and every debt. Use a simple spreadsheet or an app like Mint. It’s not about a big number; it’s about knowing where you stand. Most people overestimate their spending and underestimate their debt.
2. Automate your investments. Even if it’s just $200 a month, put it into a low-cost index fund. The power of compound interest is quiet but brutal—for your old spending habits, not for you.
3. Avoid “lifestyle creep.” When you get a raise, don’t buy a fancier car. Invest the difference. The top 1 percent didn’t get there by leasing luxury SUVs; they got there by letting their assets work while they slept.
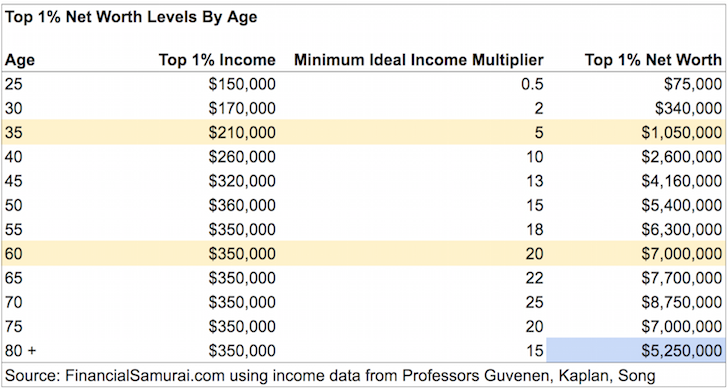 Hope Garcia: Net Worth Benchmarks To Ensure Proper Growth Over Time
4. Consider your housing. In expensive cities, your home equity can be a massive part of your net worth. But don’t assume your house is a golden ticket. It’s not liquid until you sell it. Treat it as a place to live first, an investment second.
A Little Perspective: The “Fun Fact” About Time
If you save $1,000 a month and earn a 7% average return, you’ll have over $1.2 million in 30 years. That’s not top 1 percent globally—but it’s comfortably in the top 10 percent for most countries. The trick is time, not talent. Most of us have more of the former than we think.
Connecting It to Your Daily Life
So you’re not the top 1 percent. That’s fine. The real wealth is in the choices you make every day: the cup of coffee you skip, the skill you learn, the conversation you have with your partner about money. Net worth is a metric, but net happiness is a lifestyle.
Next time you see that headline, smile. Remember that the top 1 percent includes people who are lonely, anxious, and still scrolling. Your life, with its messy accounts and honest dreams, is already richer than you think. The goal isn’t to be them—it’s to be your own version of enough.
