What Percent Of Your Net Worth Should Your House Be

So, you’re sitting there, maybe scrolling Zillow or staring at your monthly mortgage payment, and a thought pops up: Did I just bet the farm on this house? You’re not alone. I...
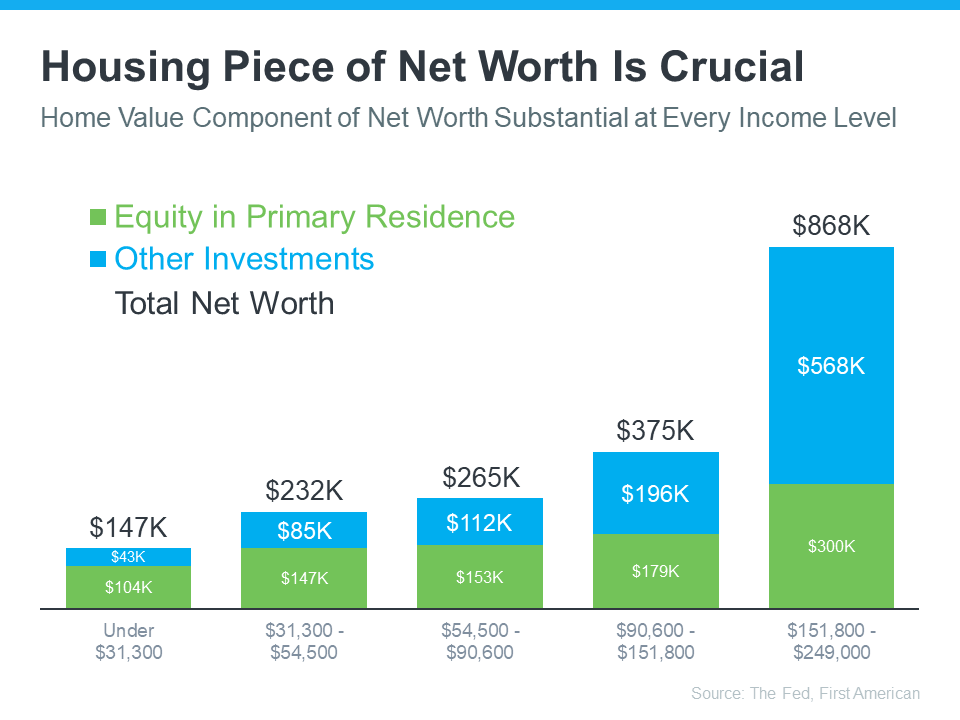
So, you’re sitting there, maybe scrolling Zillow or staring at your monthly mortgage payment, and a thought pops up: Did I just bet the farm on this house? You’re not alone. It’s the big, scary money question that nobody puts on a dinner party napkin. But let’s chat about it over our metaphorical coffee—black with a splash of common sense.
Why This Number Even Matters
Your house is probably the biggest thing you own. It’s also the biggest debt you carry, unless you hoard vintage cars. So the percentage of your net worth tied up in it matters—a lot.
Think of your net worth as your entire financial toolbox. If almost all your tools are one giant hammer, you can’t fix a watch or build a birdhouse. You’re stuck hammering everything, including your future dreams.
Must Read
Too much house makes you brittle. One job loss, one market dip, one surprise roof leak, and your whole toolbox feels wobbly. Diversify, my friend. Don’t be a one-trick pony with a mortgage.
The Magic Number (Spoiler: It’s Not One Size Fits All)
Here’s the rule of thumb that makes the most sense: your primary residence should make up no more than 30% to 40% of your total net worth. Yes, really. That feels low, right? I know. It’s like telling a kid they can only have one scoop of ice cream.
If you’re under 40, aim for the lower end—30% or less. Your superpower is time, and you need cash to invest in stocks, side hustles, or that questionable crypto your buddy keeps texting about.
If you’re older, say 50+, you might nudge up to 40%. Your house might be your retirement anchor, especially if you plan to downsize. But don’t go past 50% unless you own a literal castle. Even then, reconsider.
But What If You Live in an Expensive City?
Oh, you mean San Francisco, New York, or Seattle? I see you. You’re probably looking at your 80% house-value-to-net-worth ratio and laughing bitterly. That’s real. It’s also a trap.
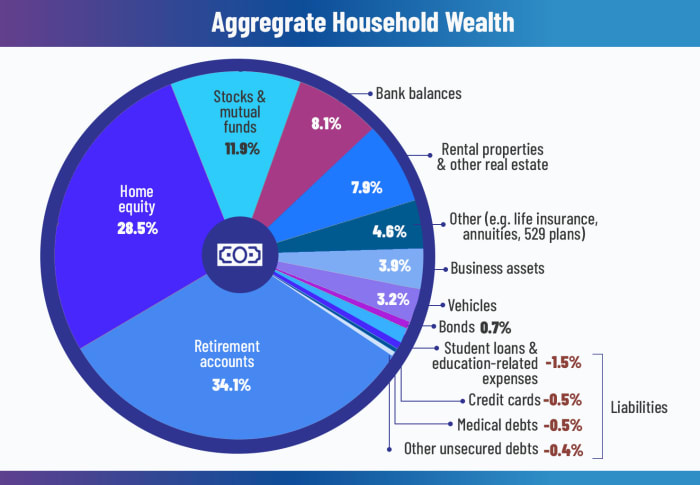 U.S. Net Worth: How Household Wealth Breaks Down - TheStreet
The solution is brutal but freeing: rent or buy less house. I know, “buy less house” sounds like a bad joke when a shoebox costs a million. But if your home eats 80% of your net worth, you’re not building wealth—you’re a tenant of your own equity.
Ask yourself: would you rather own a fancy doorstop or have money to travel, invest, and retire early? The answer isn’t sexy, but it’s honest. Blame the latte, not the city.
The “Safe” Exceptions to the Rule
Okay, let’s be fair. There are times when it’s fine to have a higher percentage. If you bought a house for $200k and it’s now worth $600k while your stocks tanked, you’re not reckless—you’re lucky. Luck counts for something.
Another exception: paid-off houses. If your house is fully yours, free and clear, the percentage can be higher because your “debt” side is zero. That changes the math. You can sleep on a mattress of cash, metaphorically.
But if you still owe a fat mortgage, keep that percentage low. A paid-off house is a shield. A big mortgage is a sword pointed at your own foot. Choose wisely.
 Primary Residence Value As A Percentage Of Net Worth Guide
How to Calculate Your Own Number (Painlessly)
First, find your net worth. Add up everything: savings, retirement accounts, stocks, that old guitar you swear is vintage. Subtract all debt: credit cards, student loans, the mortgage. The leftover is your number. Don’t fret if it’s small—everyone starts somewhere.
Next, find your home’s value. Use Zillow’s estimate, but take it with a grain of salt. It’s a zestimate, not a fact. Now divide your home value by your net worth. Multiply by 100. Boom—your percentage.
If you get 45% or higher, it’s time for a serious coffee chat with yourself. Maybe that’s fine. Maybe you need to sell or invest more. But at least now you know. Knowledge is the first step to not panicking.
The One Percent Rule (That Isn’t About Rent)
Here’s a playful metric to aim for: your house should be less than one percent of your net worth per square foot. That’s a weird one, right? Try it. A 2,000-square-foot home means your net worth should be at least $200,000. If not, your house is a bit heavy.
It’s a silly rule, but it makes you think: is your house earning its keep in your life? Or is it just a giant financial anchor wearing a cozy sweater? Houses consume money—taxes, repairs, paint. They don’t pay you back unless you sell.
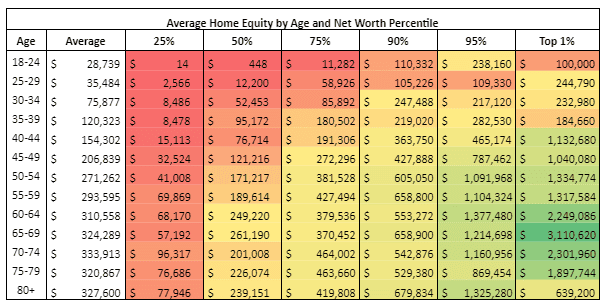 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
Remember: a house is a place to live, not a retirement plan. If it’s both, great. But don’t bet your future on a rising market. Markets have bad manners and occasionally fall down drunk.
What to Do If Your House Is Too Big a Slice of the Pie
Don’t panic. Seriously, put down the calculator. You have options. First, stop buying more house—no upgrades, no bigger backyard. Let your investments grow and your lifestyle stay flat.
Second, consider a cash-out refinance (if rates are low) or selling and downsizing. Downsizing isn’t failure; it’s financial freedom in a smaller box. Less lawn to mow, less money to worry about.
Finally, invest your extra cash. Put money into index funds or a retirement account. Over time, your net worth will grow faster than your house’s value. That percentage will shrink naturally, like a good pair of jeans after a diet.
And honestly? The best thing you can do is stop comparing your house to your neighbor’s. Their percentage might be a disaster. Yours is yours. Own it—literally and figuratively.
So, coffee finished? Good. Go check your numbers. If your house is 50% or more of your net worth, start making a plan. If it’s 30%, pat yourself on the back. And if it’s 10%? You’re basically a financial ninja. Go buy another coffee. You’ve earned it.
