What Percentage Of Net Worth Should Be In Home

Okay, friend. Let’s talk about the big, scary money question that keeps you up at 3 AM. You know the one: “How much of my net worth should be sitting under my roof?” It’s lik...
Okay, friend. Let’s talk about the big, scary money question that keeps you up at 3 AM. You know the one: “How much of my net worth should be sitting under my roof?”
It’s like trying to fit an elephant into a Mini Cooper. You know it’s important. But where do you even start?
First, let’s admit something hilarious. Your house is not just a home. It’s a giant, illiquid, sometimes-leaky piggy bank.
Must Read
The Magic Number (Or, The Liar’s Answer)
Financial gurus love throwing out neat percentages. You’ll hear “25%” or “30%” of your net worth. Sounds clean, right? Wrong.
The truth is messier than a toddler’s birthday cake. The right percentage depends on where you live and how gutsy you feel.
If you’re in San Francisco, your home might be 60% of your net worth. If you live in rural Ohio? Maybe 15%. It’s all relative, my friend.
Why the “Rule of Thumb” is Actually a Thumb-Breaker
I once heard a rule: “Your home should be no more than 3x your annual income.” Cute. Too simplistic for real life.
What if you bought at the peak of the market? Or what if you inherited a mansion from Aunt Gertrude? That rule goes out the window.
Instead of a hard number, think about balance. Is your house eating your life savings for breakfast? That’s a problem.
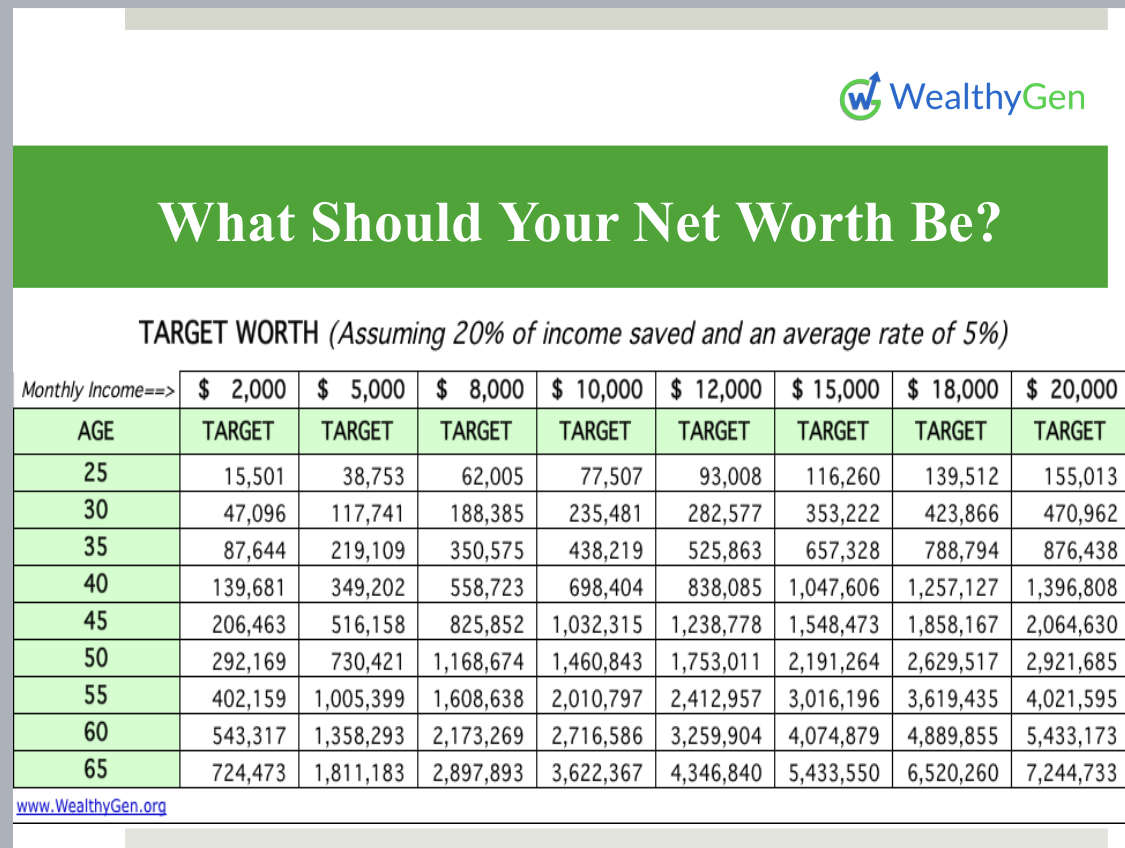 THIS IS WHAT YOUR NET WORTH SHOULD BE - WealthyGen Foundation
The Sneaky Trap of Being “House Rich, Cash Poor”
Here’s the nightmare scenario. Your home value is huge—congratulations! But your bank account is a tumbleweed.
You’re eating ramen while living in a marble palace. Fun for Instagram, terrible for your retirement. Don’t be that person.
Your net worth is a pie. If your house takes a giant slice, you have nothing left for emergencies, vacations, or that weird stock you’re betting on.
Let’s Do Some (Painless) Math
Okay, pull out your phone calculator. No, I’ll wait. Add up everything you own: house, car, savings, that Beanie Baby collection.
Now divide your home’s value (minus what you owe) by that total. Multiply by 100. Got a number? Great.
If it’s over 50%, you might be too heavy on bricks. If it’s under 15%, either you rent or you’re a stock market wizard. Good for you.
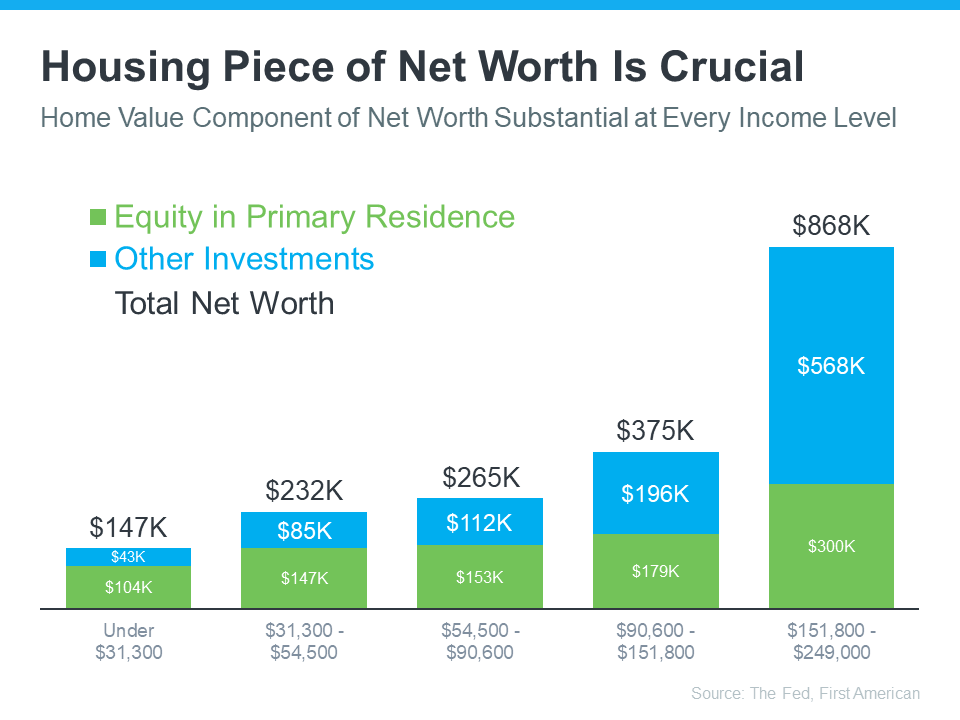
 A Homeowner’s Net Worth Is 40x Greater Than a Renter’s
What Do the Smart People Say?
I polled a few finance nerds (over terrible coffee). Most said: keep your home equity under 40% of your total net worth. Anything higher is a red flag.
But here’s their dirty secret. This rule mostly applies to younger people. If you’re 60 and paid off your house, 70% equity is totally fine.
Why? Because you have less time to recover if the market crashes. Young folks? They can ride out the storm. Old folks? They need a safe harbor.
The Great Exceptions (Because Life is Weird)
Maybe you live in a crazy expensive city. Or maybe you bought a fixer-upper for peanuts. Your percentage might be whack.
Don’t panic. Rules are more like guidelines. You know, like the Pirate Code.
The real danger is leverage. If you have a huge mortgage, your percentage can flip overnight. A 10% market drop could wipe out 50% of your equity. Yikes.
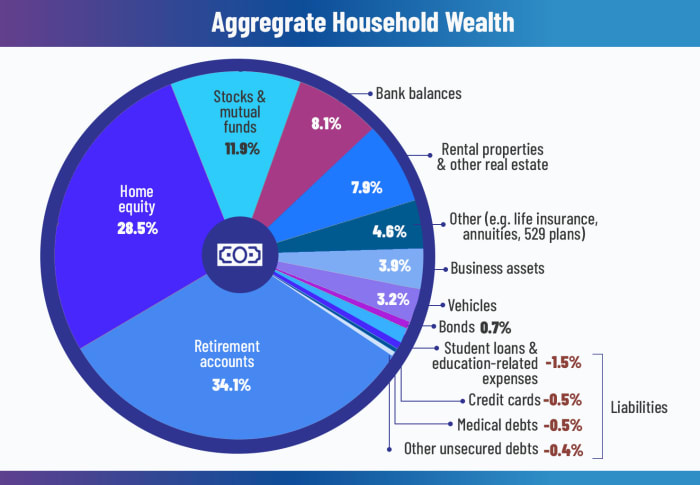 U.S. Net Worth: How Household Wealth Breaks Down - TheStreet
How to Fix a Lopsided Net Worth
If your home dwarfes everything else, here’s your to-do list. Stop paying extra on your mortgage. I know, it sounds crazy.
Instead, shovel that cash into retirement accounts or index funds. Diversify, baby! Your house doesn’t care about your retirement dreams.
You can also rent out a room. Or, if you’re feeling spicy, sell and downsize. Freedom tastes better than a spare bedroom.
The Final (Playful) Verdict
There is no perfect percentage. There is only your situation and your comfort level. If you can sleep at night, you’re probably fine.
If you worry your house is a paperweight made of debt? Maybe it’s time to lighten the load. Your net worth is a tool, not a trophy.
So go check that number. And if it’s scary? Laugh it off, then make a plan. You’ve got this.
Now, can we talk about something easier? Like, why is coffee so expensive these days? That’s the real financial crisis.
