What Percentage Of Net Worth Should Be In Real Estate

Let’s be honest: figuring out how much of your net worth should be in real estate feels like trying to decide how much cheese to put on a nacho platter. Too little, and you’re...
Let’s be honest: figuring out how much of your net worth should be in real estate feels like trying to decide how much cheese to put on a nacho platter. Too little, and you’re a sad, dry snack. Too much, and you’re a heart attack in a tortilla chip. For your financial life, the "perfect" percentage is a moving target, but I’ve got the napkin math you can actually use.
First, let’s get the boring-but-necessary truth out of the way: most financial planners will tell you to aim for 20% to 30% of your total net worth in real estate. That’s the sweet spot for diversification—enough to benefit from price appreciation and rental income, but not so much that you’re broke when the water heater explodes. But honestly, who listens to financial planners? They probably own zero cool properties and have a spreadsheet named "Retirement.xlsx."
The "You Live Somewhere" Problem
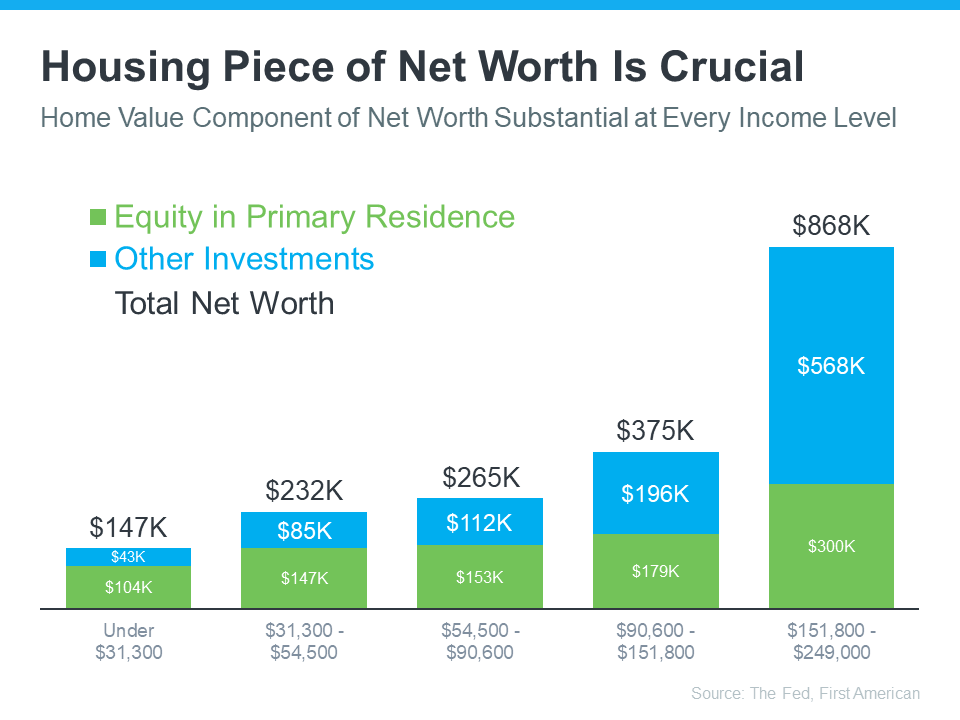
The biggest trap? Counting your primary home as an investment. It is not an investment. It’s a box you sleep in that also eats your money via property taxes and leaky faucets. A lot of people have 60% of their net worth tied up in a house, then panic when the market hiccups. That’s like betting your whole retirement on a single carnival game—sure, you might win a giant stuffed bear, but you’re also one bad throw away from crying.
Must Read
If you’re under 40, keep your primary residence’s value under 25% of your net worth. If you’re over 40, you can creep to 35%, but only because you’ve hopefully paid off some of the mortgage. Never let your house become your whole financial identity. Your house is not your child, so stop treating it like a golden goose. It’s a very expensive storage unit for your old IKEA furniture.
The Rental Property Gambit
Now, rental properties? That’s where the fun (and math gymnastics) begins. Here’s a surprising fact: the richest people in America hold about 50% of their net worth in real estate, but they’re not living in a 12-bedroom mansion. They own small multifamily units, apartment buildings, or commercial spaces. Why? Because they’re using leverage—borrowing money to buy assets that cash flow. It’s like using a giant financial pogo stick to jump over the stock market.
 What Percentage of Net Worth Should Be in Real Estate? — Delta Wealth
But for you and me, the magic number is 30% for rental properties, total. If you push past 40%, you become a "landlord who cries on weekends." I’ve seen it happen. A buddy of mine owned three duplexes and a four-plex, and he spent every Saturday unclogging toilets while his friends went paddleboarding. His net worth was high, but his soul was in a sewer.
Here’s another shocker: real estate historically appreciates about 3-5% per year, adjusted for inflation. That’s less than the S&P 500’s 10% average. But real estate offers tax breaks and forced savings—you can’t impulsively "sell a bedroom" when crypto crashes. The trade-off? Illiquidity. You can’t turn a bathroom into cash at 3 AM.
 Primary Residence Value As A Percentage Of Net Worth Guide
The "Too Much" Test
How do you know if you’ve gone overboard? Take the "Midnight Panic Test." If you wake up at 2 AM worried about a vacancy, a roof repair, or a tenant who plays the ukulele at 3 AM, you have too much real estate. The ideal amount is the maximum you can own without needing a therapist. For most humans, that’s 25–35% of net worth, including your home. For super-rich people, it’s 50%, but they also have a team of people who fix their toilets.
Consider this: Warren Buffett, one of the richest people alive, lives in a house he bought for $31,500 in 1958. He has less than 1% of his net worth in real estate. Meanwhile, some guy named "Carl from accounting" puts 90% of his savings into a timeshare in Florida. One of these people is a genius. The other owns a timeshare.
 A Homeowner’s Net Worth Is 40x Greater Than a Renter’s
The "Lazy Investor" Rule
If you don’t want to be a landlord, keep your real estate allocation under 15% via REITs or real estate ETFs. REITs let you own a slice of skyscrapers without ever meeting a plumber. You’ll sleep better, and your weekends stay free for badminton. The downside? You miss out on that sweet, sweet leverage and the tax write-offs that make wealthy people giggle.
Here’s the final punchline: the "perfect" percentage is a moving scale based on your personality. Are you handy? Can you fix a sink without crying? Then push to 40%. Do you think a "shim" is a type of hip-hop dance? Stick to 15% and buy index funds. The worst combination is owning expensive real estate you can’t afford and hating every second of it. That’s called "being house-poor and moody."
In the end, remember this golden rule: real estate is a dessert, not the entire meal. A healthy financial dinner should have stocks, bonds, cash, and maybe a side of Bitcoin-shaped Jell-O. But if you load your plate with nothing but property, you’ll end up with indigestion and a foreclosure notice. So aim for 20–30%, laugh at the people who own three houses and no retirement fund, and go enjoy that café latte. Your net worth will thank you—as long as you don’t spend it all on avocado toast.
