What Should My Net Worth Be At 30

So, you’re thirty. Or maybe you’re peeking at that milestone from a few years away. Either way, you’ve probably Googled that question: “What should my net worth be at 30?” Let...
So, you’re thirty. Or maybe you’re peeking at that milestone from a few years away. Either way, you’ve probably Googled that question: “What should my net worth be at 30?” Let’s be real—the internet is full of scary numbers and charts that make you feel like you’re already behind. But what if we took a deep breath and looked at this with a little more curiosity and a lot less panic?
First off, let’s ditch the guilt. The average net worth for a 30-year-old in the U.S. hovers around $9,000 to $20,000, depending on who you ask. That’s not a mansion or a yacht—it’s more like a decent used car or a year of saving your lunch money. Kind of cool, right? It means most of us are building our financial lives from scratch, one paycheck at a time.
But here’s the secret: net worth isn’t a final exam. It’s just a snapshot of your assets (what you own) minus your liabilities (what you owe). That student loan from art school? It counts. That beat-up couch from college? Technically, it’s worth something. The real magic is watching that number trend upward, not perfecting it at 30.
Must Read
The “Rule of Thumb” (And Why It’s Okay to Bend It)
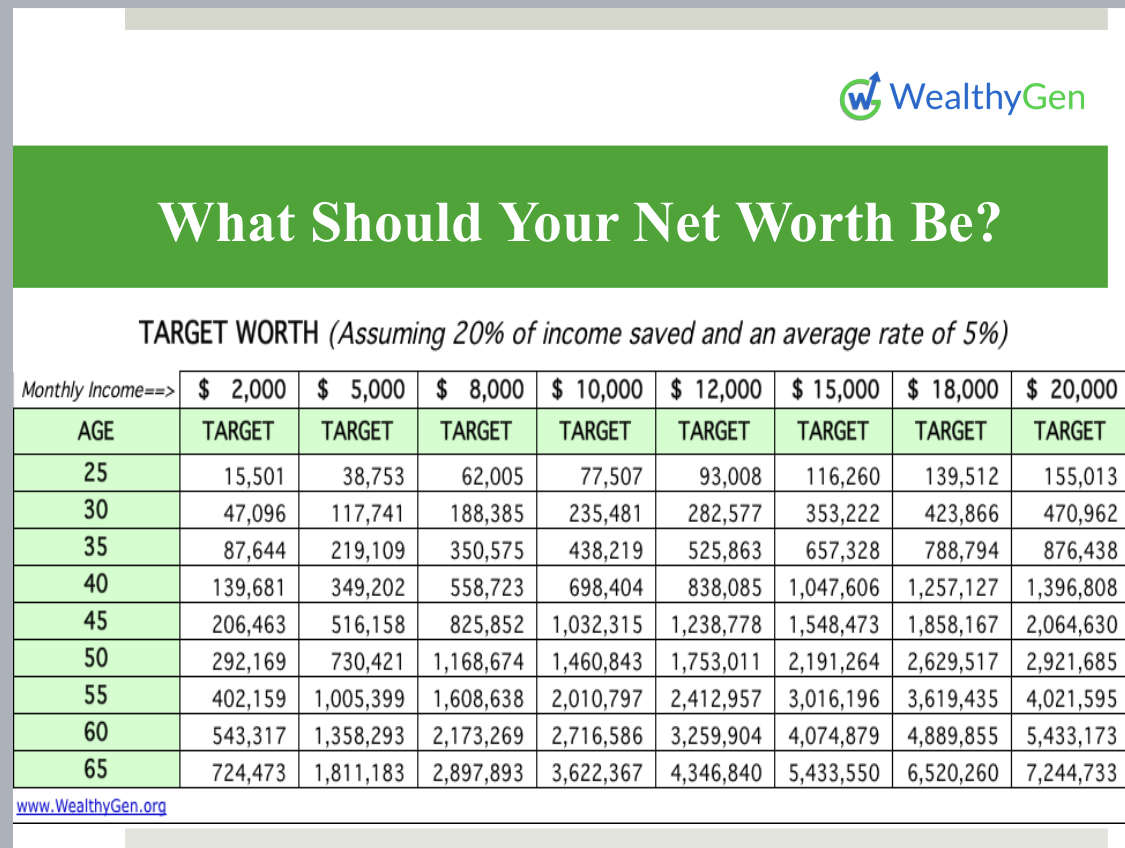
You might hear financial gurus say you should have half your annual salary saved by 30. If you make $50,000, that means $25,000 in savings and investments. Sounds impossible if you’re still renting and eating avocado toast, doesn’t it?
Here’s why that rule is more of a vibe than a hard law: it ignores your specific story. Maybe you started a business, traveled the world, or spent your twenties as a broke artist. Your net worth at 30 is a reflection of your choices, not your worth as a human. Comparison is the thief of joy, especially when you’re looking at a spreadsheet.
Instead of aiming for a magic number, try this: aim for zero bad debt. Credit card balances with 20% interest? Those are the real monsters. Paying them off is actually a better investment than any stock market gamble.
 What Should Be My Net Worth At Age 35? - Financial Samurai
What Does “Cool” Look Like at 30?
Forget the corporate ladder for a second. A “cool” net worth at 30 might look like having $10,000 in an emergency fund and a 401(k) with a few thousand bucks. That’s a safety net for when your car breaks down or you need a mental health break from your job. It’s peace of mind, not a status symbol.
Compare that to someone with $50,000 in net worth but crippling anxiety about losing it all. Suddenly, the humble saver with the old Honda Civic seems richer, doesn’t he? Lifestyle inflation is the silent killer of financial chill—the moment you buy a bigger TV just because you got a raise.
Another fun comparison: think of net worth like a video game. At 30, you’re not supposed to be at the final boss level. You’re still collecting coins, unlocking new skills, and dodging a few fireballs (hello, rent hikes). The goal is to build momentum, not to win the game overnight.
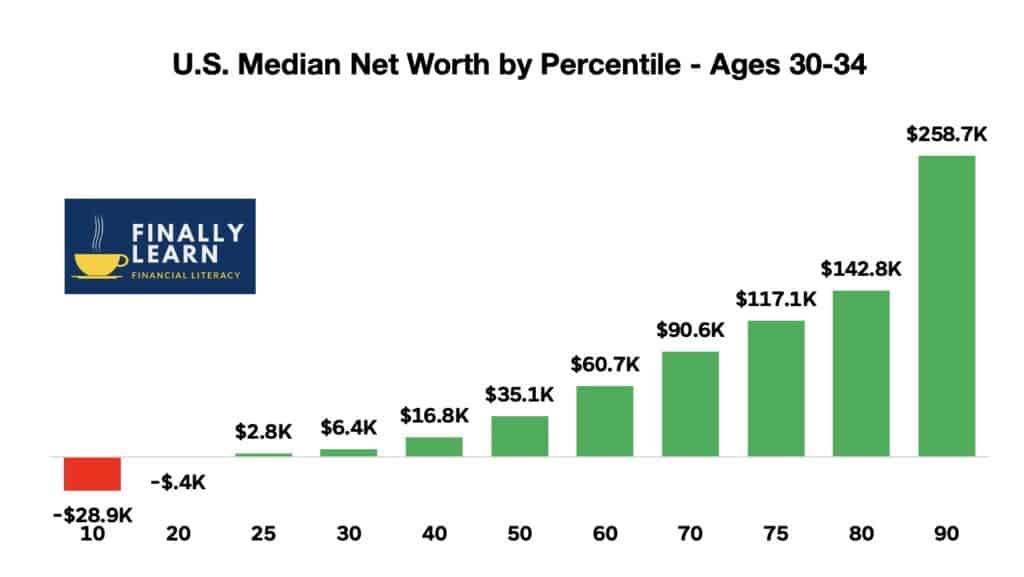 Average Net Worth by Age 40 - Finally Learn
What About That 30-Year-Old Who Owns a House?
Yeah, you’ve seen the Instagram posts: “I bought my first home at 28!” Cute, but here’s the reality check—home equity is part of net worth, but it’s not liquid cash. That person might have a net worth of $100,000, but they’re also paying mortgage, taxes, and for a new water heater. Cash flow matters more than a big number on paper.
So, if you’re 30 and renting, you’re not a failure. You’re free to move for a better job or avoid a flooded basement. Your net worth might look smaller, but your flexibility is through the roof. That’s a trade-off worth celebrating.
Here’s a wild thought: your potential is part of your net worth too. Your skills, your health, your ability to earn more in the next decade—that’s “human capital,” and it’s often worth way more than your bank account. Don’t let a number on a screen define your whole financial picture.
 What Should My Net Worth Be At Age 30, 40, 50, 60?
So, What Should You Actually Do?
Stop obsessing over a target and start building habits. Automate a small contribution to savings or investments every month—even $100 counts. If you do that from 30 to 40, you’ll have around $20,000 saved (assuming modest returns). That’s real progress without stressing over a budget spreadsheet.
Also, talk to your friends. You’ll probably find that everyone is in a similar boat—some are ahead, some are behind, but most are just figuring it out. Financial loneliness is a thing, and sharing your numbers (or not) can be surprisingly freeing.
Finally, remember that net worth at 30 is like a trailer for a movie. The best scenes are ahead of you. Focus on the story you want to tell, not the box office numbers from last weekend. You’ve got time, you’ve got curiosity, and honestly? That’s worth more than a few extra thousand bucks.
