What Should Your Net Worth Be At 40

Let’s be honest: the phrase “net worth at forty” sounds like something whispered at a dinner party with a side of avocado toast. It feels heavy, almost like a financial report...
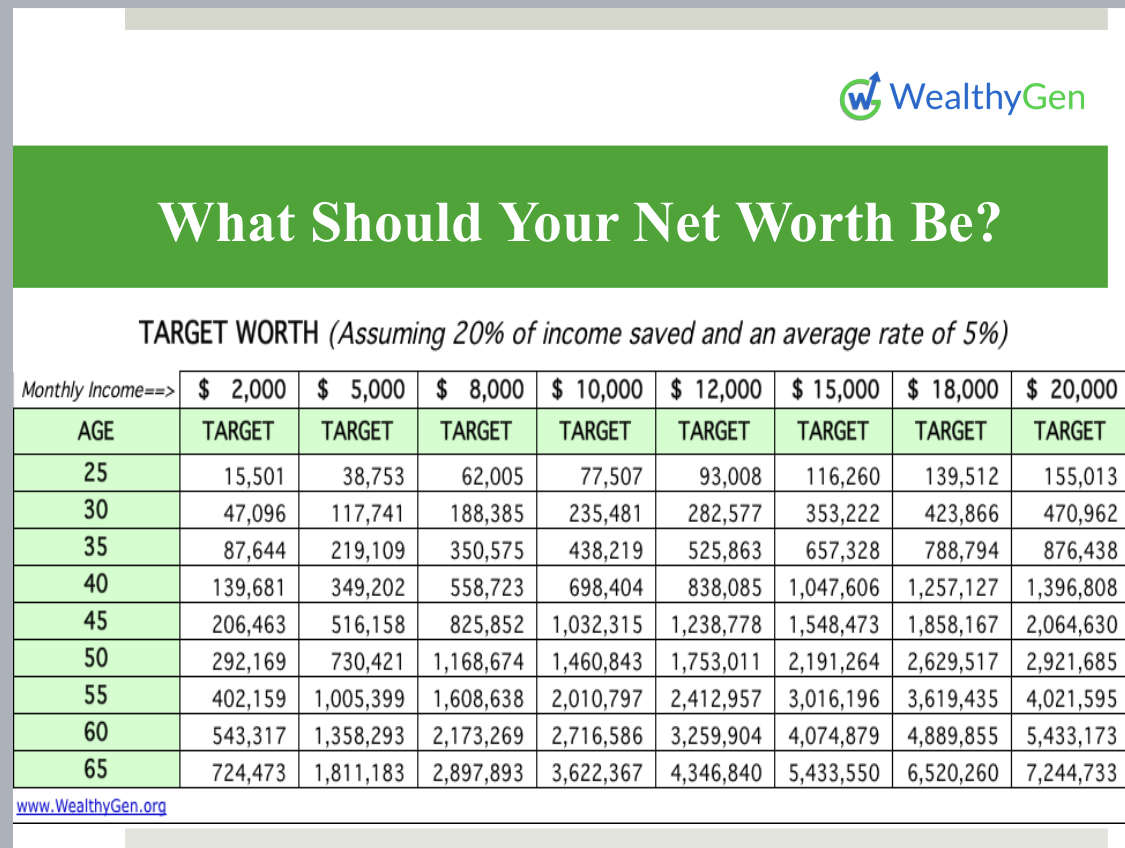
Let’s be honest: the phrase “net worth at forty” sounds like something whispered at a dinner party with a side of avocado toast. It feels heavy, almost like a financial report card you forgot to study for. But here’s the good news—this is your life, not a spreadsheet, and your forties are the sweet spot where hustle meets wisdom.
So, what should your net worth be at 40? The standard rule of thumb, whispered by financial planners and FIRE enthusiasts alike, is to have three times your annual salary saved by this age. If you earn $80,000, that means a net worth of $240,000. But don’t panic if that number feels like a distant galaxy—it’s a guide, not a judge.
The Reality Check (With a Side of Humor)
Think of your net worth as a slow-cooker recipe, not a microwave dinner. By 40, you’re probably juggling a mortgage, childcare costs, and the lingering cost of that impulse-buy espresso machine from 2021. According to the Federal Reserve, the median net worth for Americans in their 40s hovers around $135,000. That’s not a trophy—it’s a starting line.
Must Read
Fun fact: If you’ve ever watched The Office, Michael Scott’s financial advice (“I’m not superstitious, but I am a little stitious”) is exactly what not to do. Instead, channel your inner Dwight Schrute—organized, focused, and quietly building a beet-farm-sized nest egg.
What’s in the Net Worth Basket?
Your net worth isn’t just cash in a savings account. It’s a basket of assets minus liabilities: home equity, retirement accounts, investments, and even that vintage guitar you swear is a collectible. The magic number? $500,000 in total assets is a common aspirational target for 40-year-olds, but it’s not a binary pass-fail.
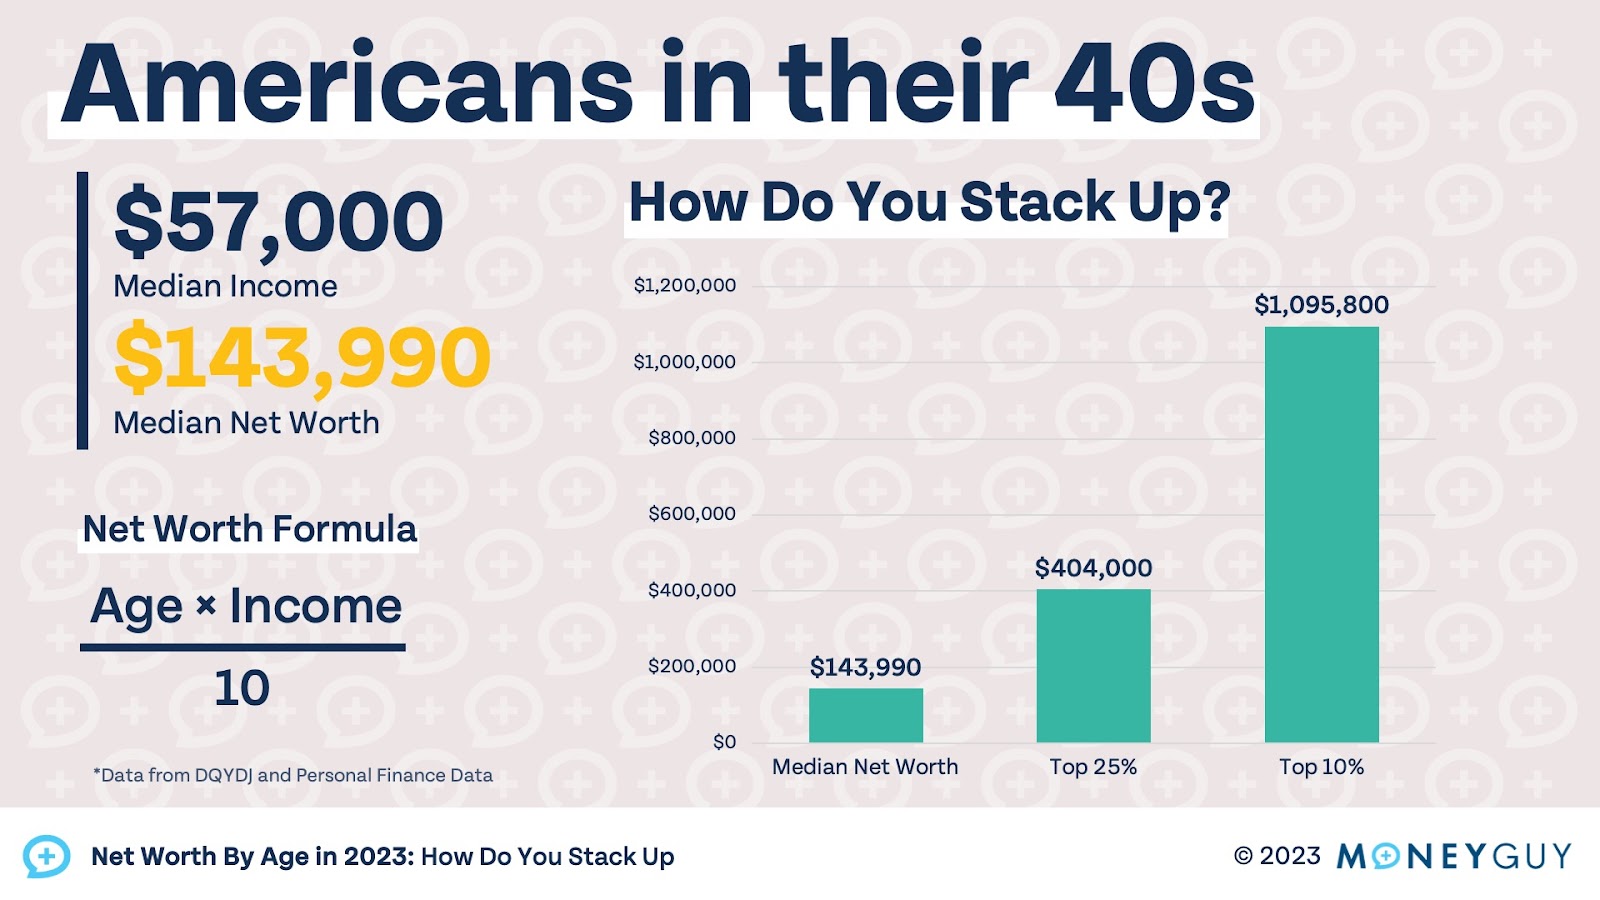 Net Worth By Age in 2023: How Do You Stack Up? | Money Guy
Cultural reference: remember Rachel Green from Friends? She went from waitress to fashion exec by 40. Your journey is yours—don’t compare your Chapter 5 to someone else’s Chapter 20. The goal is progress, not perfection.
Practical Tips to Boost Your Number (Without Quitting Your Day Job)
Start with the “Pay Yourself First” mantra. Automate 15% of your income into a 401(k) or Roth IRA before you see it. This isn’t a suggestion; it’s a cheat code. Example: if you’re 35 and invest $500 a month at a 7% return, you’ll have roughly $180,000 by 40. Compound interest is the real-life time machine.
Next, slash one dumb subscription. That forgotten Peloton app payment? Cancel it and redirect $39 to a brokerage account. Over five years, that’s nearly $2,400—enough for a mini-retirement in Bali (or a new couch). Small leaks sink big ships.
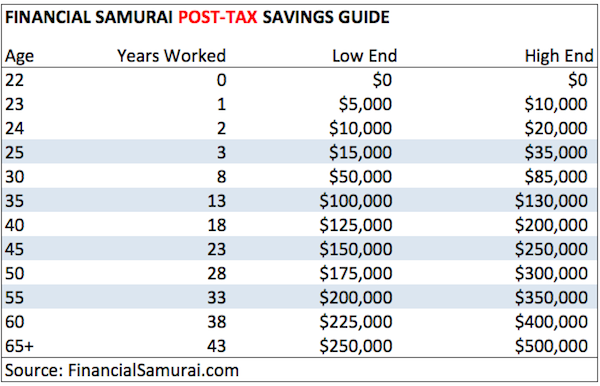 What Should My Net Worth Be At Age 30, 40, 50, 60?
Finally, talk about money with friends. Yes, it’s awkward, but it’s also how you learn. A 2022 survey found that 73% of millennials discuss salaries openly. Your buddy’s side hustle investing in crypto? Ask about it. Curiosity is the antidote to financial shame.
The “Fun Little Fact” Corner
Did you know that the word “net worth” was first used in the 14th century to describe a fisherman’s haul? True story. And today, your net worth is your personal fishing net—it catches what you’ve built, but it’s not the whole ocean. At 40, the average person has 12 years of work left before traditional retirement. That’s enough time to double your savings if you’re smart.
Another fact: Warren Buffett made 99.7% of his wealth after his 52nd birthday. So if you’re 40 and feeling behind, remember—you’re a baby in the finance world, just with better skincare and more emotional baggage.
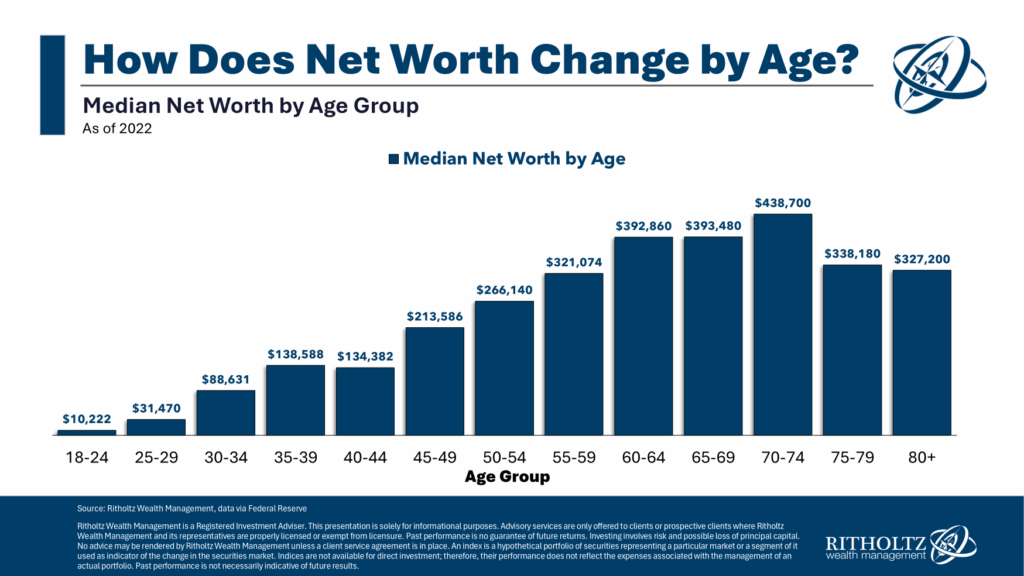 How Much Should You Have Saved by 30? 40? 50? 60? - A Wealth of Common
The Daily Life Reflection
Here’s the truth: your net worth at 40 is a snapshot, not a biography. It’s the number you write on a napkin after a good dinner, not the story you tell yourself at 3 AM. Life is lived in the in-between—in the morning coffee runs, the family movie nights, and the unexpected vet bills that remind you to be grateful for the health fund you started.
So, check your savings, yes. But also check your pulse. Are you happy? Are you learning? Are you leaving room for spontaneity? Because the best investment you can make at 40 isn’t just a bond or a stock—it’s a life you don’t need to escape from. And that, my friend, is worth every penny.
Now go enjoy that overpriced oat latte. You’ve earned it.
