Why Bond Companies Require Net Worth

Let’s be honest: when you hear the phrase “bond companies require net worth,” your eyes might glaze over. It sounds like something a stuffy accountant mutters while sipping ba...

Let’s be honest: when you hear the phrase “bond companies require net worth,” your eyes might glaze over. It sounds like something a stuffy accountant mutters while sipping bad coffee. But stick with me—this is actually a story about trust, neighborly kindness, and why your cousin’s fancy car matters more than you think.
Think of it like borrowing a lawnmower
Imagine your neighbor knocks on your door and asks to borrow your shiny new lawnmower. You’d probably want to know: Do they have a yard? More importantly, can they replace it if they break it?
Now, picture that you’re a bond company, and the neighbor is a construction contractor. That contractor needs a bond—basically a financial promise—before they can build your local playground or fix the town’s broken water main.
Must Read
If the contractor messes up, the bond company has to pay the damages. So, like you with your lawnmower, the bond company asks: “Do you have enough money to cover your mistakes?” That’s the net worth requirement in a nutshell.
Net worth isn’t just a number—it’s a safety net
Your net worth is everything you own (cash, house, car) minus everything you owe (bills, loans, credit cards). For a bond company, a high net worth says: “This person has skin in the game.” It means they’re less likely to run off or go bankrupt if something goes wrong.
Think about your friend who always pays for dinner. You trust them to split a pizza because they have enough cash to cover their half. Same logic: a contractor with a solid net worth shows they can weather a storm—financial or literal.
Without that requirement, bond companies would be handing out promises like candy. And if something broke, you—the taxpayer or homeowner—could be left holding the bill. That’s why they care.
 Chart of the Day: Banks have relied on bonds to meet credit demand
A little story: the baker and the wedding cake
Let’s say you hire a baker to make your wedding cake. You pay a deposit. The baker then buys flour, eggs, and a tiny sugar figurine of your dog. But what if the baker’s oven explodes the day before the wedding?
If the baker has savings (a net worth), they can refund your deposit and maybe even bake a new cake at another shop. If they’re broke, you’re stuck with a sad grocery-store sheet cake and a ruined Instagram photo.
Bond companies feel the same anxiety—only the stakes are bridges and hospitals, not wedding cakes. Net worth is the baker’s backup oven. It’s proof that they can handle a meltdown.
Why you should care (yes, you!)
You probably aren’t a contractor or a bond agent. But every time you hire someone to fix your roof, pave your driveway, or paint your living room, you’re making a tiny bet on their reliability. A company that can get a bond has been vetted—they have the net worth to prove they’re serious.
 Are bonds worth investing in? | The Week
It’s like dating. You wouldn’t date someone who says, “I promise I’ll call,” but has no phone. You want proof they can keep their word. Net worth is that proof for businesses.
And when a bond company requires net worth, it protects you from dodgy operators. It filters out the fly-by-night guys who might take your money and disappear into thin air.
Okay, but what’s a “good” net worth?
There’s no magic number, but bond companies usually look for liquid assets—cash or things easily turned into cash. They want to see that you can handle a sudden expense of tens or hundreds of thousands of dollars.
Think of it like an emergency fund for a business. If your personal emergency fund is three months of expenses, a contractor’s emergency fund (net worth) should cover a botched project. It’s the same principle, just bigger numbers.
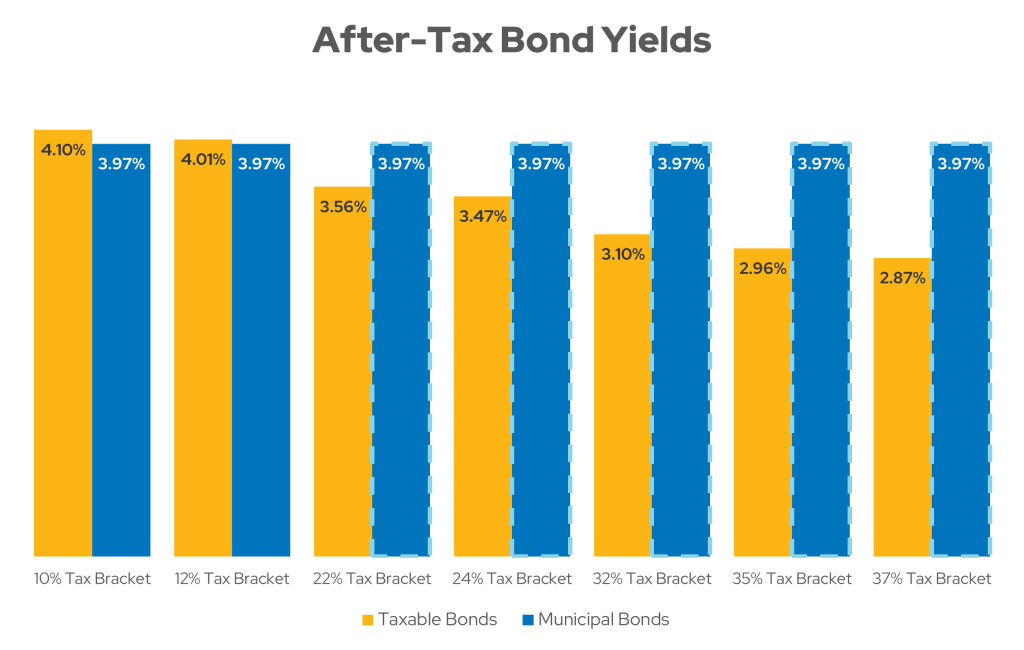 How municipal bonds fit into today’s high-net-worth portfolios | Envestnet
Some contractors grumble about this requirement. But the smart ones know it’s a badge of honor. It says: “I’m solid. I can be trusted.” And that trust is why you can sleep at night knowing your new deck won’t collapse.
The warm and fuzzy conclusion
At its heart, requiring net worth is about being a good neighbor. It’s about looking out for the little guy—you, me, the family who just bought their first fixer-upper. Bond companies aren’t trying to be mean; they’re trying to keep promises.
So next time you hear “net worth,” don’t picture a cold spreadsheet. Picture your neighbor’s lawnmower, your wedding cake, and the peace of mind that comes from knowing someone has your back. It’s just common sense, wrapped in a financial hug.
And that, my friend, is why bond companies ask. Now go forth, hire a bonded contractor, and enjoy that sturdy deck—with a slice of cake, if you’re lucky.
