Why Bond Companies Require Net Worth Information

Imagine you’re applying for your first surety bond—maybe for a contractor’s license or a small business permit—and the company suddenly asks for your net worth. It feels a bit...

Imagine you’re applying for your first surety bond—maybe for a contractor’s license or a small business permit—and the company suddenly asks for your net worth. It feels a bit like a first date asking for your bank balance, right? But trust me, this isn’t nosiness; it’s just smart business math dressed in a suit.
The bond company isn’t trying to peek into your savings jar for fun. They’re essentially acting like a high-stakes guarantor for your promises to clients or the government. If you screw up on a project, they pay the claim—and they need to know you can reimburse them later.
Think Before You Indemnify
When you sign a bond application, you’re signing an indemnity agreement. That’s a fancy way of saying, “If the bond company pays a claim, I’ll pay them back, plus legal fees and interest.” Without your net worth info, they’re basically handing you a financial safety net blindfolded.
Must Read
Your net worth is their crystal ball for how easily you can cover a potential loss. It’s not personal—it’s about risk tiers. A high net worth often means lower premiums, while a low one might require collateral or a co-signer.
Fun fact: Net worth isn’t just what you own minus what you owe; it’s your financial story in a single number. Bond companies use it to see if you have enough liquid assets (cash, stocks, property equity) to survive a claim without bankruptcy.
The “Rich Uncle” Logic
Think of the bond company as your cool but cautious rich uncle. An uncle might lend you his vintage car, but only after checking if you’ve got a job and savings to cover a fender bender. Here, the bond is the car, and your net worth is the assurance you won’t ghost him after an accident.
This isn’t just for giant corporations. Even a small electrician needing a $10,000 bond will face the same question. The bond company wants a safety cushion between them and your bad luck—or bad decisions.
 Do bond fund investors need to change their strategy after Budget?
Cultural reference: It’s a bit like the “proof of means” scene in The Great Gatsby—everyone wants to know if you can actually pay for the party before they let you into the VIP room. Except here, the party is a construction project, and the VIP room is a state license.
Credit vs. Net Worth: They’re Not Twins
You might wonder: “Why not just check my credit score?” Credit scores track how you handle debt over time, but net worth captures your total financial firepower. A score can be high while your savings are empty—think of someone with maxed-out cards but perfect payments.
Net worth paints the full landscape: maybe you own a paid-off truck worth $60,000 and have $30,000 in the bank. Even with average credit, that’s a strong net worth. Bond companies love that picture because it shows you have skin in the game beyond a FICO number.
Practical tip: Don’t guess your net worth. Use a simple spreadsheet or an app like Mint to list assets (cash, real estate, investments) and liabilities (mortgage, loans, credit card debt). Being accurate here can save you thousands in bond premiums over time.
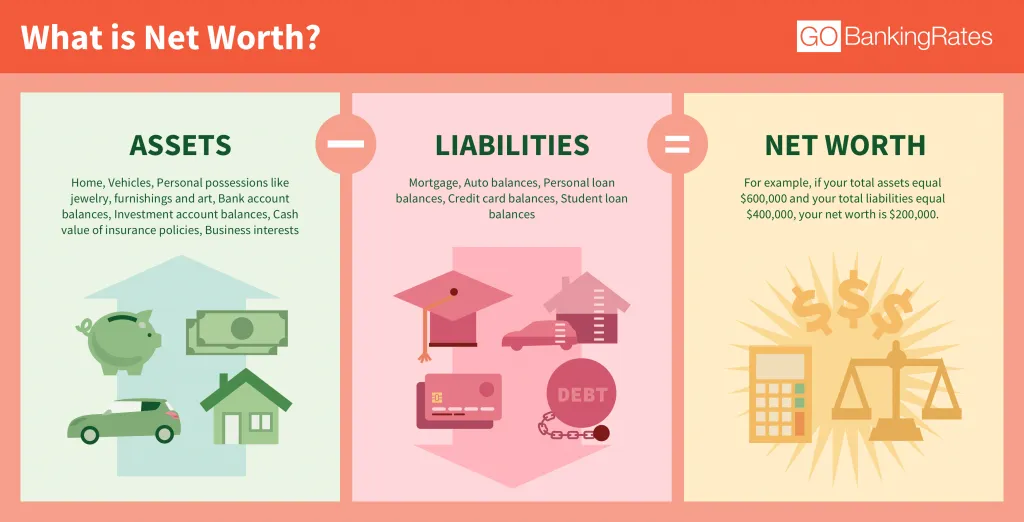 Business Net Worth
When Your Net Worth Says “No”
What if you’re a young freelancer with stellar skills but zero savings? Bond companies won’t immediately reject you. They might ask for collateral—like a certificate of deposit or a letter of credit from your bank—as a substitute for net worth.
Another workaround: include a co-indemnitor with a stronger net worth, like a business partner or parent. It’s like adding a cosigner to a lease, but way less awkward if you frame it as a professional alliance.
Fun little fact: In the UK, bond companies call this “financial standing evidence,” and they often request three years of tax returns instead of a single net worth number. Cultural differences aside, the core question is the same: Can you actually back up your promise?
The Value of Being Transparent
Hiding or inflating your net worth is a terrible idea. Bond companies have underwriters who are human lie detectors—they cross-check your numbers with tax returns, bank statements, and public records. Get caught fibbing, and you’ll lose their trust forever.
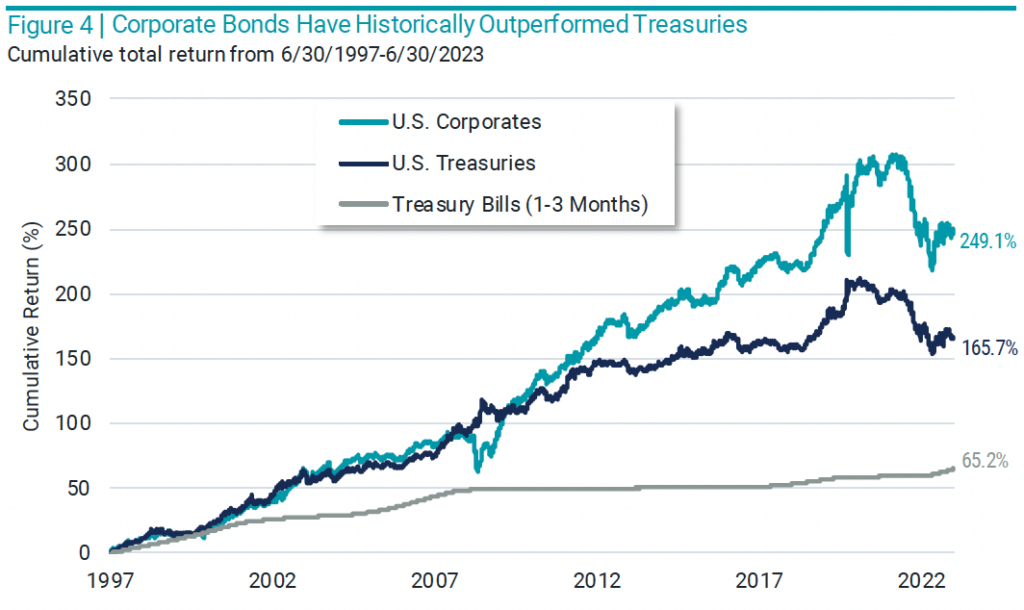 Then and Now: An Update on Today's Bond Market | Arcadia Wealth
Instead, view this as a moment of financial honesty. Even if your net worth is modest, showing accurate info can build a track record. Over time, as your assets grow, your bond premiums shrink, and your reputation as a reliable professional shines.
Modern life hack: Use a cloud-based financial dashboard to keep your asset and liability data updated quarterly. That way, when a bond company asks, you’re ready with a neat number and a “Here’s the breakdown” email—no scrambling.
Reflection: This Is a Mirror, Not a Test
So, why do bond companies require net worth? They’re not gatekeeping—they’re protecting their own ability to keep issuing bonds for everyone. It’s the same reason your car insurer asks about your driving record: fairness through shared risk assessment.
Next time someone asks for your net worth, take a deep breath. It’s not an invasion; it’s an invitation to show your professional stability. And honestly, knowing your own net worth is a life skill we all should practice—for bonds, for mortgages, or just for that quiet Sunday morning when you want to feel like a grown-up.
In daily life, we rarely calculate our full financial picture until someone forces us to. That bond application might just be the push you need to realize you’re worth more than you think—or a gentle nudge to start building that net worth one saved dollar at a time.
