Can You Get A Mortgage When On Benefits

Let's face it, getting a mortgage can be like trying to solve a puzzle blindfolded while being attacked by a swarm of bees - it's daunting, to say the least. But, what if you'...
Let's face it, getting a mortgage can be like trying to solve a puzzle blindfolded while being attacked by a swarm of bees - it's daunting, to say the least. But, what if you're on benefits? Does that mean your dream of owning a home is doomed from the start? Not necessarily, as we'll explore in this article.
Understanding the Landscape
Being on benefits doesn't automatically disqualify you from getting a mortgage, but it does make things more complicated. It's like trying to cook a recipe with missing ingredients - you can still make something edible, but it's not going to be the culinary masterpiece you envisioned. Lenders view benefits as an unstable income source, which can make them wary of approving a mortgage application.
In the UK, for instance, there are various types of benefits, such as Income Support, Employment and Support Allowance (ESA), and Universal Credit. Each has its own set of rules and regulations, which can impact your mortgage eligibility. It's essential to understand which benefits you're receiving and how they might affect your application.
Must Read
The lenders' perspective
Lenders are like the gatekeepers of credit - they need to ensure that you can repay the mortgage before approving your application. When you're on benefits, lenders may view your income as unreliable or variable, making it harder to predict your ability to make monthly repayments. This doesn't mean they won't consider your application, but you'll likely face stricter criteria and tougher affordability tests.
Some lenders specialize in mortgages for people on benefits, offering more flexible eligibility criteria. These lenders might consider your overall financial situation, including other income sources, debts, and credit history. However, be prepared for higher interest rates and stricter repayment terms to compensate for the perceived increased risk.
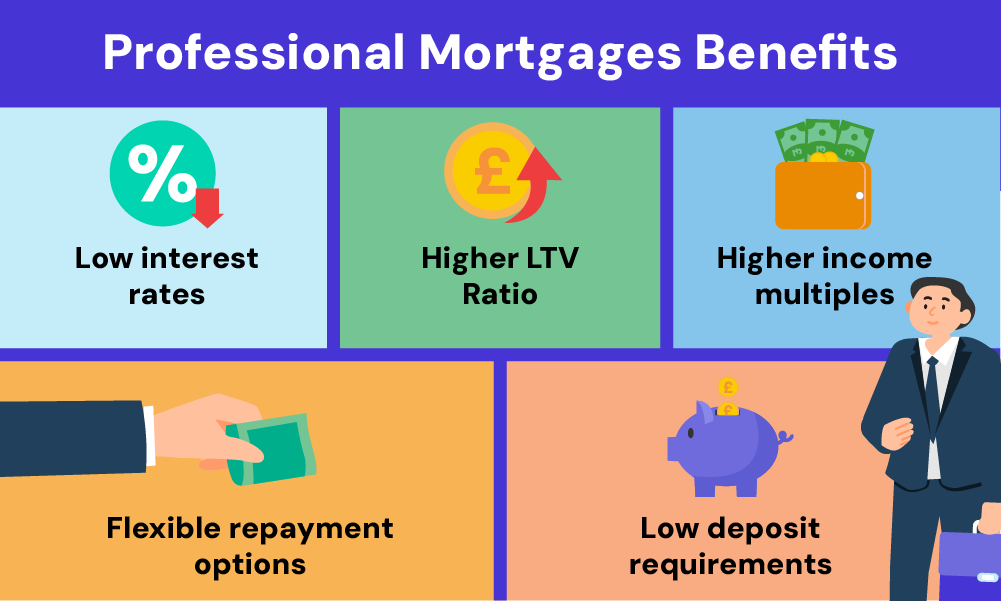 A Complete Guide to Mortgages for Professionals
Improving Your Chances
If you're on benefits and want to get a mortgage, there are ways to boost your chances of approval. For starters, improve your credit score by paying off debts, making timely payments, and reducing your credit utilization. This demonstrates to lenders that you're responsible with credit and can manage your finances effectively.
Having a stable income alongside your benefits can also help. This could be from a part-time job, freelance work, or other sources. Lenders like to see a diversified income stream, as it reduces their risk and increases your chances of securing a mortgage. Additionally, save for a larger deposit - this will not only reduce your loan-to-value ratio but also show lenders that you're committed to owning a home.
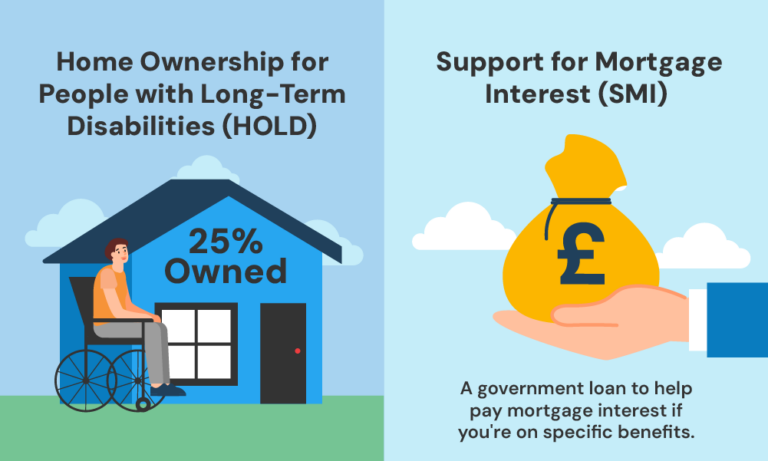 Getting Mortgages For Disabled On Benefits In The UK
Seeking Professional Help
Getting a mortgage while on benefits can be a complex process, and it's easy to get bogged down in paperwork, jargon, and rejection. This is where a mortgage broker or financial advisor can be a lifesaver. They'll help you navigate the system, find suitable lenders, and increase your chances of approval.
A good broker will understand the benefits system and know which lenders are more likely to accept benefit recipients. They'll also help you assemble a strong application package, including all the necessary documentation and a solid credit history. Don't be afraid to shop around for a broker who understands your situation and has experience in this area.
In conclusion, getting a mortgage while on benefits is definitely possible, but it requires patience, persistence, and the right guidance. By understanding the lenders' perspective, improving your credit score, and seeking professional help, you can increase your chances of securing a mortgage and make your dream of homeownership a reality. So, don't give up - with the right approach, you can find a mortgage that fits your needs and start building a brighter financial future.
