Is It Better To Overpay Mortgage Or Reduce Term

So, you've got a mortgage, and you're wondering what to do with it - overpay or reduce the term? Well, grab a cup of coffee, get comfy, and let's dive into it. It's a big deci...
So, you've got a mortgage, and you're wondering what to do with it - overpay or reduce the term? Well, grab a cup of coffee, get comfy, and let's dive into it. It's a big decision, but don't worry, we'll break it down in a way that's easy to understand.
First off, let's talk about overpaying your mortgage. Sounds crazy, right? I mean, who wants to give their bank more money than they have to? But hear me out - overpaying can actually save you money in the long run by reducing the amount of interest you pay over the life of the loan.
The Overpayment Option
So, how does it work? Well, when you overpay, you're essentially paying off the principal amount of your mortgage faster. This means you'll pay less interest overall, which can save you thousands - yes, thousands! - of dollars. It's like getting a discount on your mortgage, and who doesn't love a good discount?
Must Read
But, on the other hand, you could use that extra money to reduce the term of your mortgage. This means you'll be debt-free sooner, which is a pretty great feeling. I mean, who wouldn't want to own their home outright and never have to worry about mortgage payments again? It's like being on top of the world, right?
The Term Reduction Option
So, what's the best approach? Well, it really depends on your financial goals and priorities. If you want to save money on interest, overpaying might be the way to go. But if you want to be debt-free ASAP, reducing the term could be the better choice. It's all about what you want to achieve, and when.
Now, let's talk about the pros and cons of each option. Overpaying can be a bit of a gamble, since you're essentially locking your money into your mortgage. But reducing the term can be pretty rigid - if you need to access that money later, you might be out of luck. So, it's all about weighing your options and considering what might happen in the future.
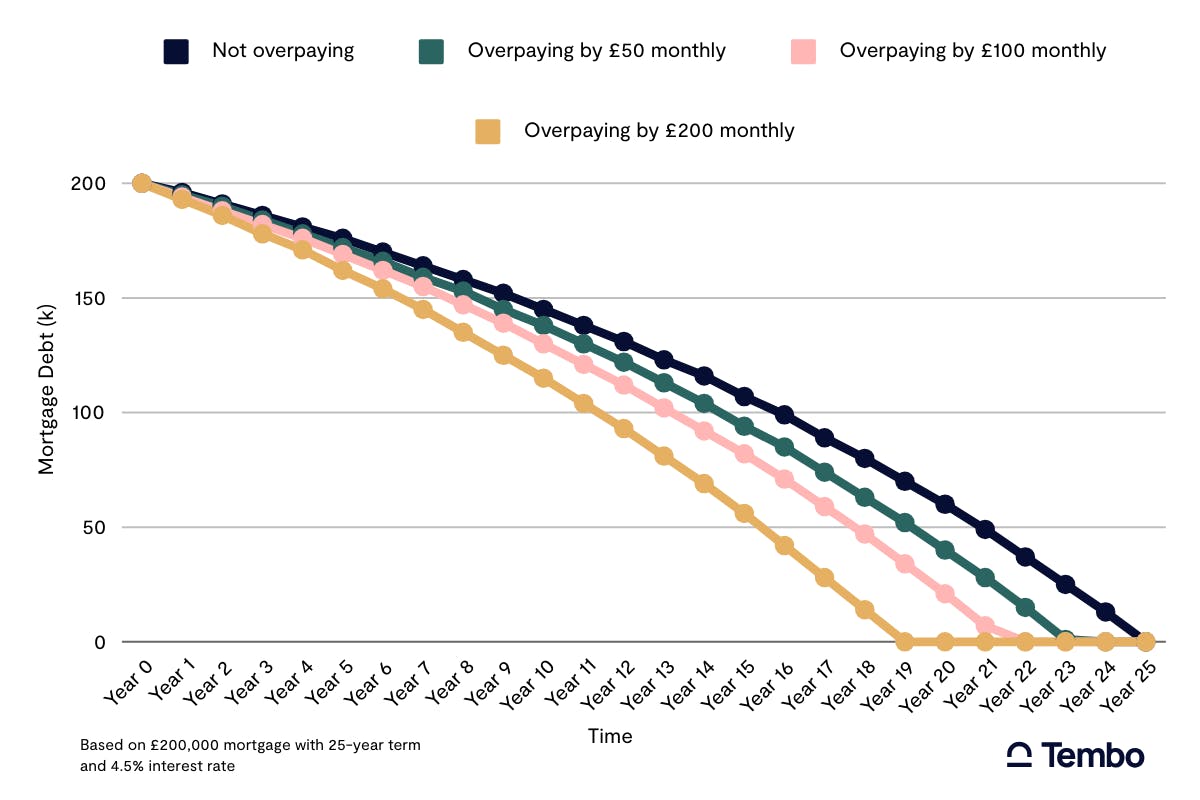 Should I Overpay My Mortgage? Must-Read Guide
Of course, there are also some other factors to consider. Like, what's the interest rate on your mortgage? If it's pretty low, overpaying might not make as much sense. And what about other debts you might have - like credit cards or personal loans? You might want to prioritize those before worrying about your mortgage.
Considering Your Options
So, what's the verdict? Should you overpay or reduce the term? Honestly, it's not a one-size-fits-all answer. You need to consider your individual circumstances and financial situation. Maybe you'll decide to do a bit of both - overpay a little and reduce the term a little. It's all about finding the right balance for you.
And don't even get me started on the psychological benefits of each option. Like, paying off your mortgage early can be a huge stress-reliever. But overpaying can also give you a sense of control and security. So, it's not just about the numbers - it's about how you feel, too.
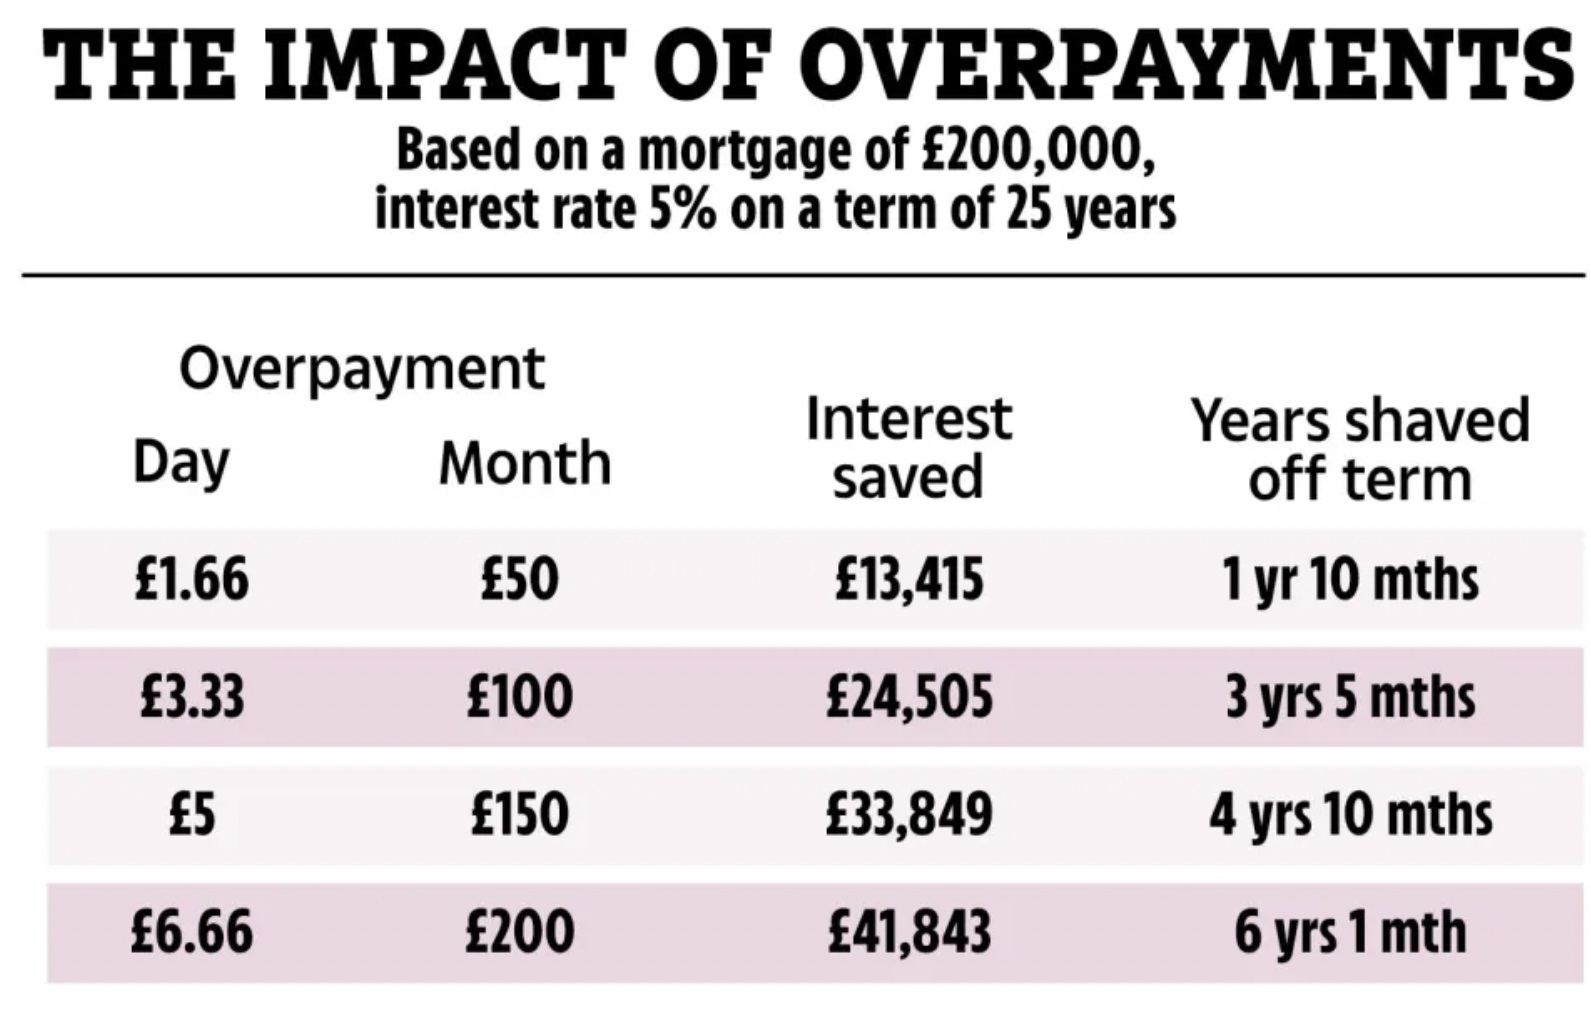 Is It Worth Overpaying Mortgage: Pros & Cons
In the end, it's all about what works best for you and your financial goals. So, take your time, do your research, and don't be afraid to seek advice from a professional. And remember, it's okay to make mistakes - it's all part of the learning process, right?
Making a Decision
So, what are you waiting for? Grab a calculator, pour yourself another cup of coffee, and start crunching some numbers. Consider your options, weigh the pros and cons, and make a decision that's right for you. And hey, if you're still unsure, just remember that it's okay to ask for help - that's what friends (and financial advisors) are for!
And finally, don't forget to review and adjust your plan regularly. Your financial situation might change, and your goals might shift. So, stay flexible, stay informed, and keep on track. You got this!
In conclusion, it's not necessarily a question of whether it's better to overpay or reduce the term - it's about finding the right approach for you and your unique circumstances. So, go ahead, take control of your mortgage, and make a plan that works for you. Happy planning, and cheers to being mortgage-free (or at least, on your way there)!
