Stamp Duty On Second Holiday Home

As the saying goes, "a house is not a home" – but what if you're lucky enough to have not one, but two homes to call your own? For those who have invested in a second holiday...

As the saying goes, "a house is not a home" – but what if you're lucky enough to have not one, but two homes to call your own? For those who have invested in a second holiday home, the process can be a thrilling adventure, but also a complex one, especially when it comes to stamp duty. In this article, we'll delve into the world of stamp duty on second homes, and explore the ins and outs of this often-misunderstood tax.
What is Stamp Duty?
For the uninitiated, stamp duty is a type of tax that's levied on the purchase of a property, and it's typically paid by the buyer. The amount of stamp duty you'll need to pay varies depending on the location and value of the property, as well as the specific stamp duty rates in place at the time of purchase. In the UK, for example, stamp duty rates range from 0% to 12% of the property's purchase price.
In the context of a second holiday home, stamp duty can be a significant expense, especially if you're buying a high-value property. However, there are some exemptions and reliefs available, which can help reduce the amount of stamp duty you'll need to pay. For instance, if you're buying a property in a rural area, you may be eligible for a rural exemption or relief.
Must Read
How Much is Stamp Duty on a Second Home?
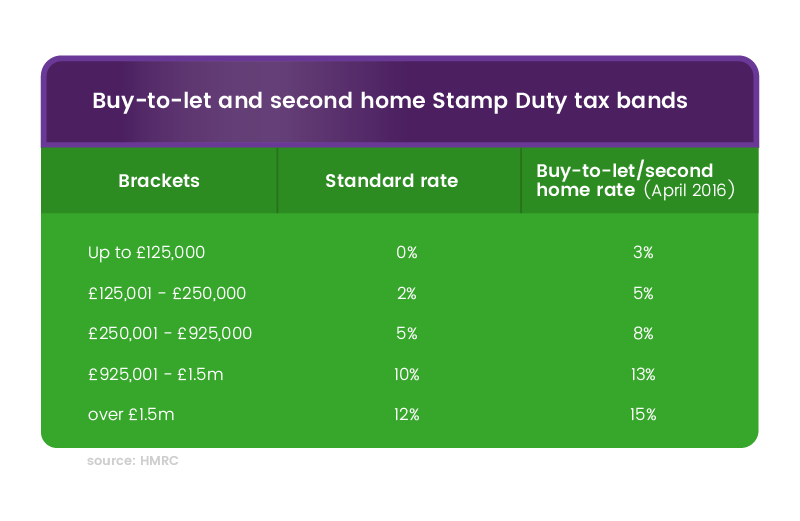
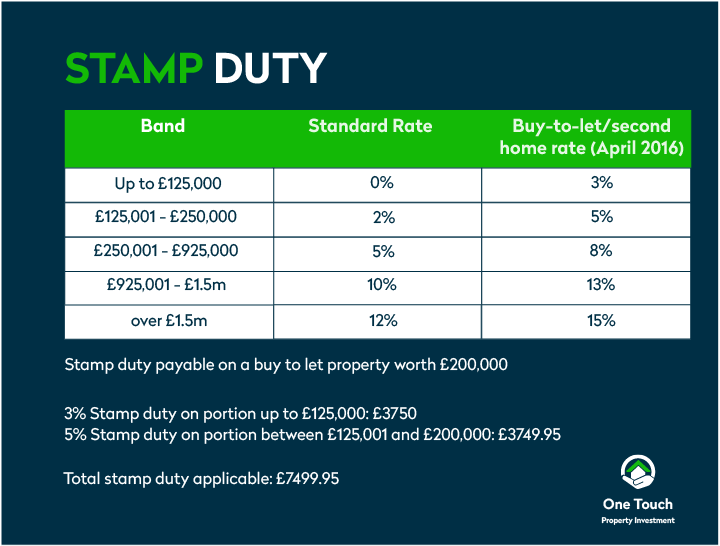
The amount of stamp duty you'll need to pay on a second home will depend on the purchase price of the property, as well as the specific stamp duty rates in place at the time of purchase. In general, you can expect to pay a higher rate of stamp duty on a second home, compared to a primary residence. For example, in the UK, the stamp duty surcharge for second homes is 3% above the standard rate.
To give you a better idea, let's consider an example: if you're buying a second home worth £500,000, you might need to pay £15,000 in stamp duty, assuming a 3% surcharge. However, this amount can vary depending on the specific circumstances of the purchase, so it's always a good idea to consult with a tax expert or financial advisor to get a more accurate estimate.
 How to Buy a Second Home: Your Key Questions Answered
Tips and Tricks for Reducing Stamp Duty
While stamp duty can be a significant expense, there are some tips and tricks you can use to reduce the amount you'll need to pay. For instance, if you're buying a second home in a joint ownership arrangement, you may be able to split the stamp duty bill with your co-owner. Alternatively, you could consider restructuring your finances to minimize your tax liabilities.
Another option is to delay your purchase until a more favorable stamp duty regime is in place. For example, some governments offer stamp duty holidays or reductions for certain types of properties, such as new builds or eco-friendly homes. By doing your research and timing your purchase carefully, you may be able to save thousands of pounds in stamp duty.
Cultural References and Fun Facts
Stamp duty may not be the most glamorous topic, but it has a rich history that dates back to the 17th century. In fact, the first stamp duty was introduced in the UK in 1694, as a way to raise revenue for the government. Today, stamp duty is an important source of income for governments around the world, and it's a key consideration for anyone buying or selling a property.
 Buy to let tax guide | Buy to let tax guide for landlords
On a more lighthearted note, did you know that the stamp duty on a second home can be higher than the average annual salary in some countries? It's a sobering thought, but it highlights the importance of planning ahead and budgeting carefully when it comes to buying a second home. Whether you're a seasoned investor or a first-time buyer, it's essential to do your research and seek professional advice to ensure you're making the most of your money.
Reflection and Conclusion
As we've seen, stamp duty on a second holiday home can be a complex and often confusing topic. However, by educating yourself and seeking professional advice, you can navigate the process with confidence and make the most of your investment. Whether you're looking to escape the city or retire in style, a second holiday home can be a wonderful addition to your lifestyle – and with the right planning, you can enjoy it without breaking the bank.
In the end, it's all about finding the right balance between your financial goals and your personal aspirations. By being mindful of your spending and planning for the future, you can create a lifestyle that's truly unforgettable. So why not start exploring your options today, and see where your second holiday home takes you? The world is full of possibilities, and with the right attitude and expertise, you can make your dreams a reality.
