Comprehensive Insurance Driving Other Cars
Few things beat the simple joy of borrowing a friend’s car for a weekend errand or hopping behind the wheel of a rental on a spontaneous road trip. The topic of comprehensive...
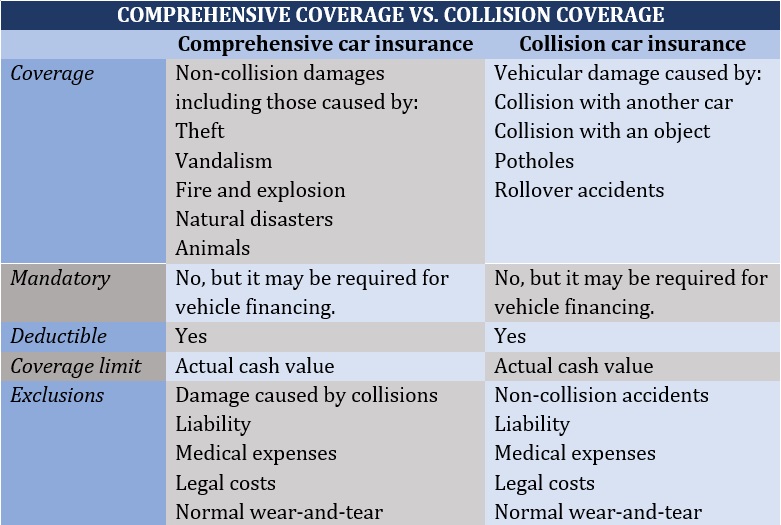
Few things beat the simple joy of borrowing a friend’s car for a weekend errand or hopping behind the wheel of a rental on a spontaneous road trip. The topic of comprehensive insurance driving other cars is a practical delight because it turns a confusing “what if” into a smooth, confident “go for it.” Its main purpose is straightforward: if you already have comprehensive cover on your own vehicle, many policies—especially in the UK and Australia—extend that same level of fire, theft, and accidental damage protection to a car you don’t own, provided you have the owner’s permission. This benefit is a game-changer for occasional drivers, renters, and anyone who values freedom without the headache of buying separate short-term policies.
The real charm lies in who it helps. Imagine a student temporarily driving a parent’s larger car for moving day, or a freelancer borrowing a neighbor’s van to pick up supplies. For these folks, the cover means peace of mind without extra paperwork. Even frequent travelers appreciate it: you can rent a car and, instead of paying for the rental agency’s pricey collision damage waiver, rely on your own comprehensive back-up. It’s a quiet hero that saves time, money, and stress.
You might recognize a common variation: in some countries, this cover is called “driving other cars” (DOC) and is often included as a standard perk—but only for cars not owned by you or your insurer. Another variation is the “any car” extension, though this is rarer and usually limited to third-party cover (damage to other people’s cars) rather than comprehensive. The key is to always check your policy wording, because the scope can differ wildly between insurers.
Must Read
To make the most of it, start with a simple tip: call your insurer or read your policy’s fine print to confirm exactly what’s covered. Ask if it includes damage to the borrowed car itself, and whether it applies to rentals. Next, never assume it covers commercial use or vans larger than a standard car—these are frequent exceptions. Finally, always carry proof of your own policy when driving another car, as you might need it during a claim.
A pro move is to spread the word among friends and family. Many people pay for extra coverage unnecessarily because they don’t realize their own policy already has their back. Share this knowledge, and you’ll not only make yourself a hero at the next dinner party but also help others drive with confidence on their next borrowed journey. After all, comprehensive cover for other cars isn’t just a fine print detail—it’s a ticket to worry-free flexibility.