Compulsory Excess Insurance
For many, insurance feels like a grudge purchase—a necessary drain on the wallet. But compulsory excess insurance offers a surprisingly welcome twist: it transforms a predicta...
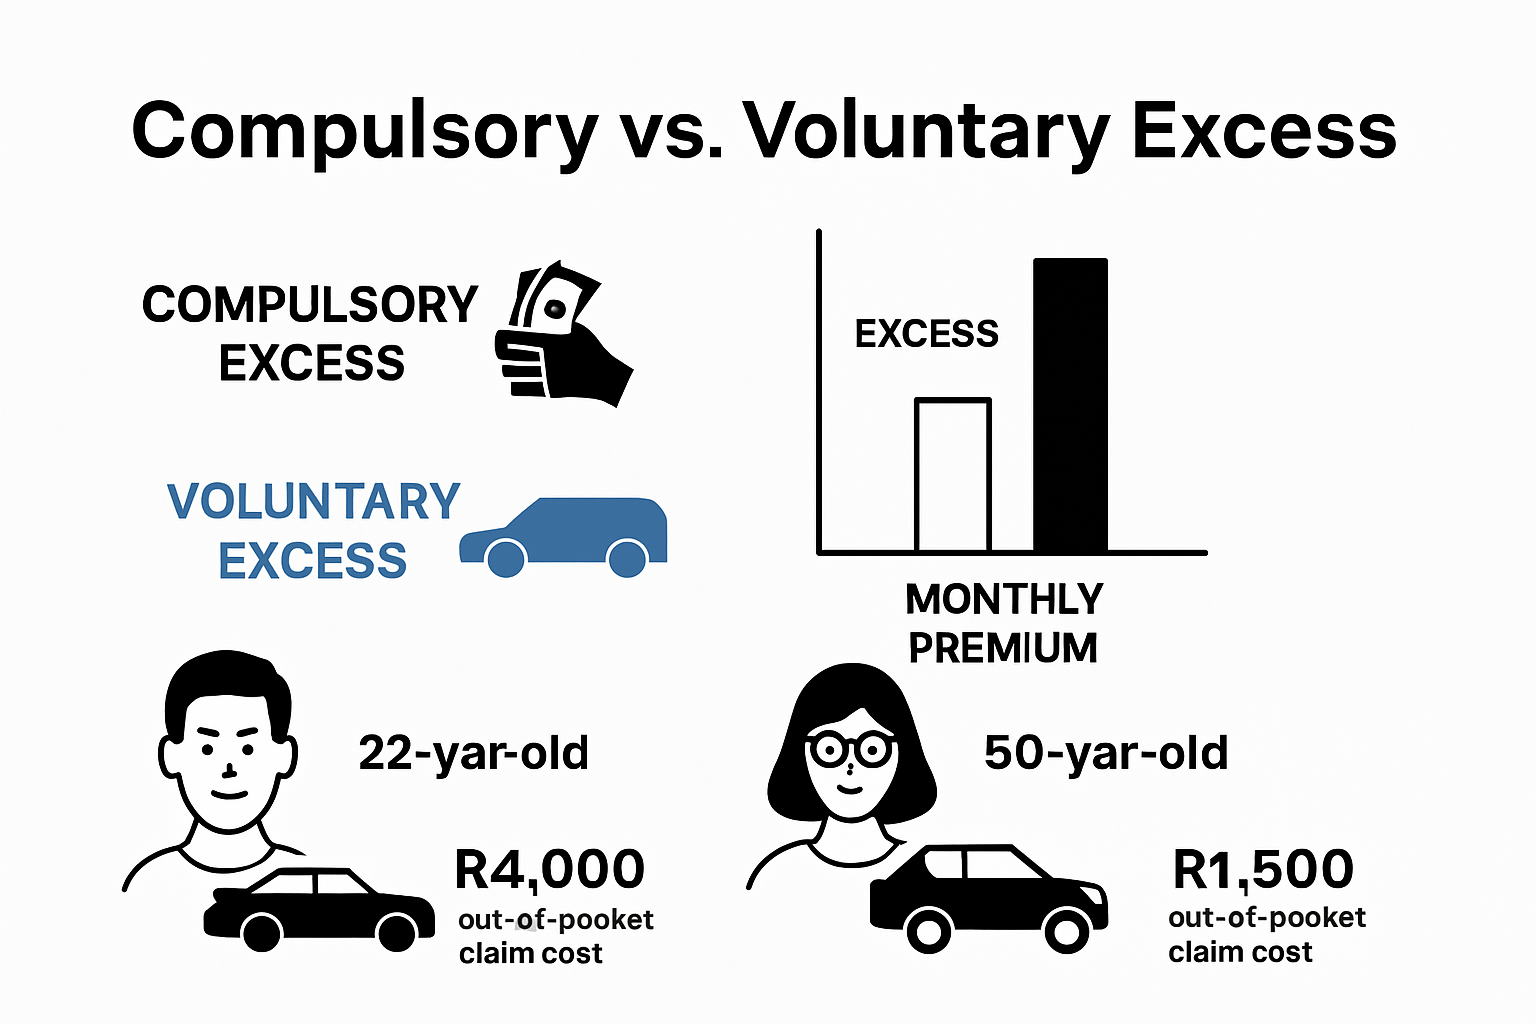
For many, insurance feels like a grudge purchase—a necessary drain on the wallet. But compulsory excess insurance offers a surprisingly welcome twist: it transforms a predictable frustration into a predictable saving. By agreeing to pay a fixed, upfront amount towards a claim, policyholders enjoy significantly lower premiums, turning a potential financial headache into a manageable, budget-friendly choice.
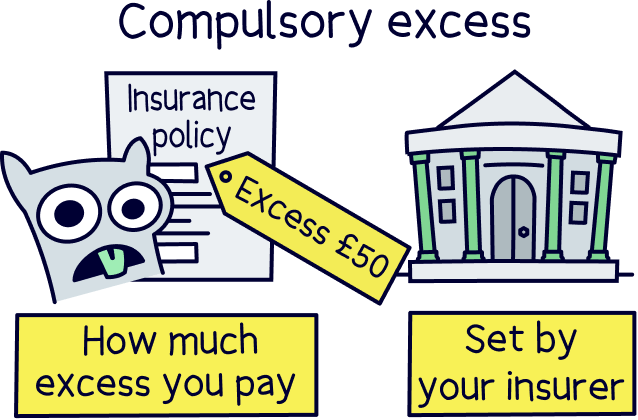
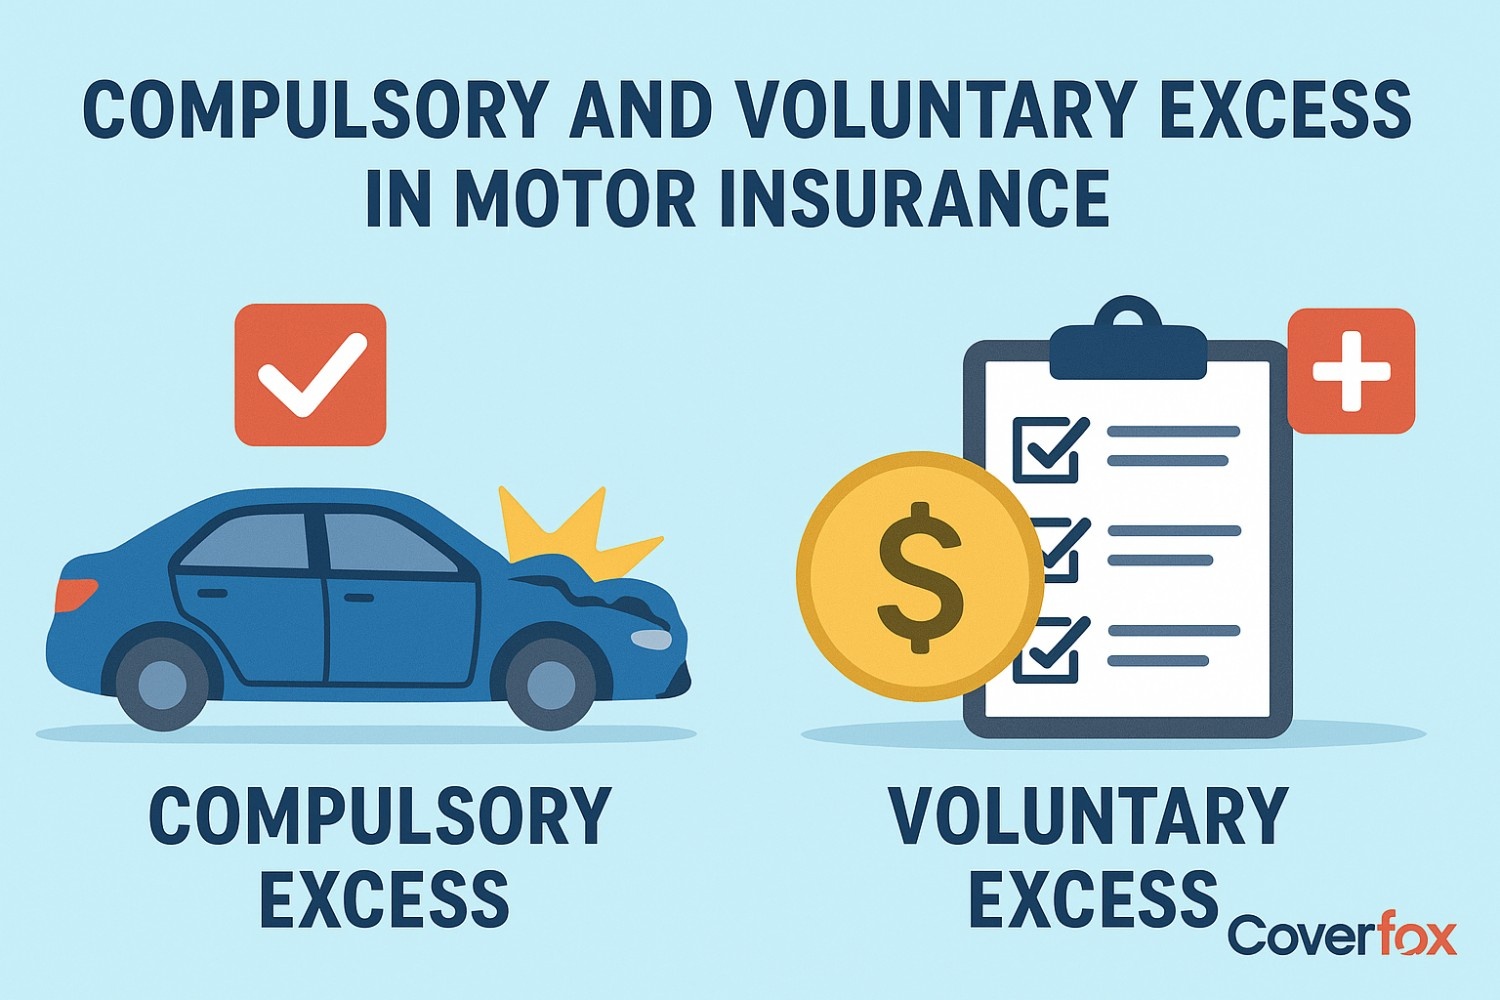
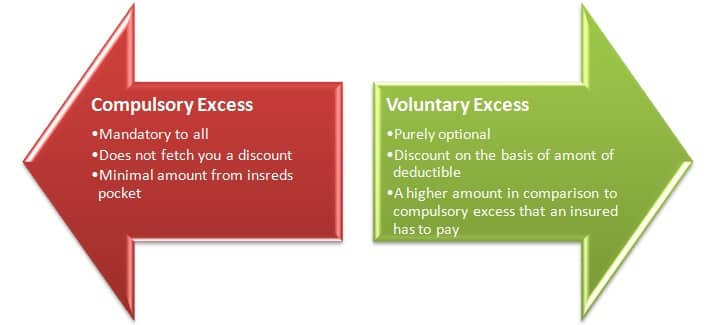
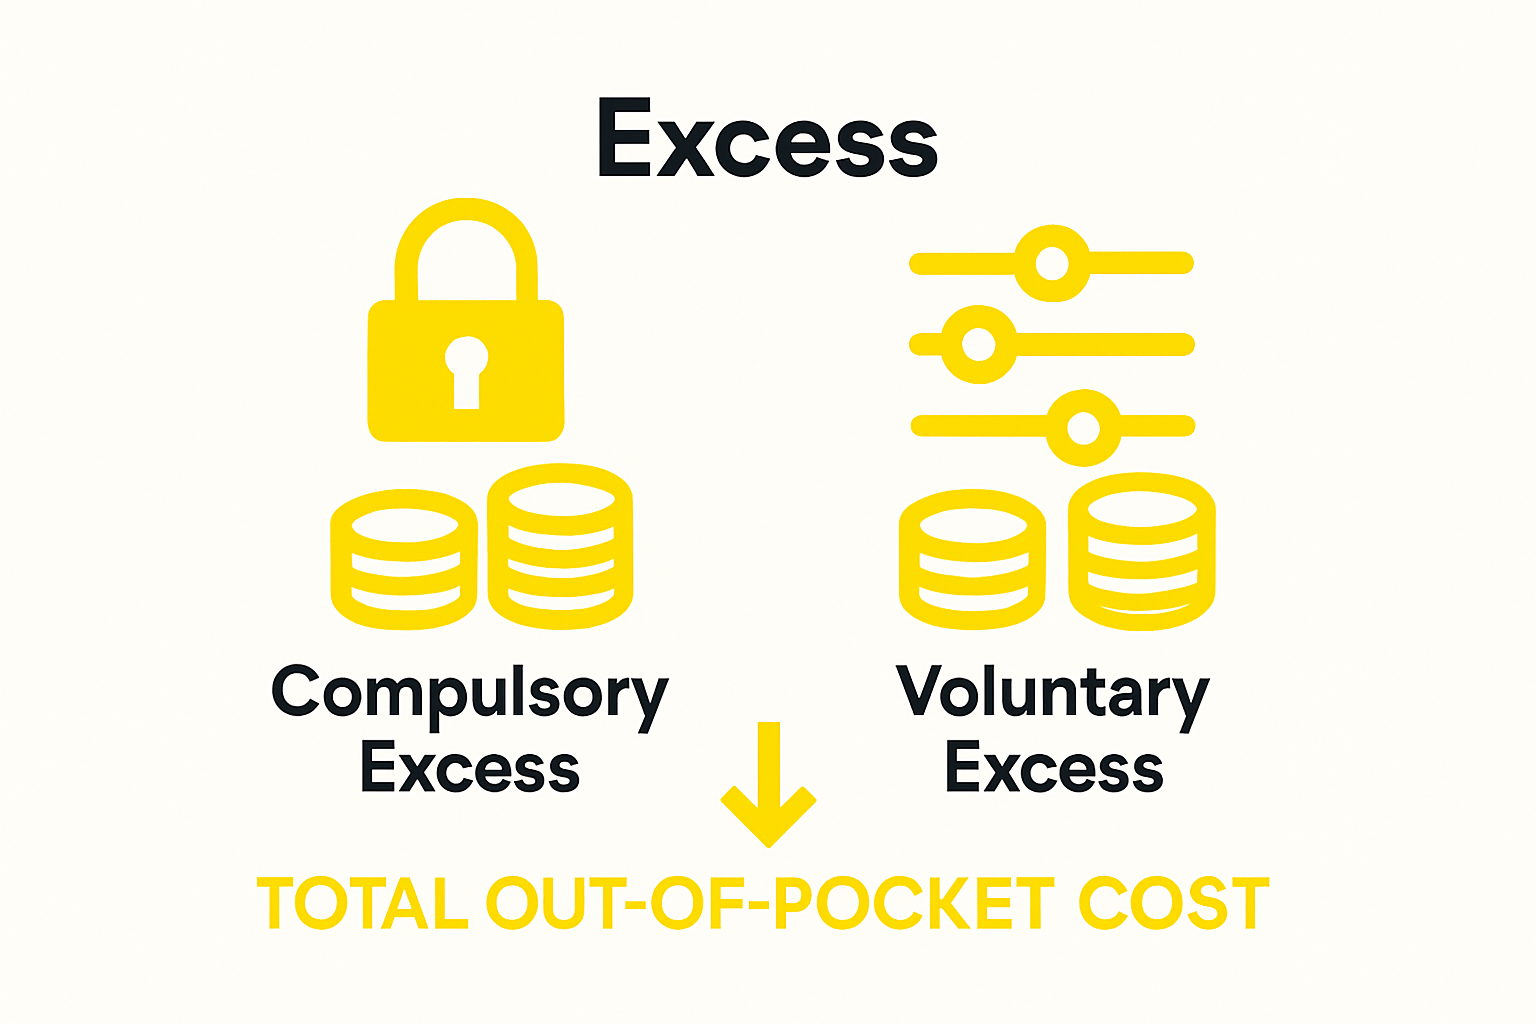
At its core, compulsory excess is the agreed portion of a claim you must pay yourself before your insurer covers the rest. Its key purpose is to reduce small, nuisance claims. This keeps insurance costs down for everyone, as insurers spend less on processing minor incidents. For you, the trade-off is clear: a slightly higher risk on small damages in exchange for much cheaper annual coverage.
The benefits for everyday life are tangible. Imagine you scraped your car against a bollard. With a standard policy, you might hesitate to claim a £300 repair if your premium will jump £500 next year. However, with a compulsory excess of £250, you simply handle that cost yourself and protect your no-claims bonus. This smart approach keeps your future premiums low and your finances stable.
Must Read
Consider home insurance. A broken window from a storm might cost £400 to fix. If your compulsory excess is £200, you pay that amount, and your insurer covers the rest. Without excess, you might avoid claiming entirely to prevent a rate hike. Thus, the excess becomes a calculated tool to use your policy when it truly matters—for major losses, like a burglary or a burst pipe.
The real value lies in freedom from the "rat race" of tiny claims. Instead of worrying about every minor incident, you know exactly when to step in. This clarity reduces anxiety and allows you to budget effectively. It turns insurance from a reactive safety net into a proactive financial strategy for the big, unpredictable events.
 What is Excess in Insurance? Understanding Its Role
To explore this on your own, start by comparing premium quotes with different excess levels on comparison websites. A £50 increase in your excess often reduces your premium by 10–15%. Next, ask your insurer: "What is the maximum excess I can choose while still being covered for major risks?" Finally, always set aside the excess amount in a separate savings account. This simple habit ensures you're never caught off guard.
Compulsory excess insurance isn't about paying more—it's about paying less on purpose for the things you can handle. By embracing the small, predictable cost, you gain greater control over your finances and genuine peace of mind for the big surprises.