Compulsory Vs Voluntary Excess
Okay, let’s talk about insurance. I know, I know—it’s about as exciting as watching paint dry while being poked by a very dull stick. But stick with me, because we’re diving i...
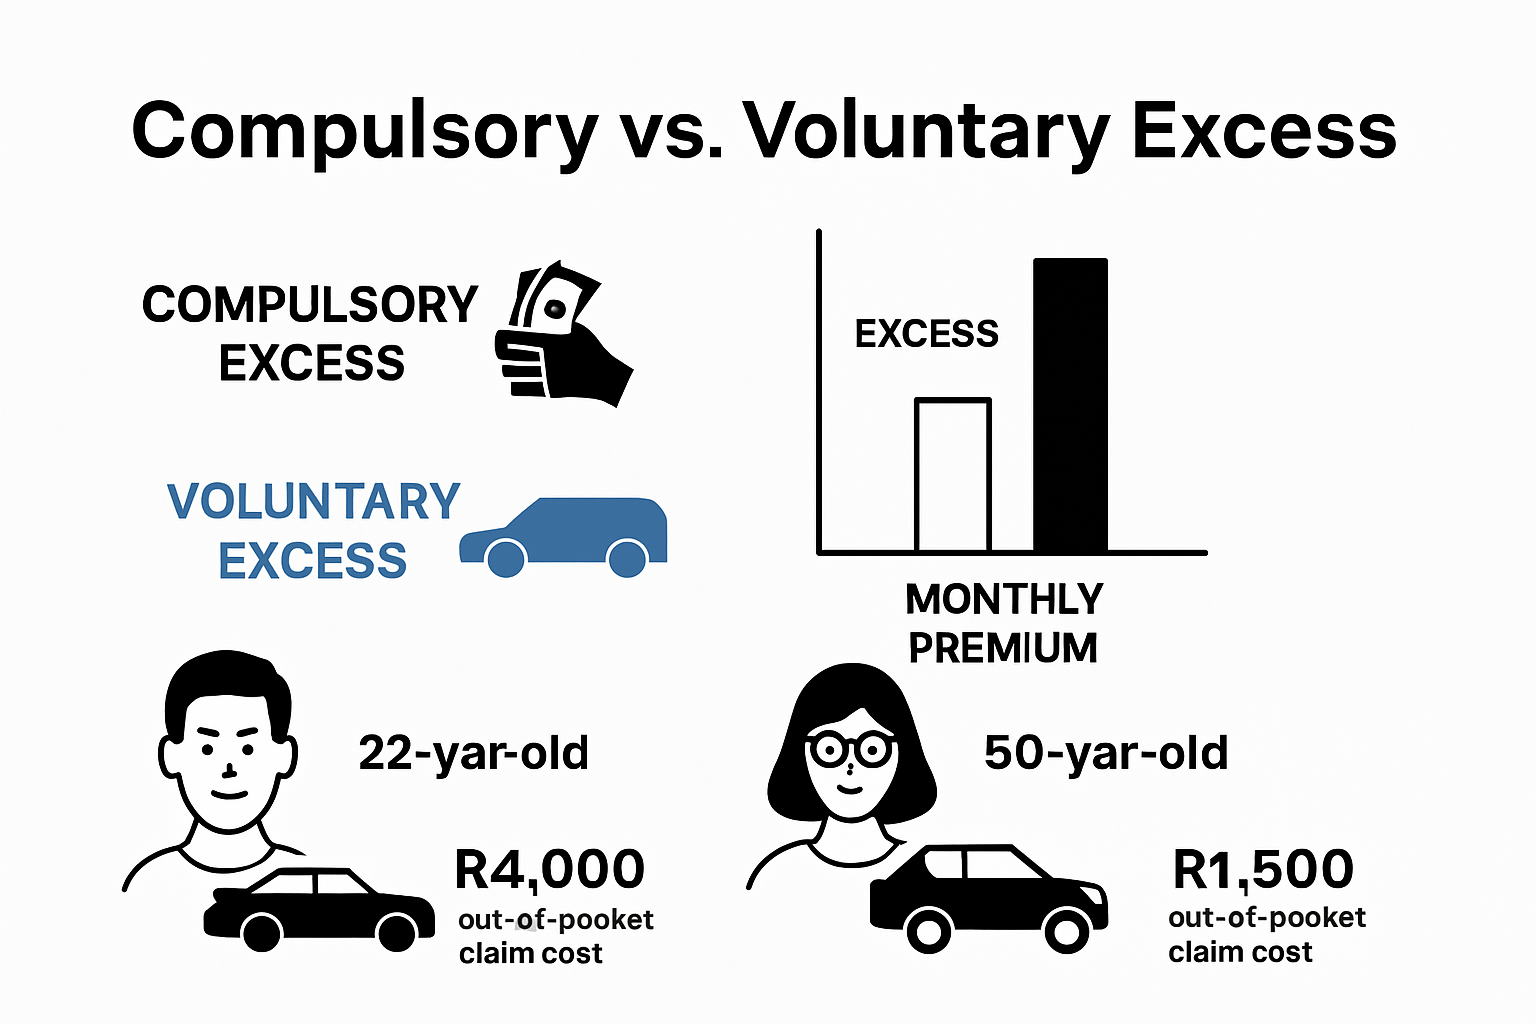
Okay, let’s talk about insurance. I know, I know—it’s about as exciting as watching paint dry while being poked by a very dull stick. But stick with me, because we’re diving into the surprisingly juicy world of compulsory vs. voluntary excess. Think of it as the "choose your own adventure" of your policy, but with fewer dragons and more fine print.
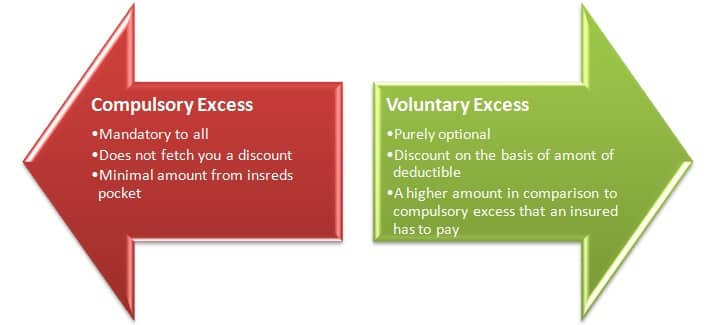
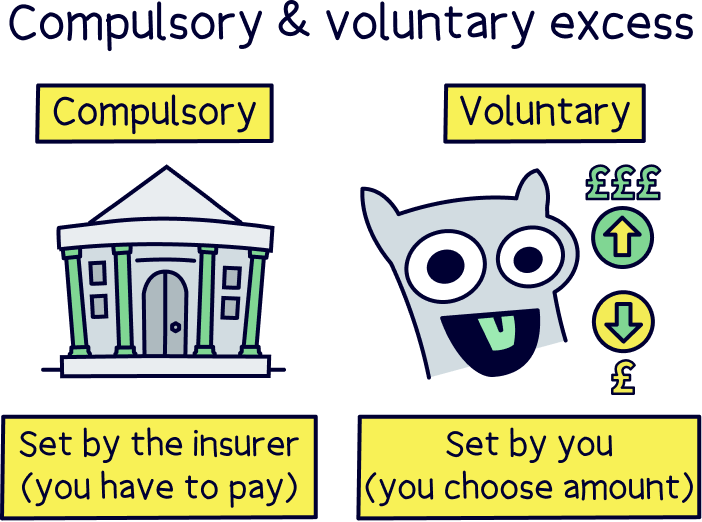
First up: compulsory excess. This is the non-negotiable part. Your insurer sets a fixed amount—say, £250—that you always pay toward a claim. It’s like the entrance fee to the “I’ve Had a Mishap” club. You don’t get a say, but it keeps your premium low. Annoying? A little. But it’s the price of playing the game.
Then there’s voluntary excess. Ah, here’s where you get to pretend you’re in control. You choose to pay extra—maybe another £250—on top of the compulsory bit. Why would anyone do that? Because it slashes your monthly premium! It’s like saying, “I’ll take a higher risk for a cheaper latte fund.” But here’s the joke: if you actually do crash, you’ll be forking over £500 total. Suddenly that latte fund tastes a little bitter.
Must Read
The golden rule? If you’re a careful driver (or just lucky), a higher voluntary excess can save you cash. If you’re a butterfingers prone to bumping lamp posts, stick to the compulsory minimum. Your bank account will thank you.
So which one’s better? Neither! It’s like choosing between extra guacamole or saving for a house—it’s all about your vibe. The real win? You’re being financially savvy just by asking the question. Give yourself a pat on the back (gently, no claims needed). Now go treat yourself—you’ve earned it. You’ve got this, and your future self is smiling all the way to the bank.