Difference Between Voluntary And Compulsory Excess Car Insurance
Let’s be honest: car insurance jargon can feel like a secret handshake you were never taught. You hear words like "excess" and suddenly your brain conjures images of boring sp...
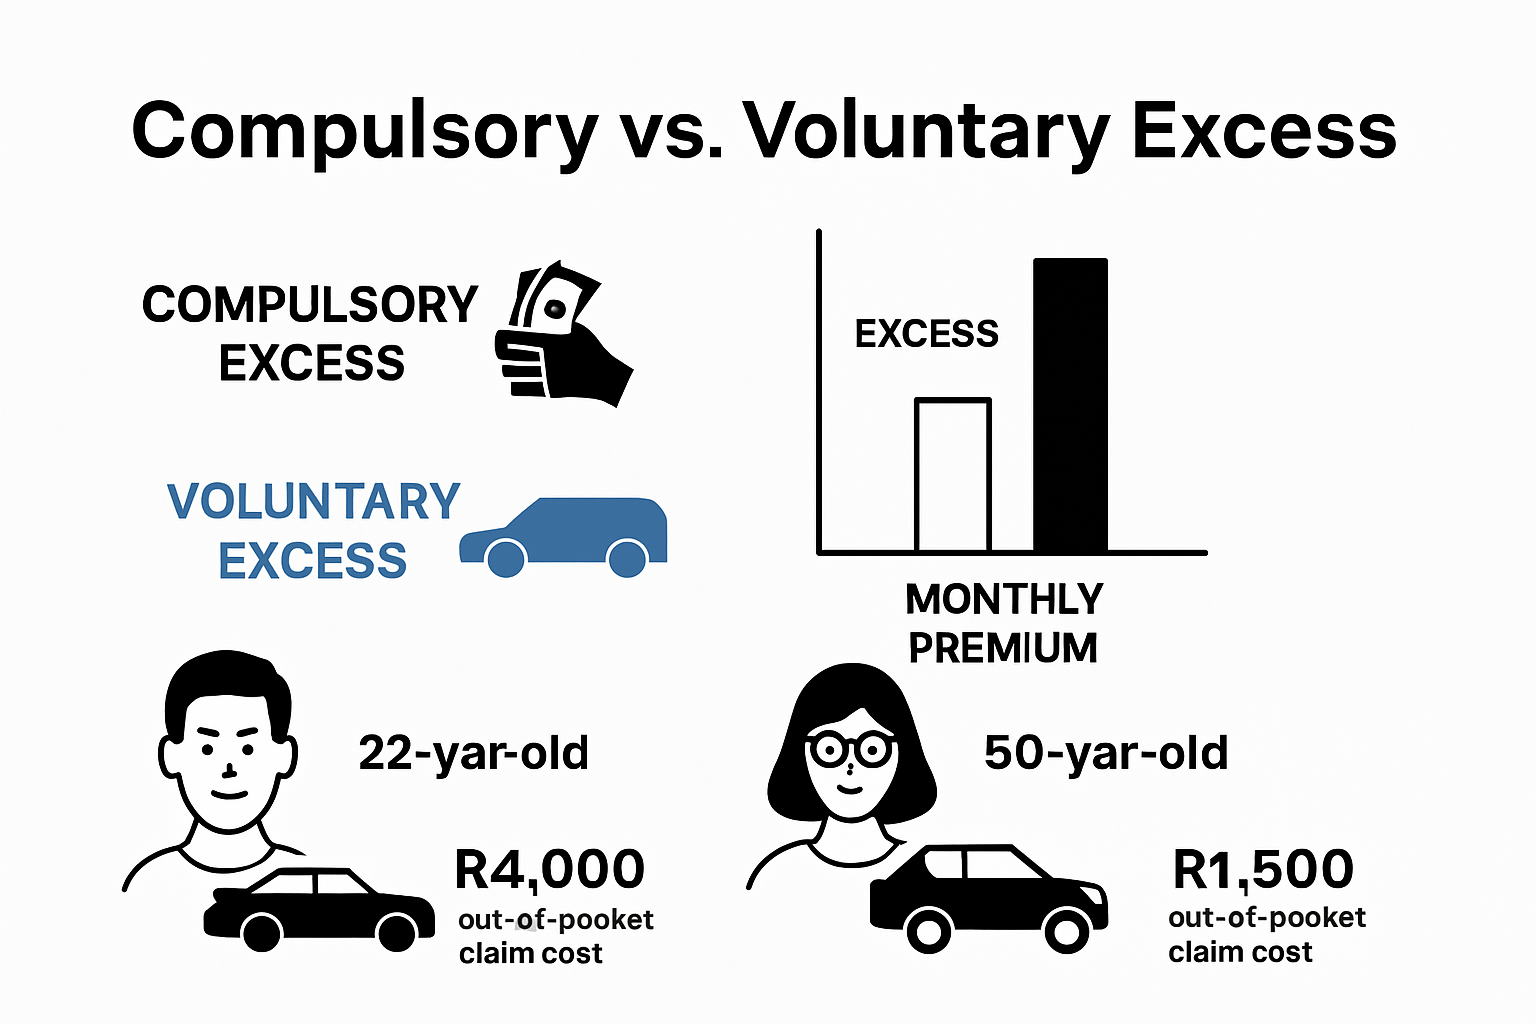
Let’s be honest: car insurance jargon can feel like a secret handshake you were never taught. You hear words like "excess" and suddenly your brain conjures images of boring spreadsheets. But stick with me, because this tiny detail—the difference between voluntary and compulsory excess—actually has a big, friendly hand in your wallet.
Think of it like a pizza delivery
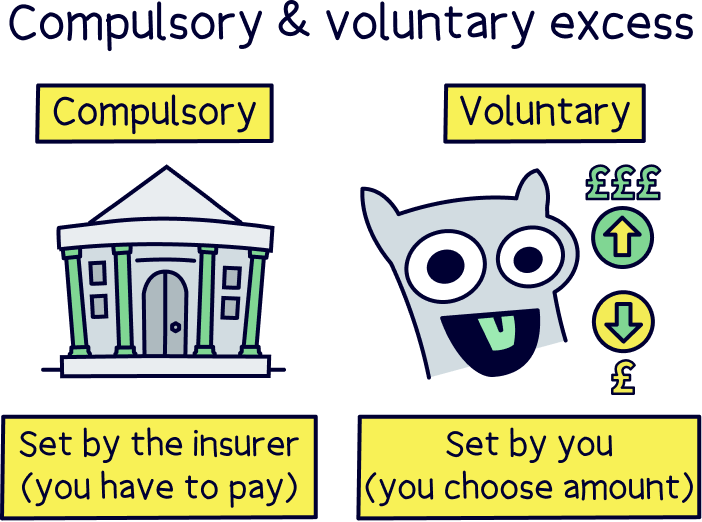
Imagine you order a pizza. The compulsory excess is like the unavoidable delivery fee—everyone pays it, no matter what, if something goes wrong. The voluntary excess is like the extra tip you choose to add to get better service (or in this case, a lower premium). You’re in the driver’s seat for the voluntary part, but the compulsory? That’s set by the insurance company.
The compulsory bit: the non-negotiable
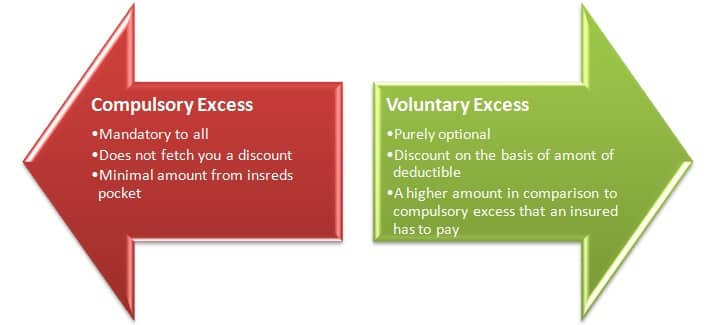
This is the fixed amount your insurer says you must pay if you make a claim. They decide it based on your age, driving history, and the car itself. It’s like the cover charge at a club—you can’t skip it, and it’s not up for debate. For a new driver or a flashy sports car, it might be steeper.
Must Read
The voluntary bit: your personal slider
Here’s where you get to be the boss. You can choose to add a voluntary excess on top of the compulsory amount. Why would you? Because a higher voluntary excess usually lowers your monthly premium. It’s a trade-off: you say, “I’ll pay more if I crash, if you give me a discount now.” It’s like agreeing to bring your own snacks to the movie theater so the ticket costs less.
A little story about Sarah and her bumper
Sarah once bumped a bollard in a parking lot. Her compulsory excess was $400, and she added a voluntary excess of $300 to save money each month. Total cost to fix: $700. She grumbled, but remembered she’d saved way more than that over two years of lower premiums. Smart Sarah—she’d made the math work for her.
 Compulsory and Voluntary Excess In Motor Insurance
Why you should actually care
This isn’t just abstract numbers—it’s about real money and peace of mind. Setting your voluntary excess too high might save you cash upfront, but could hurt if you have a fender bender. Set it too low, and you’ll pay more every month for the privilege. It’s like choosing between a sturdy umbrella or a cheap one—you don’t know if you need it until it rains.
Think of your driving style. Are you a careful, “park far from the cart corral” type? Maybe a higher voluntary excess is your friend. A bit of a lead-foot or new to the road? A lower one might be kinder to your wallet when the unexpected happens. It’s all about balance, like knowing when to splurge on guacamole and when to stick with plain salsa.
 All About Compulsory and Voluntary Excess in Motor Insurance
The quick takeaway
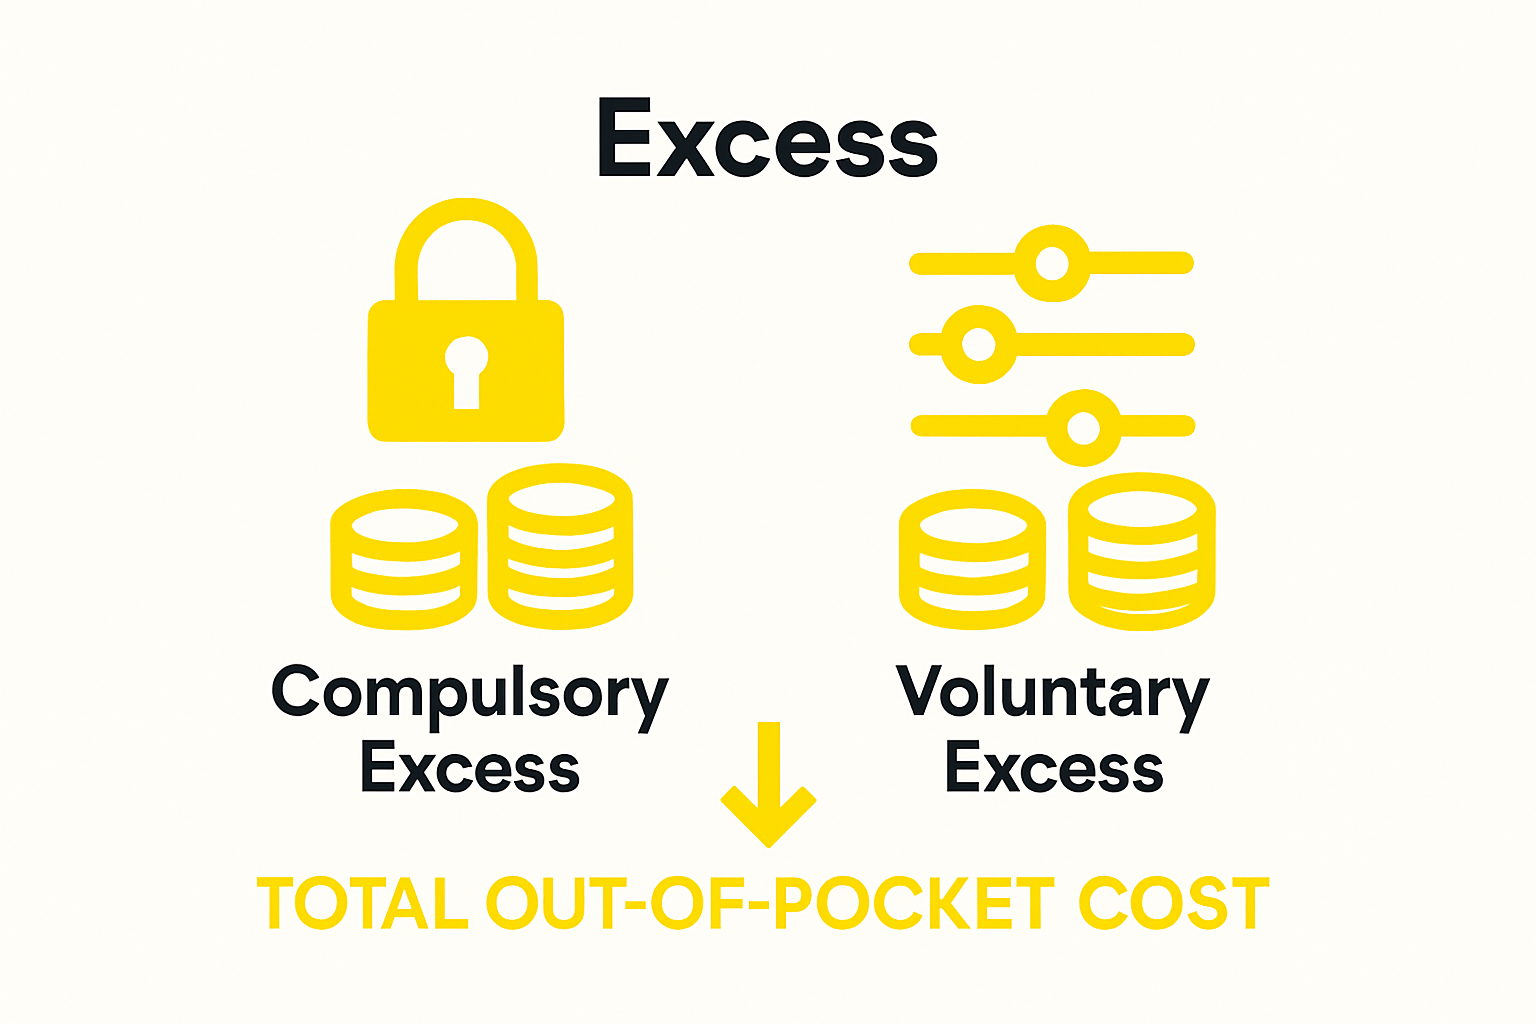
Compulsory excess is the fixed fee you can’t change. Voluntary excess is the slider you control to tweak your premium. Together, they add up to your total out-of-pocket cost if you make a claim. The magic is finding the sweet spot that doesn’t leave you broke after a scrape, but also doesn’t bleed your bank account dry every month.
So next time you renew, don’t just blink at the numbers. Ask yourself: “Am I willing to pay a bit more later to pay less now?” It’s a simple question with a surprisingly personal answer. And honestly, that kind of choice feels pretty good—like being the one who decides how much cheese goes on your pizza.