How To Get Rid Of A Vehicle With Negative Equity
Let’s face it: being stuck with a car that’s worth less than you owe is a financial drag. It’s a super common problem, hitting anyone who financed a vehicle that depreciated f...
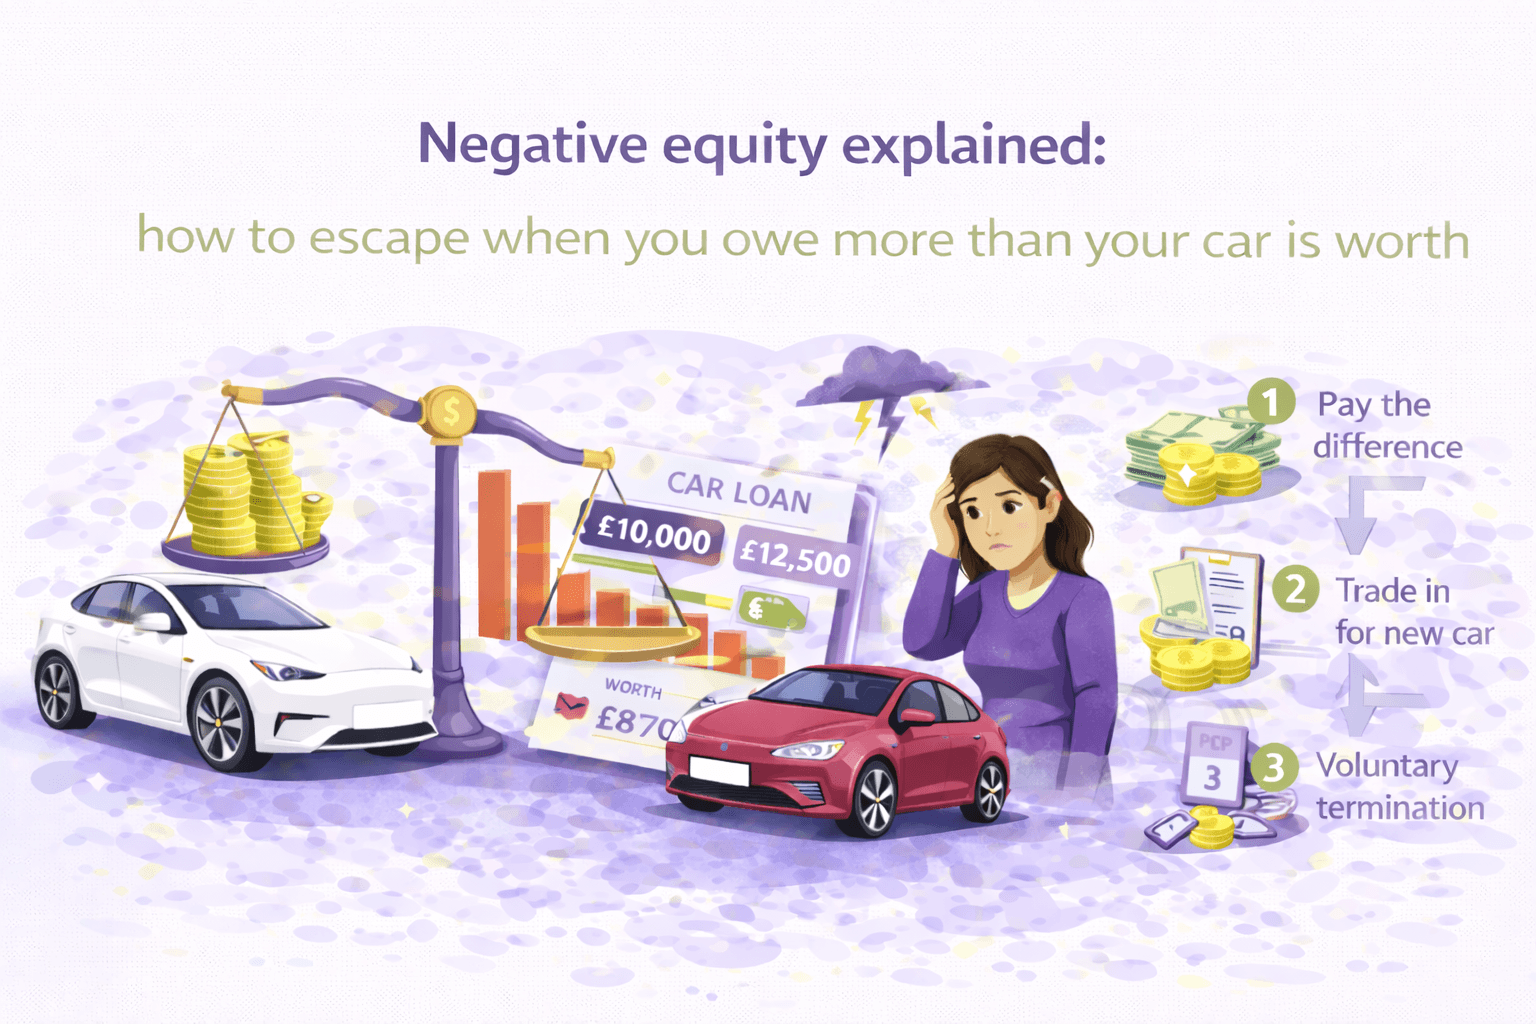
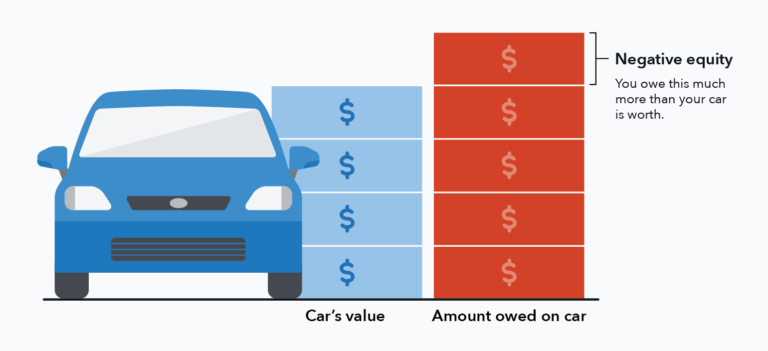
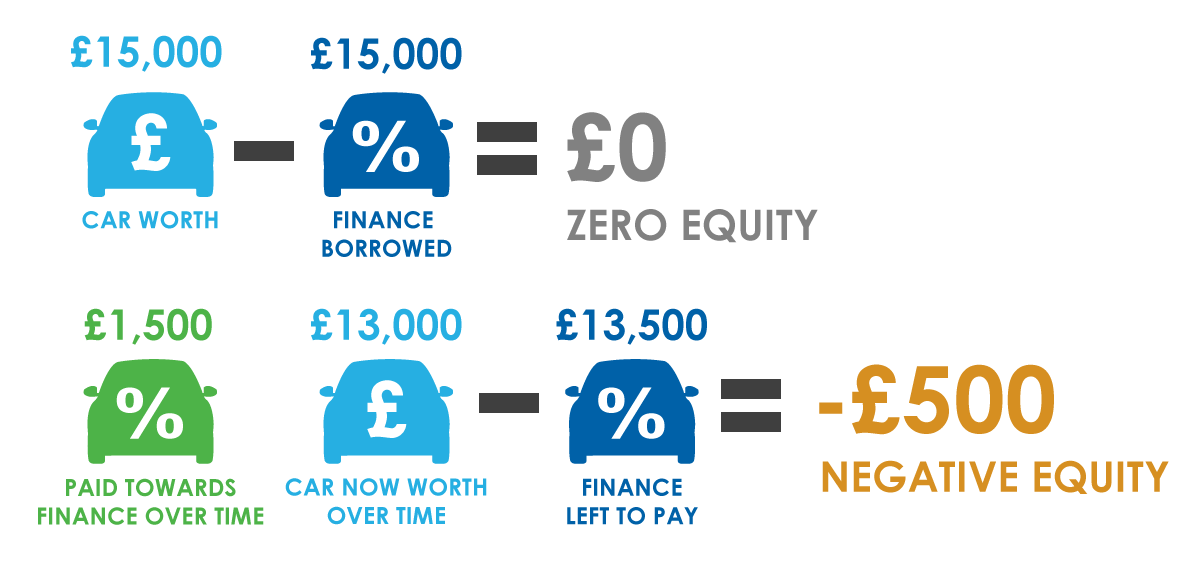
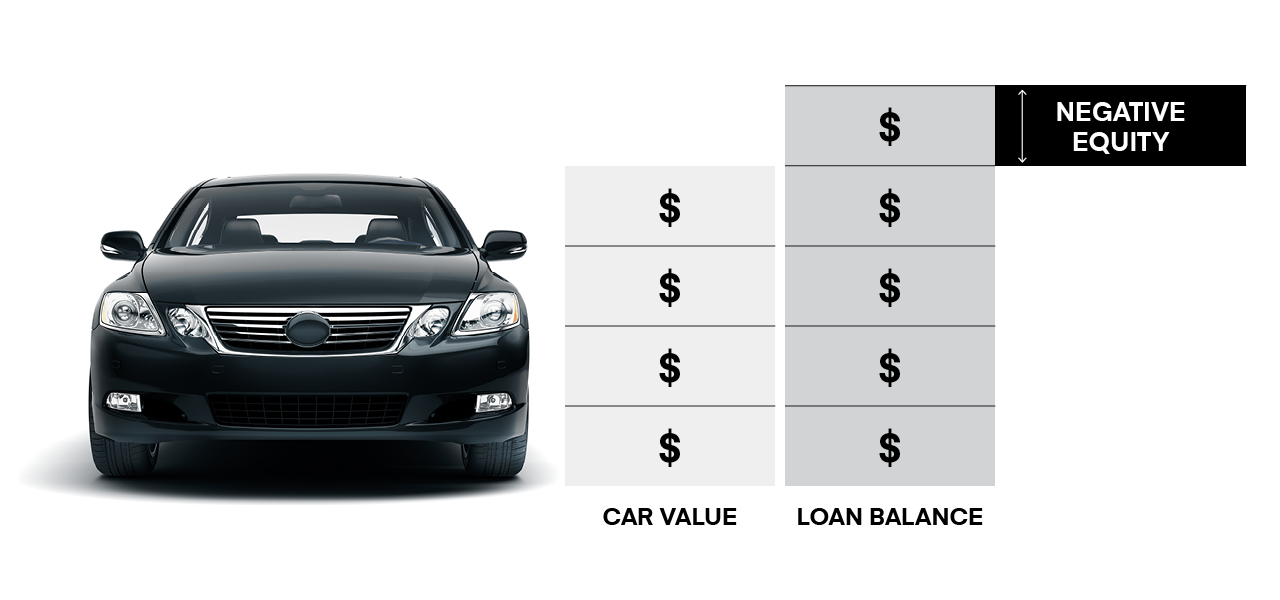
Let’s face it: being stuck with a car that’s worth less than you owe is a financial drag. It’s a super common problem, hitting anyone who financed a vehicle that depreciated faster than the loan balance. But you don’t have to ride that sinking ship forever. Ditching a negative-equity ride matters because it frees up your monthly cash flow and removes a major source of financial stress. For families, that means more room in the budget for groceries or a vacation instead of a car payment that feels like a punishment.
Take Jen, who owed $22,000 on an SUV worth $15,000. She felt trapped until she realized that rolling over negative equity into a cheaper, reliable used car lowered her payment by $150 a month. Then there’s Mark, who traded his upside-down truck for a lease on a subcompact model—his negative equity was spread into the lease terms, giving him a fresh start in three years. These moves aren’t magic; they’re strategy.
The first practical step? Check your car’s true value on sites like Kelley Blue Book. Know the exact gap between what you owe and what it’s worth. Next, pay down a chunk of that negative equity with a lump sum if you can. Even $500 helps. Then, explore selling privately—you’ll often get more than a dealer trade-in, shrinking the gap faster.
Must Read
Another solid move: refinance your loan at a lower interest rate. This won’t erase the negative equity, but it can slash your monthly payment, buying you time. Finally, consider a voluntary repossession only as a last resort—it wrecks your credit, but it does end the cycle. For most, the winning play is trading for a cheaper car and using the savings to chip away at the debt.
Getting rid of negative equity isn’t about a quick fix; it’s about strategic progress. Each step—whether it’s selling, refinancing, or downsizing—brings you closer to positive equity and real financial freedom. So, don’t let that upside-down number scare you. With a plan, you can ditch the dead weight and drive forward into a better deal for you and your family.