Lease Accounting Journal Entries Example

So, you're an accountant, and you're feeling pretty confident about your skills, right? I mean, who needs lease accounting to throw a wrench in your perfectly organized world?...
So, you're an accountant, and you're feeling pretty confident about your skills, right? I mean, who needs lease accounting to throw a wrench in your perfectly organized world? But, let's be real, lease accounting can be a real challenge, even for the most seasoned accountants.
Take my friend, Alex, for example. He's been an accountant for years, and he thought he had seen it all. That is, until he encountered his first lease accounting journal entry. Let's just say it was a wild ride, full of IASB and FASB regulations, and a healthy dose of confusion.
The Basics of Lease Accounting
So, where do we start with lease accounting? Well, first things first, we need to understand the difference between a finance lease and an operating lease. A finance lease is basically a lease where the lessee (that's the person renting the asset) has control of the asset and is responsible for its maintenance and upkeep. On the other hand, an operating lease is more like a traditional rental agreement, where the lessor (the person owning the asset) is responsible for maintenance and upkeep.
Must Read
Now, let's talk about lease classification. This is where things can get a bit hairy, but stick with me, folks! Essentially, we need to classify each lease as either a finance lease or an operating lease, and then apply the corresponding accounting treatment. And, let me tell you, this is where the journal entries come in.
Lease Accounting Journal Entries Example
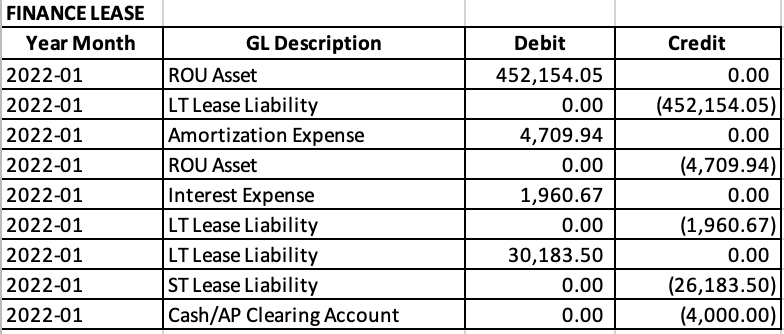
Okay, so let's say we have a company that signs a 5-year lease for a piece of equipment, with monthly payments of $1,000. The company needs to record this lease on their balance sheet, and that's where our lease accounting journal entry comes in. The entry would look something like this: Debit Right-of-Use Asset ($50,000), Credit Lease Liability ($50,000).
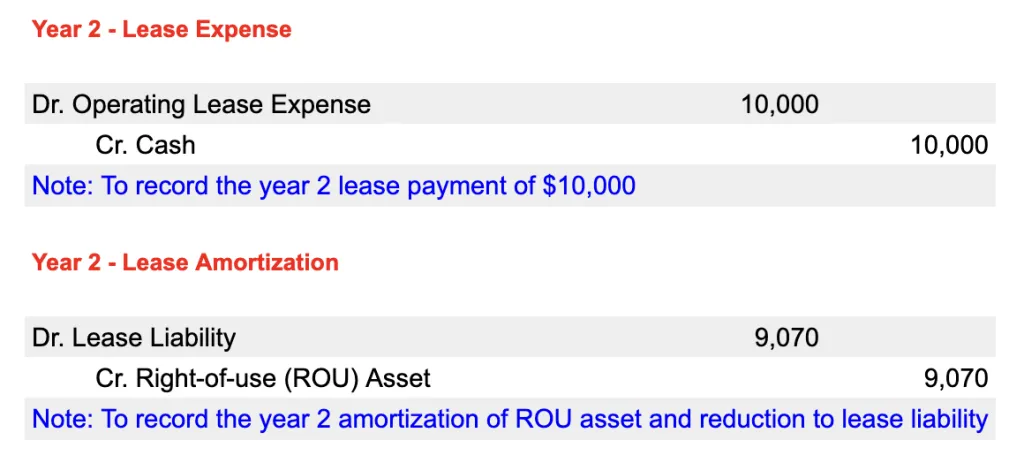 Journal Entries for Operating Lease: ASC 842 - Simple Guide
Now, you might be thinking, "Wait, what about the lease payments?" Well, my friend, that's where the interest expense comes in. Each month, the company would need to record the lease payment as a debit to lease expense and a credit to cash. And, let's not forget about the amortization of the right-of-use asset!
So, as you can see, lease accounting journal entries can be a bit of a puzzle, but once you get the hang of it, it's actually pretty straightforward. And, trust me, it's worth getting right, or you might end up with a financial statement that's more fiction than fact.
The Importance of Getting it Right
So, why is it so important to get lease accounting right? Well, for one thing, lease accounting errors can have serious consequences, from financial misstatement to regulatory penalties. And, let's not forget about the reputation damage that can come with a lease accounting scandal.
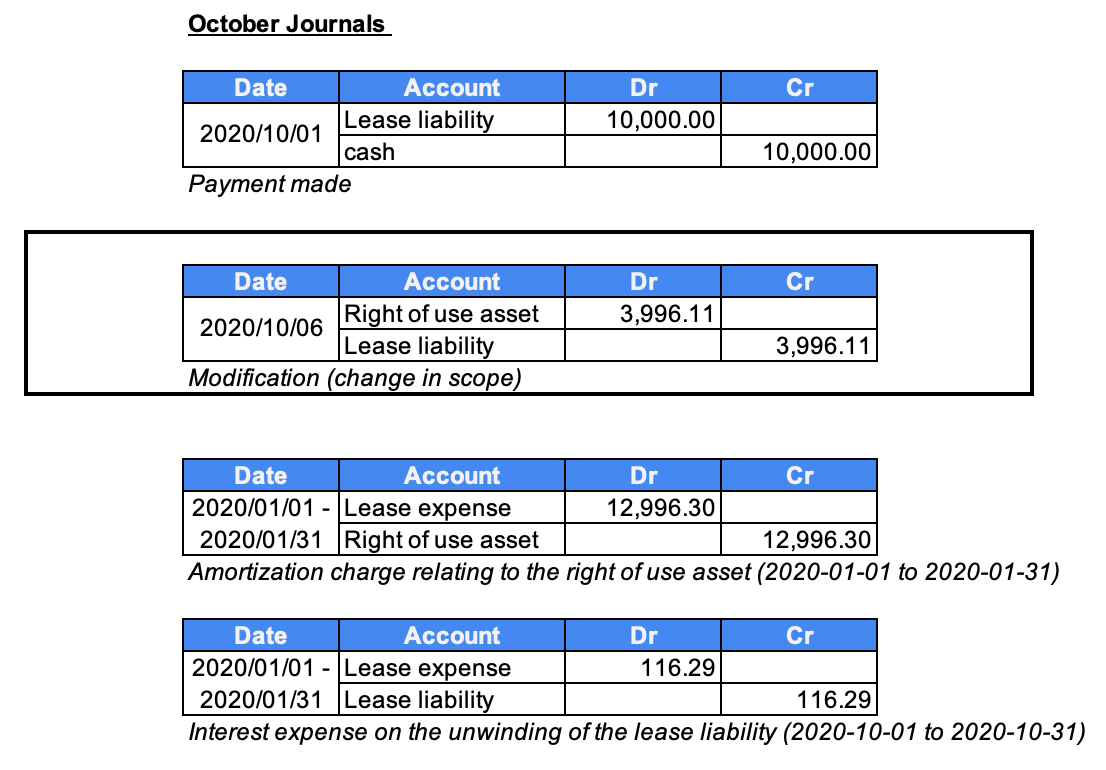 How to Calculate the Journal Entries for an Operating Lease under ASC 842
Now, I know what you're thinking: "This all sounds like a lot of work!" And, you're right, it is! But, trust me, the payoff is worth it. By getting lease accounting right, you'll be able to provide accurate and transparent financial reporting, which is essential for any business.
Conclusion
In conclusion, lease accounting journal entries might seem like a daunting task, but with a little practice and patience, you'll be a pro in no time. Just remember to classify those leases, record the journal entries, and amortize that right-of-use asset! And, most importantly, don't be afraid to ask for help when you need it.
So, the next time you're faced with a lease accounting journal entry, just take a deep breath, and remember: it's not as scary as it seems. And, if all else fails, you can always consult the lease accounting guides and experts out there. Happy accounting, folks!
