What Is Compulsory Excess In Car Insurance
So, you’ve got your car insurance sorted, and you’re feeling smug. But then someone drops the phrase “compulsory excess,” and suddenly it sounds like a threat. Relax. Pour a c...
So, you’ve got your car insurance sorted, and you’re feeling smug. But then someone drops the phrase “compulsory excess,” and suddenly it sounds like a threat. Relax. Pour a cuppa, and let’s decode this together—it’s way less scary than your aunt’s fruitcake.
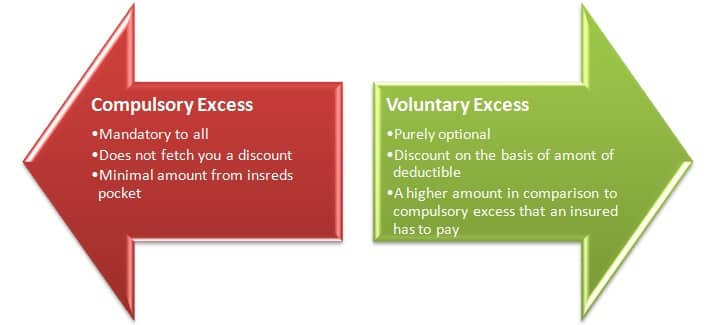
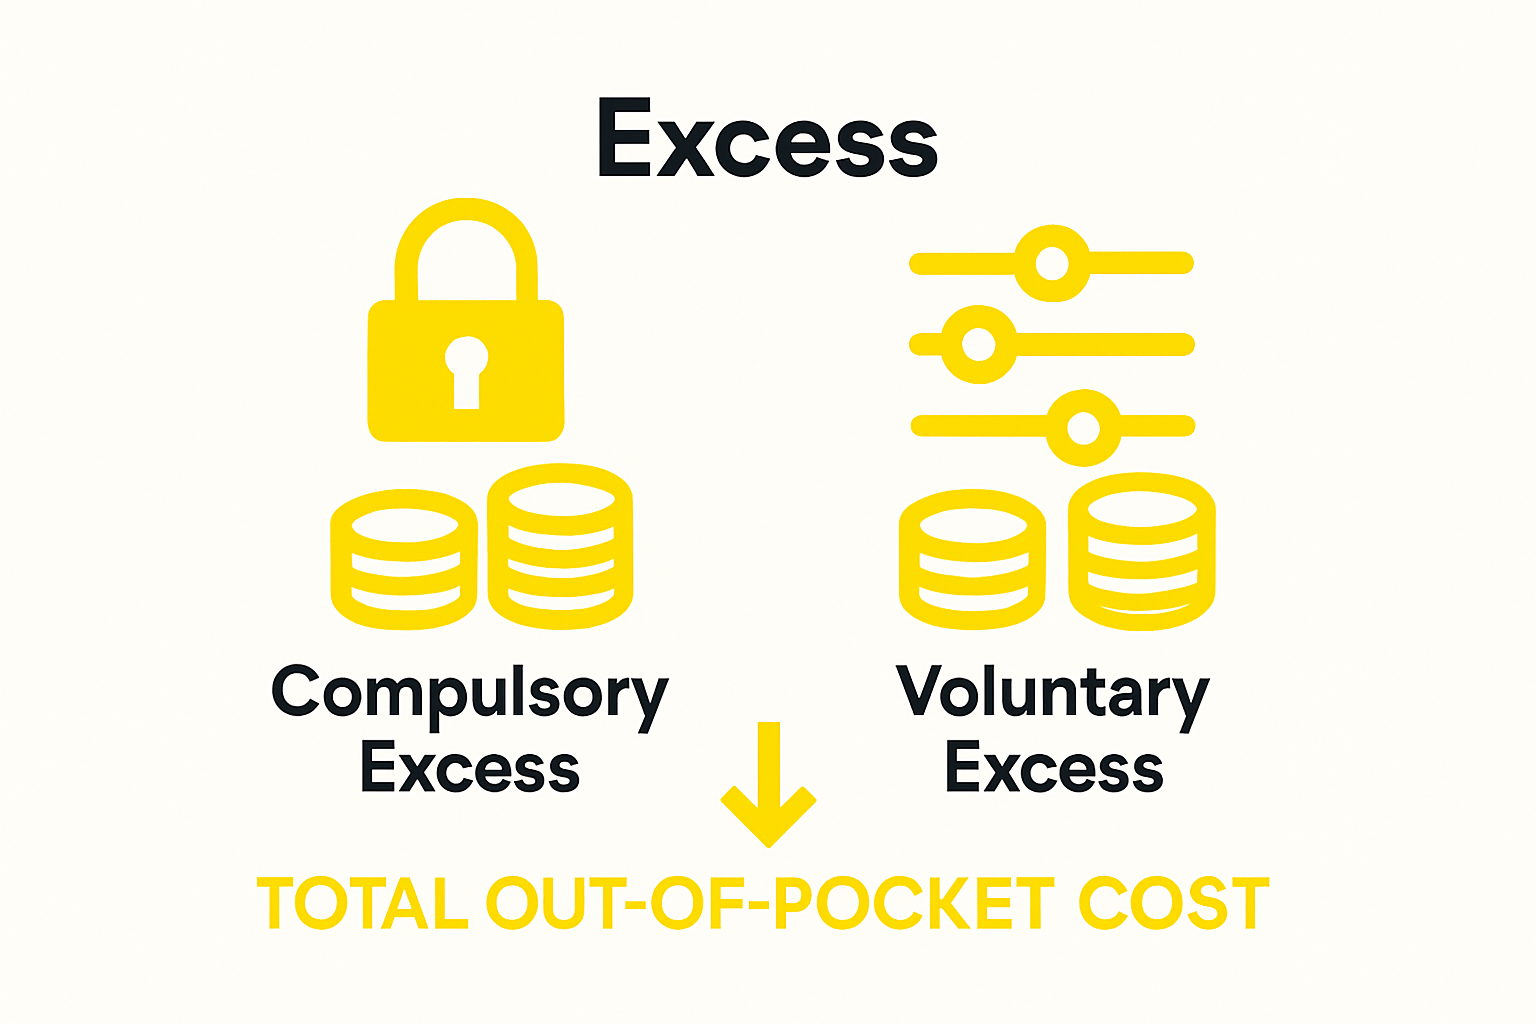
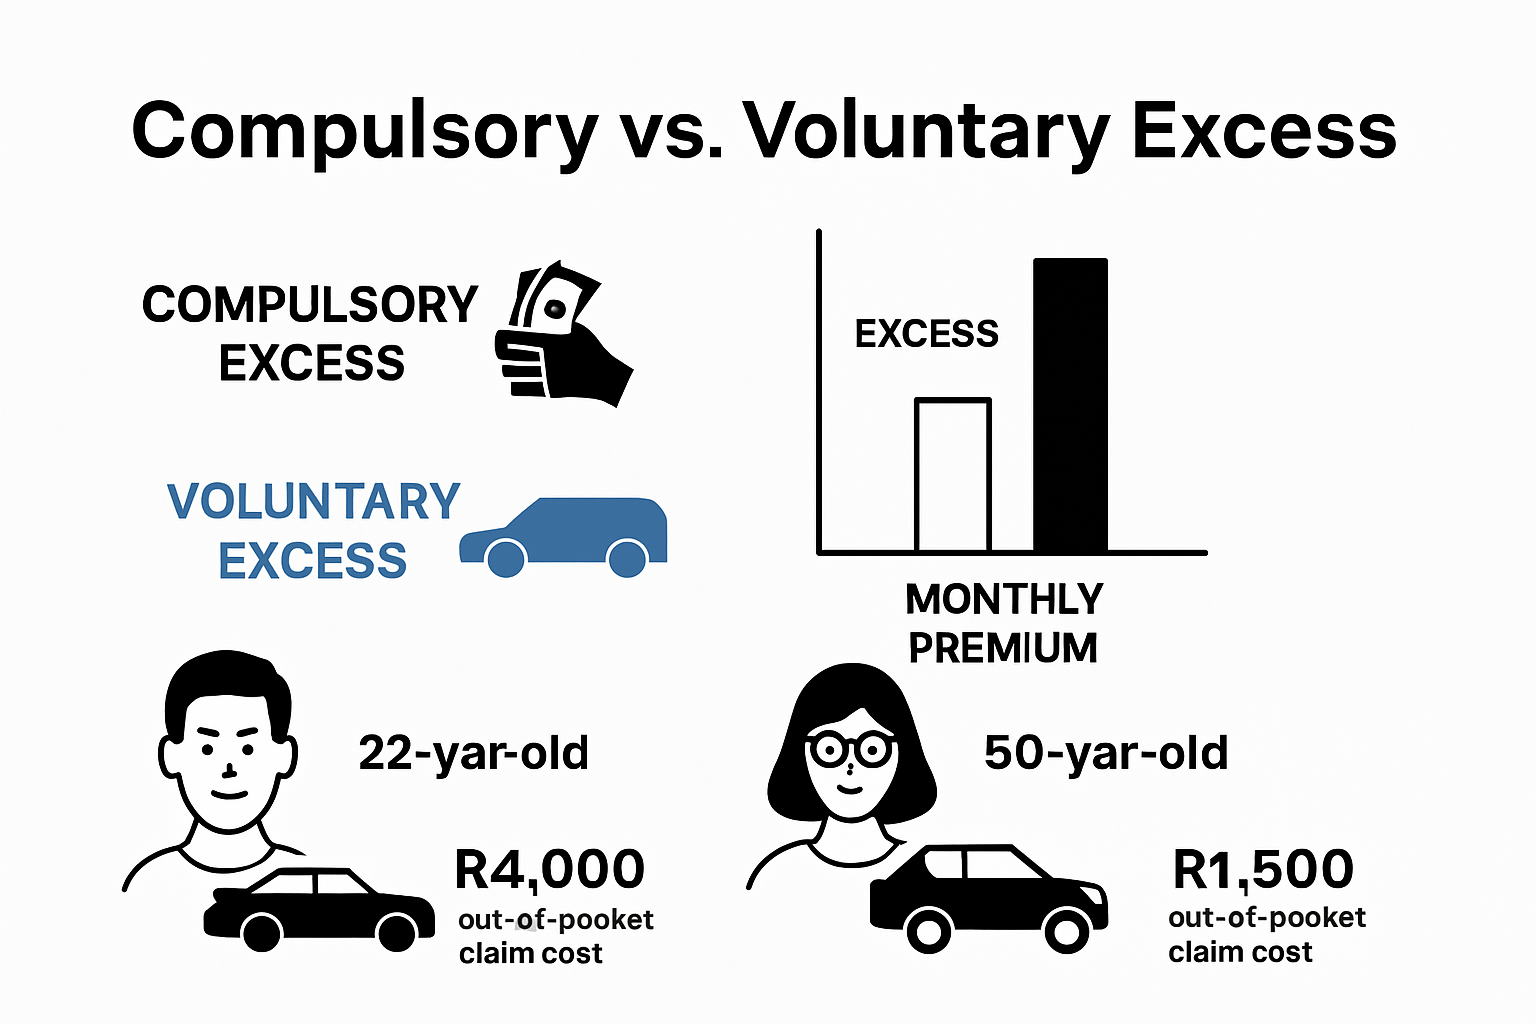
Think of compulsory excess as the non-negotiable “first bite” you take out of any claim. It’s a fixed amount—say, $250 or $500—that you must pay before your insurer chips in. For example, if you accidentally kiss a lamppost and repairs cost $2,000, and your compulsory excess is $300, you hand over the $300, and your insurer covers the rest. Annoying? A bit. But it’s designed to keep premiums lower for everyone—and to stop you from claiming for a scratch that a magic marker could fix.
Now, here’s the playful catch: you might also see a voluntary excess box you can tick. That’s your chance to play insurance roulette. Choosing a higher voluntary excess reduces your premium, but it also turns a minor fender-bender into a math problem. “Do I pay $800 to fix this… or just pretend it’s a new aerodynamic feature?” Pro tip: only pick a voluntary excess you could actually afford while weeping. And remember, your compulsory excess is set in stone by your insurer—no negotiations, no coupons, no sad puppy eyes.
Must Read
Why does it exist? Because insurance companies have a sense of humor (sort of). It keeps them from paying for every little oopsie, and it makes you a slightly more careful driver. So next time you see “compulsory excess” on your policy, just nod wisely. It’s not a trap—it’s just your way of saying, “I’ve got this.” And hey, seeing that number every month is a great reminder to drive like there’s cake at the finish line. You’ve got this. Literally. Now go enjoy the open road—and maybe avoid that lamppost. 🌟