What Is Compulsory Excess On Car Insurance
Imagine you’re cruising in your car, windows down, jammin’ to a cheesy ‘80s hit. Suddenly, WHAM—a rogue shopping cart dings your door. Yikes. You think, “No problem, insurance...
Imagine you’re cruising in your car, windows down, jammin’ to a cheesy ‘80s hit. Suddenly, WHAM—a rogue shopping cart dings your door. Yikes.
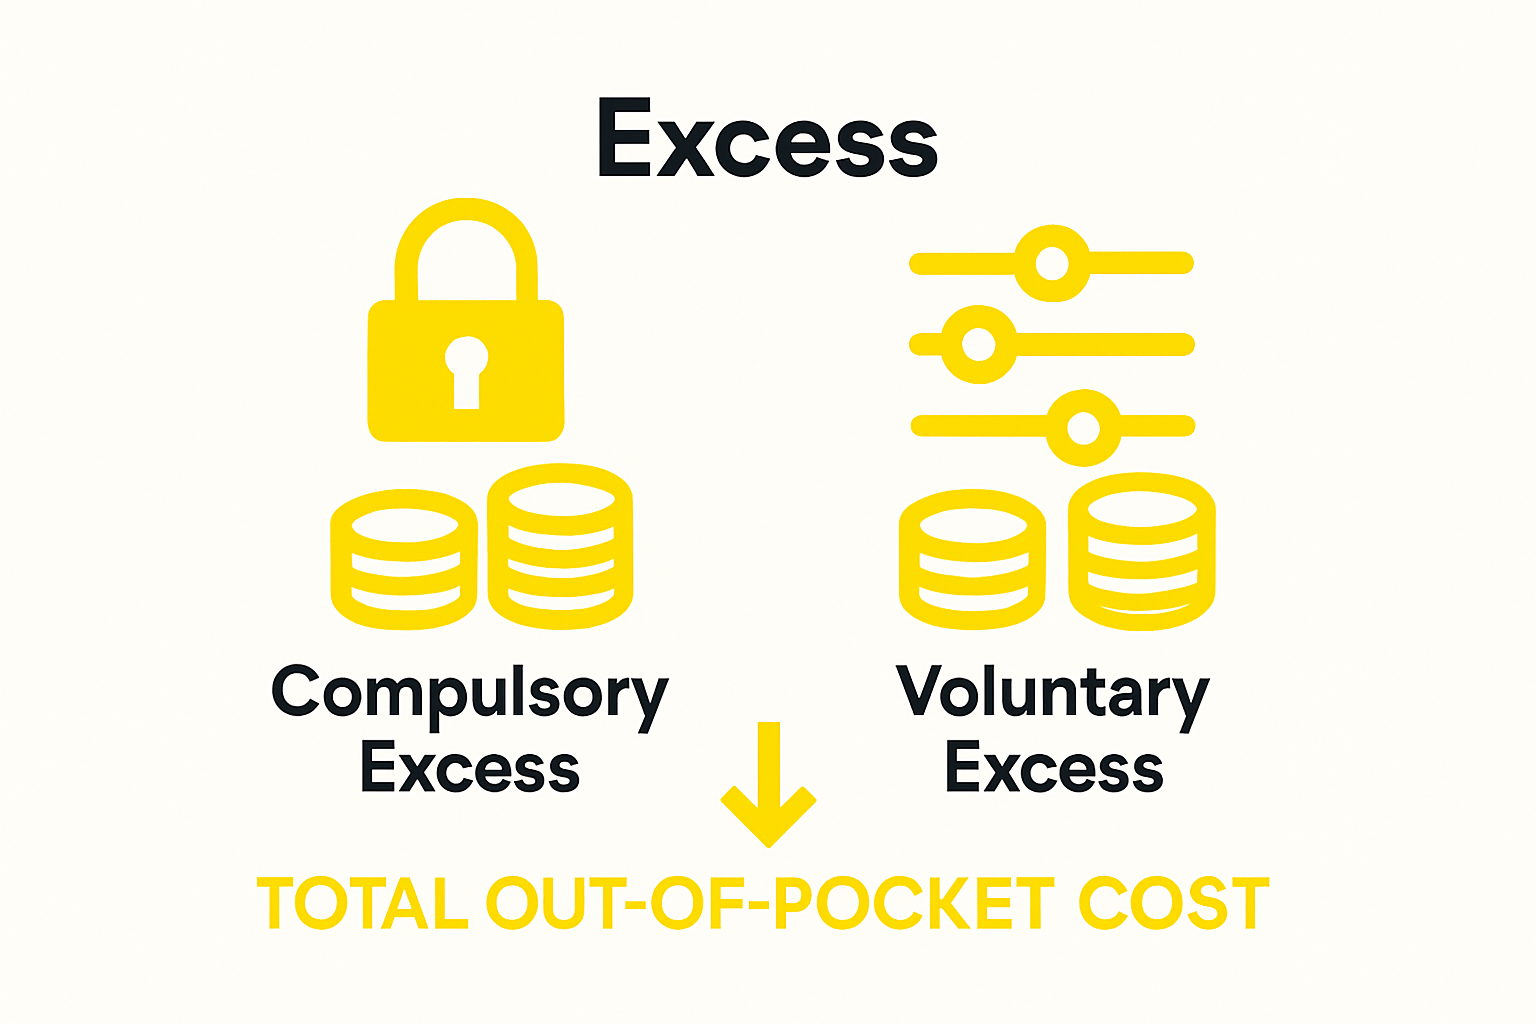
You think, “No problem, insurance has my back!” But wait. The insurance fairy waves a slightly annoying wand: compulsory excess. It’s the fee you must pay before your insurer chips in. It’s not optional—it’s part of the deal, like paying for guacamole on your taco.
So, what actually is it?
Think of excess as your financial “first punch.” If your crash costs $2,000 and your excess is $500, you pay the first $500. The insurance company covers the rest.
Must Read
It’s a classic “you break it, you buy the first bit” situation. Compulsory excess is the non-negotiable chunk set by your insurer. You can’t haggle it down—it’s tied to your age, driving history, or even your car’s horsepower.
Why does it even exist?
Honestly? It’s to stop you from filing a claim for a single lost hubcap. Insurers hate tiny, annoying claims more than you hate Monday mornings. Compulsory excess filters out the drama.
 Compulsory and Voluntary Excess In Motor Insurance
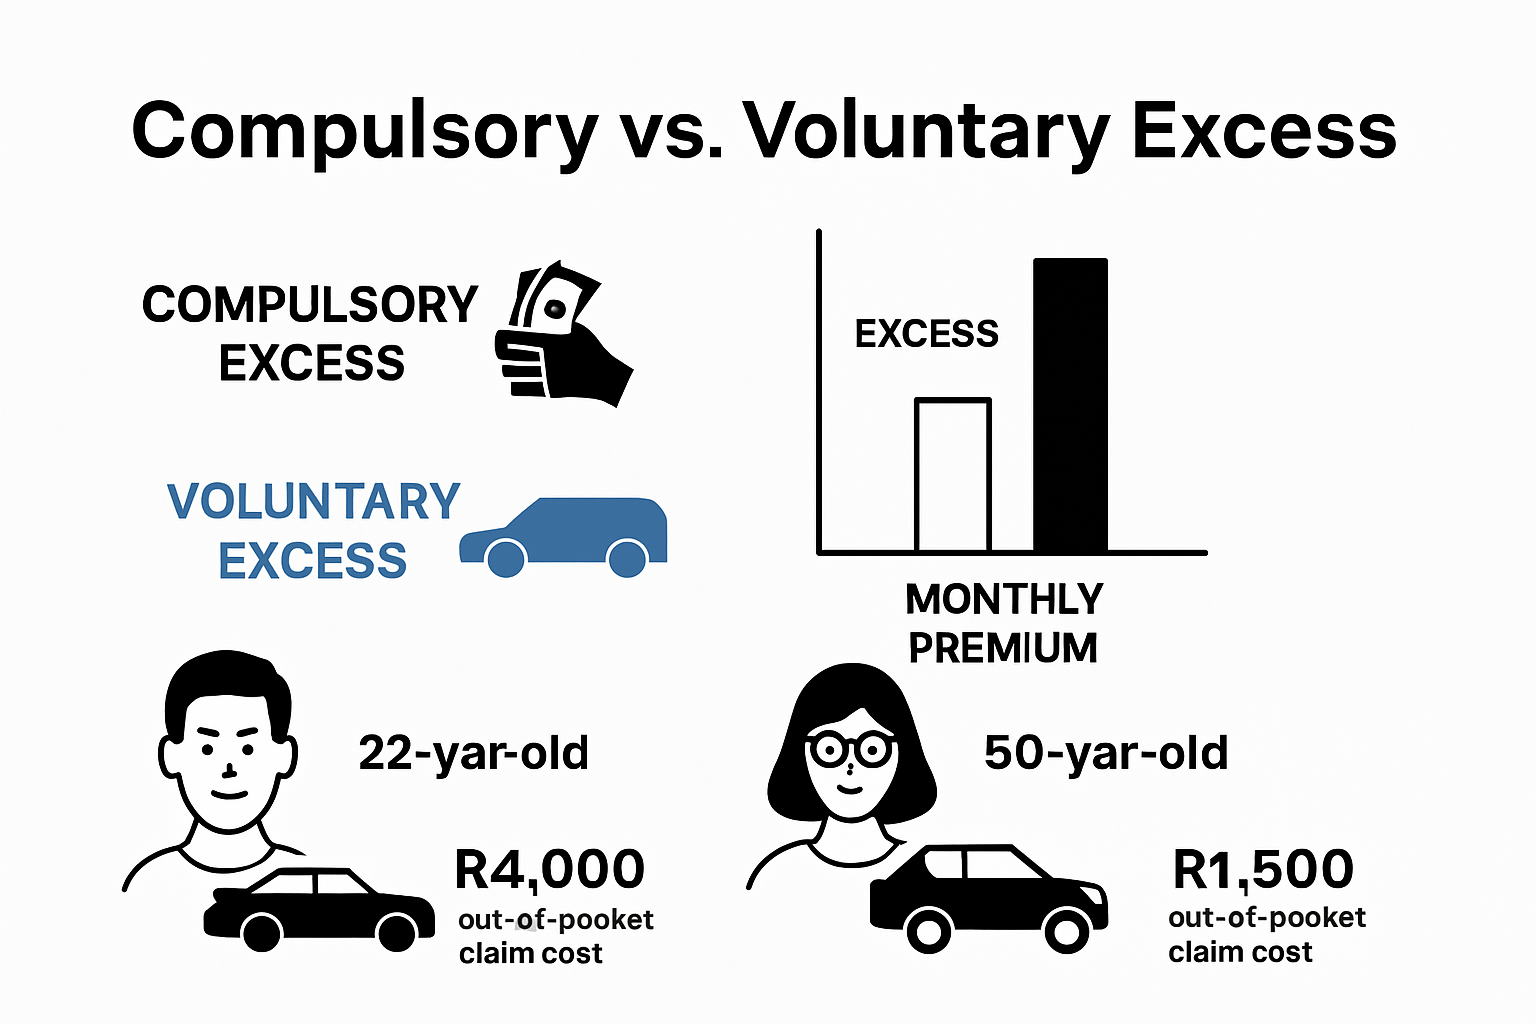
Fun fact: In some countries, if you’re under 25, your compulsory excess can be double or triple the normal amount. Why? Because young drivers are statistically more likely to yell “YOLO” and merge into a lamppost. Not you, of course. But your cousin? Maybe.
The quirky, sometimes ridiculous side
Here’s a wild truth: Your excess might be higher than the damage. Imagine scratching a bumper for $400, but your excess is $500. You pay the whole repair yourself. Insurance just shrugs and says, “Better luck next time, pal.” It’s like ordering a pizza, but realizing you have to tip the delivery driver more than the pizza costs. Ouch.
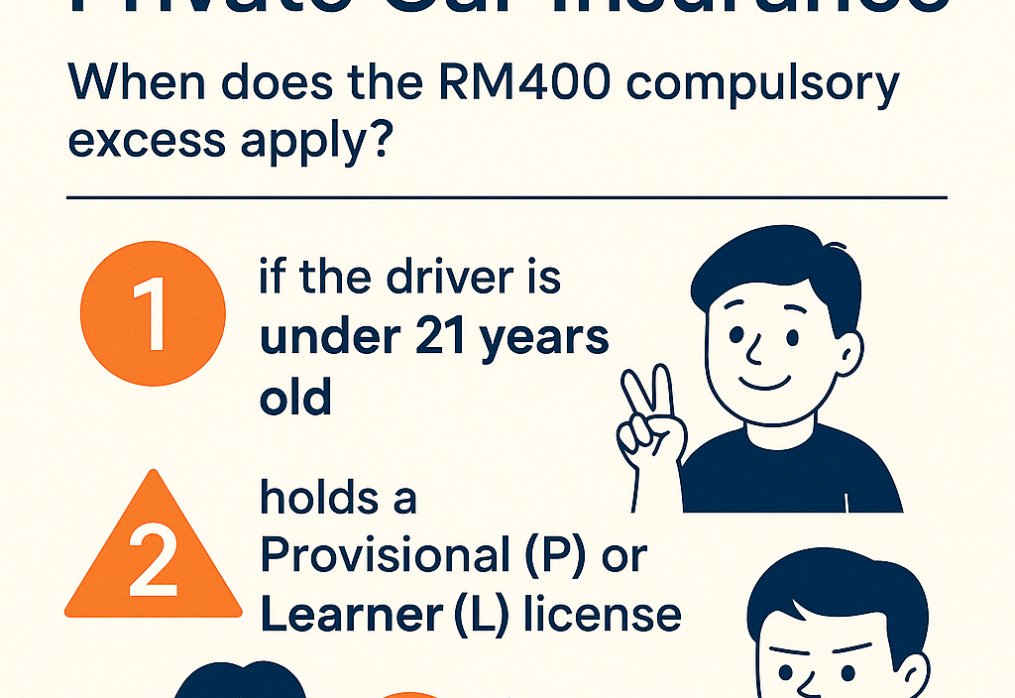 What Is Compulsory Excess in Private Car Insurance – And When Does It
And get this: Compulsory excess can be different for different types of claims. Hitting a pothole? One excess. Hitting a swan? Possibly another. Yes, swan-related claims are a real thing in the UK. They’re surprisingly common. Those birds are absolute road hazards.
How to not be surprised by it
Before signing any insurance policy, look for the “Excess” section in tiny font. Usually, it’s around $200–$800, but sports cars or high-performance hatchbacks often have a $1,000+ compulsory excess. Why? Because speed demons crash faster. Literally.
 All About Compulsory and Voluntary Excess in Motor Insurance
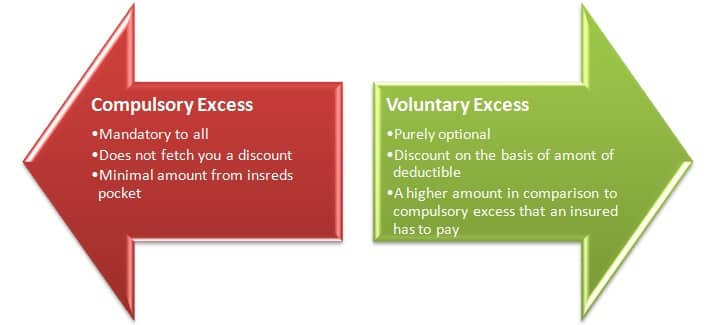
Pro tip: Never confuse compulsory excess with voluntary excess. Voluntary is like choosing to add extra cheese. Compulsory is the bread you have to eat first. You can adjust voluntary excess to lower your premium, but compulsory is set in stone.
The punchline
Compulsory excess is basically the bouncer at the insurance club. It says, “You can’t get in without paying the cover charge.” It’s not glamorous, but it keeps the system from collapsing under a pile of $50 claims for fallen bird droppings.
So next time you’re driving, remember: Your first $500 is on you. Avoid llamas, don’t text while merging, and maybe keep a stash of cash under your seat. Your wallet will thank you—and the insurance company will too. They might even send you a smiley-face emoji. (No, they won’t. But it’s fun to imagine.)