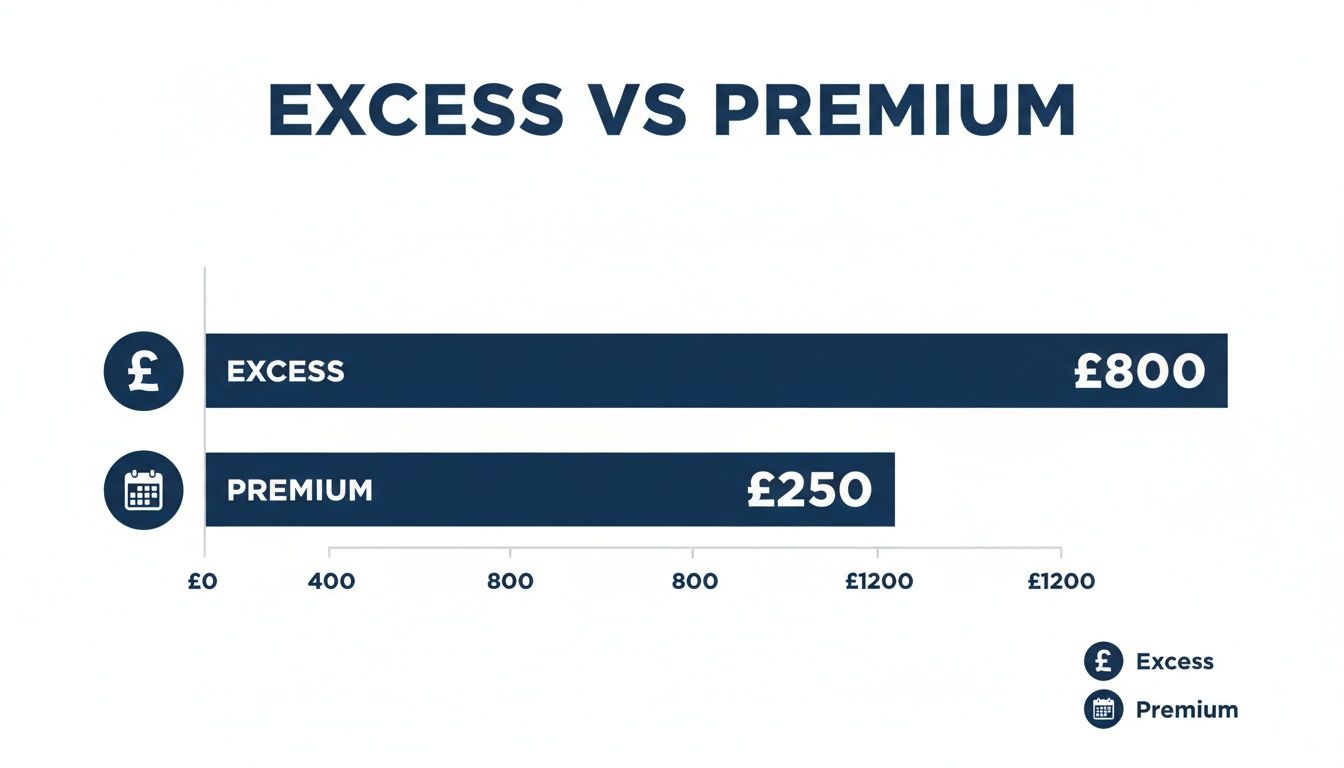
What Is The Difference Between Voluntary And Compulsory Excess
Let’s talk about excess. No, not your wild party habits. We’re diving into insurance excess. That’s the money you pay before your insurer chips in. It sounds dull, but trust m...
Let’s talk about excess. No, not your wild party habits. We’re diving into insurance excess. That’s the money you pay before your insurer chips in. It sounds dull, but trust me—it’s a secret handshake between you and your policy.
The Two Big Bosses: Voluntary vs. Compulsory
There are two types of excess: voluntary and compulsory. They hang out together on your policy, but they have very different jobs. Think of them as a grumpy bouncer and your friendly sidekick.
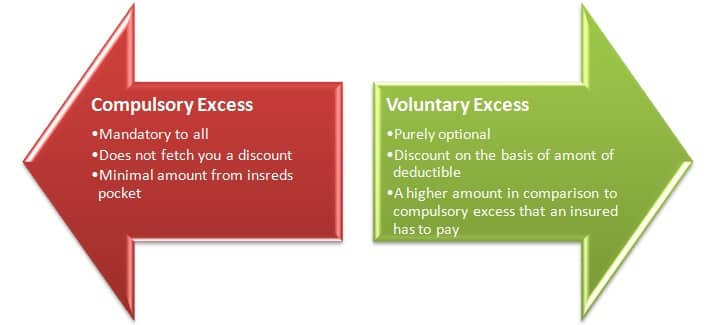
Compulsory excess is the grumpy bouncer. Your insurer sets this amount, and you can’t change it. It’s non-negotiable, like paying for your own socks when you buy shoes.
Must Read
Voluntary excess is your friendly sidekick. You pick this number yourself. Want to save on your premium? Bump it up. Want to pay less if you crash? Keep it low. It’s your secret lever.
The Quirky Dance of Money
Here’s the quirky part: they always add up. If your compulsory excess is $200 and your voluntary is $300, your total bill for a claim is $500. Surprise! You pay both at once.
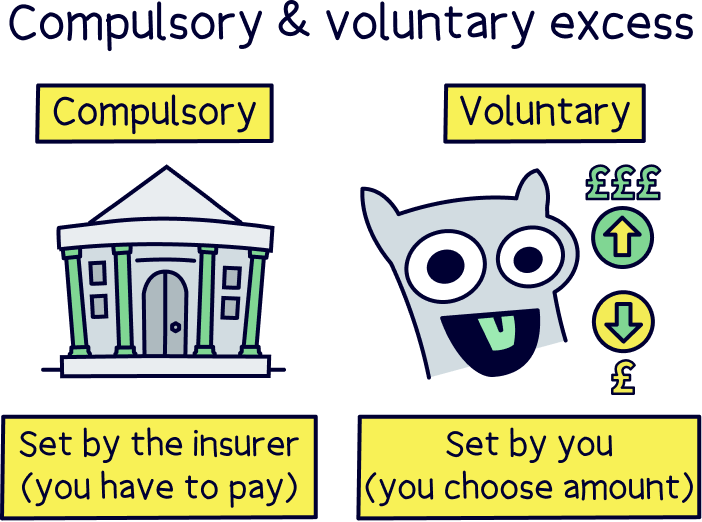 What is compulsory excess? - Nuts About Money
It’s like ordering a pizza. Compulsory is the mandatory cheese. Voluntary is your extra pepperoni. You have to pay for the cheese, but you cleverly chose the pepperoni to lower the pizza’s base price.
Fun fact: raising your voluntary excess can slash your premium by up to 30%. That’s like finding a $20 bill in your winter coat, except it’s every year.
Why This Topic is Weirdly Fun
It’s fun because it’s your choice. Insurance usually feels like homework. But excess? You get to play with numbers and gamble a little. Who knew being an adult could feel like a betting game?
 Compulsory and Voluntary Excess In Motor Insurance
Another gem: some insurers let you set voluntary excess at zero. That means the bouncer (compulsory) works alone. Great if you hate surprises. Terrible if you love saving cash upfront.
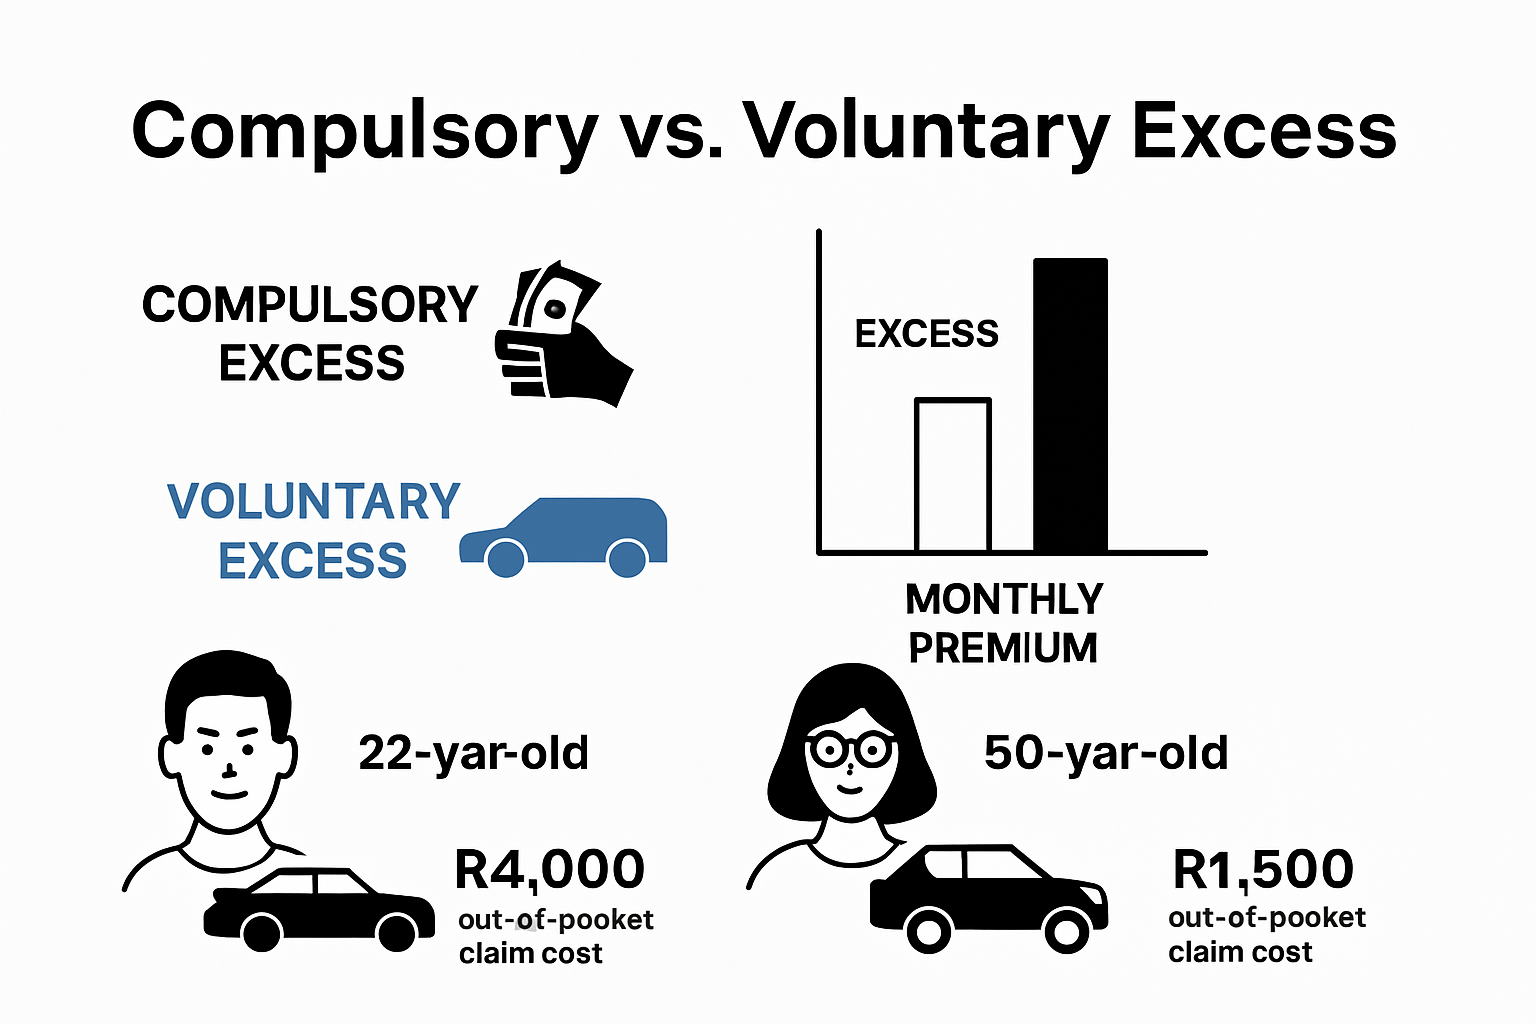
And here’s a funny detail: young drivers often get slapped with a higher compulsory excess. Why? Because insurers know you might drive like a koala on caffeine. Sorry, young speedsters.
 What is Excess in Insurance? Understanding Its Role
The Secret Strategy
Want to be clever? Lower your voluntary excess if you’re a nervous Nelly. You’ll pay a bit more each month, but you’ll have peace of mind. That’s like buying a stress-free bubble.
Feeling brave? Jack up your voluntary excess to, say, $500 or $1,000. Your premium drops like a stone. Just don’t crash your car into a mailbox next week. That’s a $1,000 lesson right there.
Pro tip: always check your insurer’s maximum voluntary excess. Some let you go to $2,000. That’s dangerous if you’re clumsy, but glorious if you’re a safe driver who never parks near shopping carts.
 All About Compulsory and Voluntary Excess in Motor Insurance
The Bottom Line (Without the Boredom)
So, what’s the difference? Compulsory is set in stone by your insurer. Voluntary is your personal dial. Together, they decide how much pain your wallet feels after a fender bender.
Think of it like a see-saw. Balance your premium against your out-of-pocket costs. And remember: you can always ask your insurer, “Hey, can I tweak my voluntary excess?” They’ll probably say yes.
Now go forth and impress your friends at parties. Tell them you’re a voluntary excess wizard. They’ll be amazed—or at least slightly less bored than before.